Clubbing of Income: Four Mistakes That Start With a Gift or a Name on a Document
Clubbing of income means the tax law adds one person’s income to another person’s income. It most often happens within a family, between husband and wife, or between parents and a minor child.
Families usually find out only after the money has moved. A gift to a spouse, an FD in a child’s name, a flat registered in someone else’s name. The money feels like it belongs to the other person. The tax law may not agree.
Under the Income-tax Act 2025 (Tax Year 2026-27), the main rules sit in Section 99 (earlier Section 64).
Note: The people and numbers in the four stories below are illustrative, to explain the rules. They are not real clients.
“Families often ask me where to keep money so that it feels safe. Before that, I ask one question: whose income will the law say it is? That answer should come before the FD, not after the notice.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
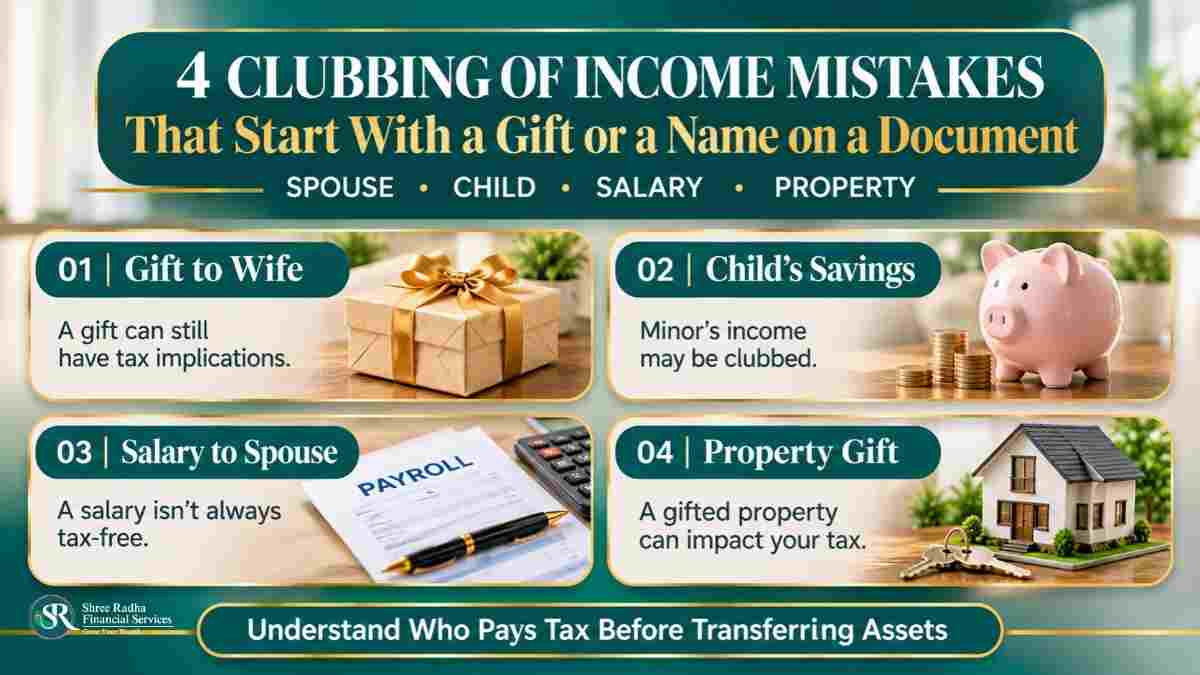
Story 1: Ahmedabad, the Gift to a Homemaker Wife
Amit, 42, is a senior software architect in Ahmedabad. He gifted Rs 25 lakh to his wife, Priya, who is a homemaker. She put it in a fixed deposit at 7.5%. The yearly interest was Rs 1,87,500.
Amit’s thinking was simple. Priya has no income, so the interest would stay below the tax limit.
What went wrong
The gift itself is not the problem. A gift from a husband to a wife is exempt, because a spouse is a “relative” under the gift rules. Our income from other sources guide explains that.
But under Section 99(1)(a)(ii), income from assets transferred to a spouse without adequate consideration is added to the giver’s income. The Rs 1,87,500 interest is taxed with Amit, at his own slab rate. Section 99(5)(d) adds that “income” includes loss.
The right way
Check before you transfer. If the money moves, the income follows the giver. Keep records of who funded what, and ask your CA whether another arrangement, such as the spouse’s own funds or a documented loan on fair terms, fits your case. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully.
Whether income earned on the already-clubbed interest is also clubbed is discussed in several court decisions, but it is not in the Act text. Please confirm with your CA.
Story 2: Lucknow, the Child’s Savings
Sunita and her husband live in Lucknow. The child’s grandparents gifted Rs 5 lakh to their 14-year-old son, Kabir. The parents put it in an FD and a mutual fund in his name. The yearly interest and dividend came to Rs 40,000.
They assumed it was Kabir’s income, taxed in his name, and so below the tax limit.
What went wrong
Under Section 99(1)(c), a minor child’s income is added to a parent’s income. Section 99(5)(b)(i) says it goes to the parent whose total income is higher, when the marriage subsists. Sunita earns more.
Schedule III, Sl. 17 excludes up to Rs 1,500 per minor child. So Rs 40,000 less Rs 1,500 means Rs 38,500 is added to Sunita’s income. Once it is added to one parent, it is not added to the other parent in later years, unless the Assessing Officer is satisfied after hearing the other parent.
The right way
Report the child’s income in the parent’s return. The current ITR-3 has a schedule (Schedule SPI) for income of specified persons such as a spouse or minor child. If a child earns from their own work, skill or talent, or has a disability under Section 154, that income is not clubbed. Whether yield earned on such earnings is clubbed is a point to confirm with your CA. For the investment side, our guardian for minor mutual fund account guide explains the folio rules.
Story 3: Chandigarh, the Salary to the Spouse
Manpreet owns 40% of the shares in his family auto-parts company in Chandigarh. His wife, Simran, has no training in accounts or finance. The company pays her Rs 6 lakh a year as “accounts head”, and she signs a few papers each month.
They felt this was a normal way to share income in the family.
What went wrong
Section 99(1)(a)(i) adds a spouse’s salary or fees from a concern in which the individual has a substantial interest. Substantial interest means 20% or more of the voting power in a company, or at least 20% of the profits in other concerns (Section 99(5)(a)(iii)).
The only exception is income solely attributable to the spouse’s technical or professional knowledge, experience and qualification. Simran does not have these, so the Rs 6 lakh goes to whichever spouse has the higher total income before the inclusion.
The right way
If a spouse really does professional work, for example as a practising CA or doctor with a clear role, the exception may apply. Document the work, the hours and the pay, because clubbing of income applies to the pay where the tests are met. Whether your case qualifies is a CA question, especially when only some of knowledge, experience and qualification are present.
Story 4: Bhopal, the Flat Gifted to a Wife
Rajesh, 50, owns a let-out flat in Bhopal. The rent is Rs 25,000 a month, which is Rs 3 lakh a year. He gifted the flat to his wife, Meena, by a registered gift deed. He expected the rent to be taxed in her hands at a lower rate.
What went wrong
For house property, Section 25(a) treats an individual who transfers a property without adequate consideration to a spouse, or to a minor child other than a married daughter, as the owner. Section 99(1)(a)(ii) is made subject to it. The rent is still taxed with Rajesh. The exception is a transfer under an agreement to live apart.
The right way
Think about tax along with the family reason for the gift. Stamp duty and registration rules differ by state. Our gift deed guide covers Gujarat. For income computation, see our house property guide.
What Clubbing of Income Means Under Section 99
Section 99 of the Income-tax Act 2025 says the total income of an individual includes income arising directly or indirectly to certain family members, in the cases below.
| Situation | Whose income is added | Section |
|---|---|---|
| Spouse’s salary or fees from a concern where you have a substantial interest | The spouse with the higher total income | 99(1)(a)(i), 99(5)(a) |
| Income from assets you transfer to your spouse without adequate consideration | You, the transferor | 99(1)(a)(ii) |
| Income from assets you transfer to your son’s wife (on or after 1 June 1973) | You, the transferor | 99(1)(b) |
| Income of your minor child | The parent with the higher income | 99(1)(c), 99(5)(b) |
| Assets transferred to any person for the benefit of your spouse or son’s wife | You, to the extent of that benefit | 99(1)(d) |
| Your property converted into HUF property without adequate consideration | You, not the HUF | 99(3) |
If the asset you gave your spouse or son’s wife is put into a business or a partnership, only a proportion of the income is added. The share is worked out by the formula in Section 99(2), using the amount invested and the total investment.
For a spouse’s salary, the clubbing of income rule depends on three tests.
| Test | What the Act says | Section |
|---|---|---|
| Substantial interest, company | Shares carrying 20% or more of the voting power, owned by you or jointly with relatives | 99(5)(a)(iii)(A) |
| Substantial interest, other concern | Entitled to at least 20% of the profits, alone or with relatives | 99(5)(a)(iii)(B) |
| Exception | Income solely attributable to the spouse’s technical or professional knowledge, experience and qualification is not added | 99(1)(a)(i) |
Clubbing of Income for a Minor Child: What Is Added and What Is Not
| Child’s income | Added to the parent? |
|---|---|
| Interest, dividend and similar income from investments held in the child’s name | Yes, after the Rs 1,500 per child exclusion |
| Income from work done by the child | No (Section 99(1)(c)(i)) |
| Income from activities using the child’s own skill, talent, specialised knowledge or experience | No (Section 99(1)(c)(ii)) |
| Income of a child with a disability under Section 154 | No (Section 99(1)(c)(iii)) |
The Rs 1,500 amount is in Schedule III, Sl. 17. It may be updated, so please check the current figure with your CA.
| Case | Whose income it joins |
|---|---|
| Parents are married | The parent whose total income, before the inclusion, is higher |
| Parents’ marriage does not subsist | The parent who maintains the child during the tax year |
| In later years | Not moved to the other parent, unless the Assessing Officer is satisfied after giving that parent a hearing |
The Gift Is Exempt, But the Income Is Not
| Step | Tax result |
|---|---|
| Amit gifts Rs 25 lakh to his wife | The gift is exempt, as it is from a relative (Section 92(3)) |
| She earns Rs 1,87,500 interest on an FD | The interest is added to Amit’s income (Section 99(1)(a)(ii)) |
| She earns salary from her own genuine job | Her own income, not clubbed |
Family Property and the HUF
Section 99(3) covers a related situation. If you put your own property into the family pool, for example by throwing it into the common stock of the HUF, without adequate consideration, the income from it is treated as your income. If the property is later divided and your spouse receives a share, the income from that share is treated as arising from assets you transferred to your spouse. Section 99(4) leaves out property converted on or before 31 December 1969.
This matters for family businesses, where clubbing of income can follow a property into the family pool. Our guides on HUF for estate planning and HUF vs private trust explain the structures.
Rules and rates change from time to time. Please confirm with your tax consultant / CA.
| Subject | 1961 Act | 2025 Act |
|---|---|---|
| Transfer of income without transfer of asset | Section 60 | Section 96 |
| Revocable transfer of assets | Sections 61, 62 | Section 97 |
| “Transfer” and “revocable transfer” | Section 63 | Section 98 |
| Clubbing: spouse, minor child, son’s wife, HUF | Section 64 | Section 99 |
| Liability of person for clubbed income | Section 65 | Section 100 |
Official Sources to Read
- Income Tax Department: the Income-tax Act page, Sections 96 to 100 and Section 25.
- e-Filing portal: incometax.gov.in for return forms and schedules.
- AMFI: amfiindia.com for mutual fund scheme information.
Read these along with our guide to SIP for housewives and the mutual fund taxation guide. Planning for a spouse or child becomes easier once you know the rules on clubbing of income.
How SR Wealth Can Help
Shree Radha Financial Services is an AMFI Registered Mutual Fund and SIF Distributor and an APMI Registered PMS Distributor. We are not tax consultants. What we do:
- Explain the products you hold or are considering, such as mutual funds, SIF, PMS and deposits
- Help you keep clear records of who funded which investment, so your CA can handle clubbing of income correctly in your return
- Connect you with a competent CA or tax consultant if you need one for your salary tax, return or notice
Clubbing of Income: Frequently Asked Questions
1. Is a gift to my wife taxable?
The gift is exempt, because a spouse is a relative (Section 92(3)). The income earned on it is added to your income under Section 99(1)(a)(ii).
2. Who pays tax on interest from money I gave my wife?
You do. The interest is added to your total income, whatever the wife’s own income is.
3. Is a minor child’s income taxed with mine?
Yes, in most cases, under Section 99(1)(c). Income from the child’s own work, skill or talent, and income of a child with a Section 154 disability, is not added.
4. Which parent is the income added to?
When the parents are married, to the parent with the higher total income. If the marriage does not subsist, to the parent who maintains the child.
5. How much of a minor child’s income is exempt?
Rs 1,500 per child, as seen in Schedule III, Sl. 17. This may be updated, so please confirm with your CA.
6. Is my child’s earning from acting or sports clubbed?
Income from the child’s own skill, talent or work is not clubbed. Yield on investing that money is a point to confirm with your CA.
7. Can I pay my wife a salary from my company?
If you have a substantial interest (20% or more) and she lacks the relevant knowledge, experience and qualification, the salary is added to the higher-income spouse. A real professional role may be treated differently.
8. What if I gift a house property to my wife?
Under Section 25(a), you are still treated as the owner for house property income, unless the transfer is under an agreement to live apart.
9. Does clubbing apply to gifts to my daughter-in-law?
Yes. Under Section 99(1)(b), income from assets you transfer to your son’s wife without adequate consideration is added to your income.
10. What happens when I put property into the HUF?
Under Section 99(3), income from property you convert into HUF property without adequate consideration is treated as your income.
This article is also available on Medium for wider reading:https://medium.com/@shreeradha.services/the-gift-is-tax-free-but-the-income-is-not-clubbing-of-income-explained-1e93e9eb475a
Planning Your Family’s Investments?
If you want to talk about SIPs, mutual funds, SIF or retirement income planning for your family, connect with Shree Radha Financial Services for a personalized discussion.
📞 Call/WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services, Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN05763
IRDAI Licensed Insurance Distributor
Investing since 2012 | BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN05763). All content is strictly for educational purposes only and does not constitute individualized investment or tax advice. The characters in this article are fictional. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing. Rules and rates change from time to time. Please confirm with your tax consultant / CA. Tax treatment is based on current laws and subject to change.