Income From House Property Under the New Income-tax Act: The Quick Answer
Income from house property is the tax on the rent your buildings earn, or are treated as earning, and it is one of the five heads of income. The Income-tax Act 2025 covers it in Sections 20 to 25, for income earned from 1 April 2026. The first thing to know is which of three types each of your houses is.
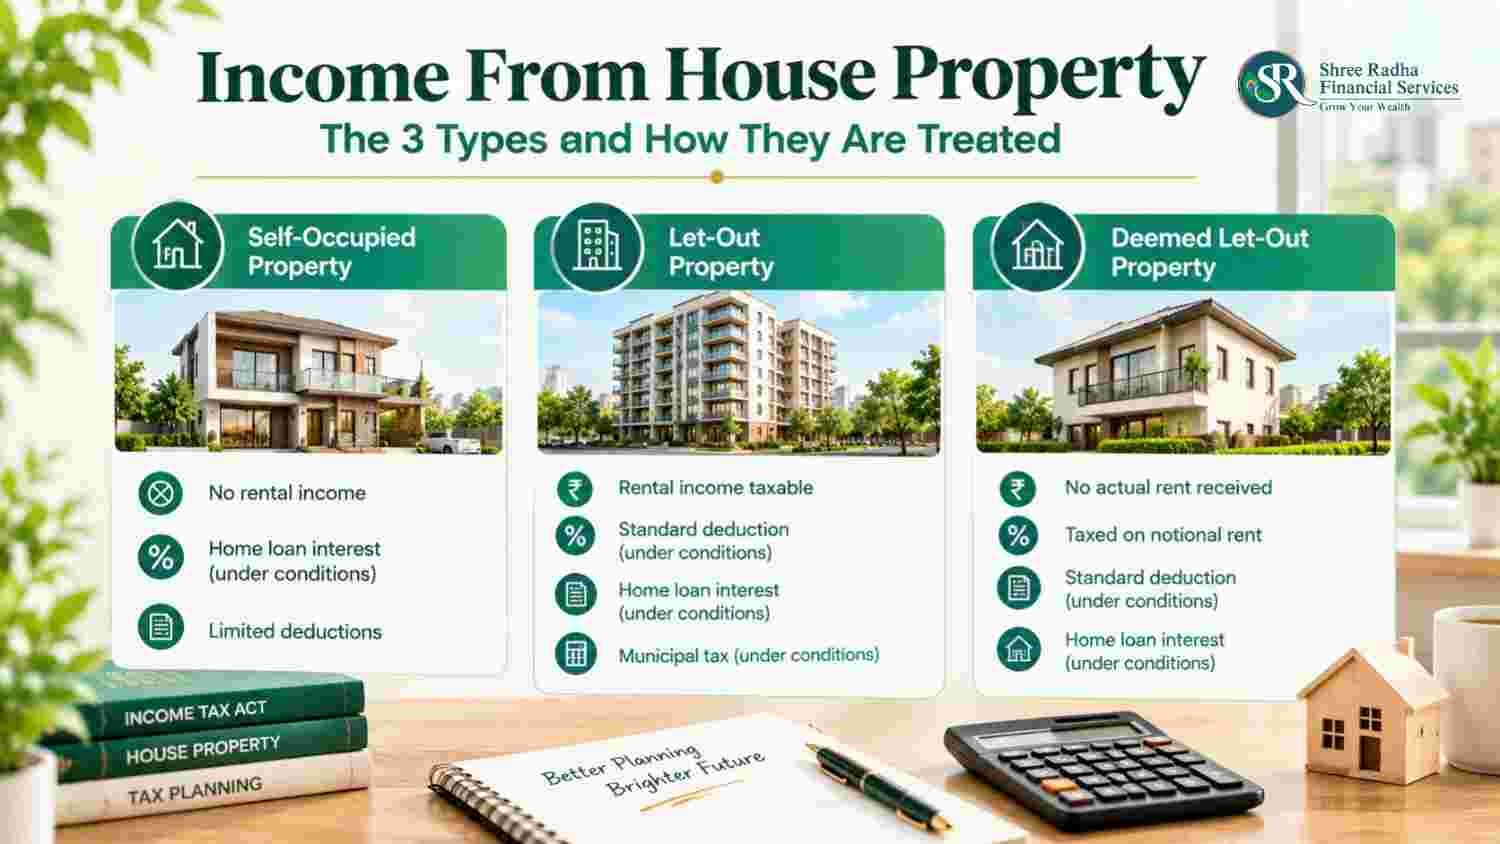
- Self-occupied: you live in it, or cannot occupy it for any reason. Its annual value is nil, for up to two houses.
- Let-out: you rent it. Tax is on the net annual value, after municipal tax paid and a 30% deduction, less your home loan interest.
- Deemed let-out: your third house onwards, if not rented. You are taxed on the rent it could earn, even when no rent comes in.
Co-owners with a joint home loan can each claim their own share, and rent from a house let with furniture or services can be taxed under a different head. The new regime blocks two things that many home loan borrowers expect: the interest deduction on a self-occupied house, and the set-off of house property loss against salary. Rules change from time to time, so please check your own case with your CA or tax consultant.
“Many families buy a second or third flat for the rental income, and only later discover how much of that rent is left after tax, loan interest and vacant months. The after-tax return should be part of the buying decision, not a surprise after it.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
Income From House Property: Which Act and Which Section?
The question: “My CA mentions Section 24 but the new Act has different numbers. Which is right?”
The answer: Income earned up to 31 March 2026 stays under the Income-tax Act 1961. Income from 1 April 2026 falls under the Income-tax Act 2025 as Tax Year 2026-27. The Income Tax Department explains the move in its FAQs on the transition. Our income tax computation guide shows how the heads fit together. Use this table to match the numbers.
| Item | 1961 Act | 2025 Act |
|---|---|---|
| Charge of tax on house property | Section 22 | Section 20 |
| Annual value | Section 23 | Section 21 |
| Deductions (30%, interest) | Section 24 | Section 22 |
| Arrears and unrealised rent | Section 25A | Section 23 |
| Co-owned property | Section 26 | Section 24 |
| Deemed owner | Section 27 | Section 25 |
| Set-off of house property loss | Section 71 | Section 109 |
| Carry forward of house property loss | Section 71B | Section 110 |
| TDS on rent | Sections 194-IB and 194-I | Section 393 (Table, Sl. 2) |
Self-Occupied, Let-Out and Deemed Let-Out Property: The 3 Types
Every house you own falls into one of three types, and the type decides what you pay. Section 21(6) gives a nil annual value to a house you live in, or cannot actually occupy for any reason. Section 21(7) limits this to two houses of your choice. It also says the relief does not apply to a house that is let at any time in the year or gives you another benefit.
| Self-occupied | Let-out | Deemed let-out | |
|---|---|---|---|
| Who it is for | Your own home, or a house you cannot occupy for any reason (up to two) | A house you rent out | Your third house onwards that is not let |
| Annual value | Nil | Higher of expected rent and actual rent, less municipal taxes you paid | Expected rent, less municipal taxes you paid |
| 30% standard deduction | Not applicable (annual value is nil) | Yes, on the net annual value | Yes, on the net annual value |
| Home loan interest | Up to ₹2 lakh (₹30,000 in some cases), old regime only | Allowed in full, in both regimes | Allowed in full, in both regimes |
| Can there be a loss? | Yes, from interest (old regime only) | Yes, if interest is more than income | Yes, if interest is more than income |
A house held as stock-in-trade by a builder has its own rule in Section 21(5), and a part of a house used for your own business is outside the head of income from house property (Section 20). This guide is for ordinary owners.
Let-Out Property Income: Sanjay’s Flat in Nagpur
Sanjay owns a flat in Nagpur and rents it out for ₹25,000 a month. He pays municipal tax of ₹12,000 a year and home loan interest of ₹1,40,000. He thought, “I get ₹3 lakh rent, so ₹3 lakh is my income.”
The mistake: taxing the full rent, and forgetting the deductions.
The way forward: start with the annual value. It is the higher of the rent a similar house could reasonably fetch and the actual rent (Section 21(1)). Subtract municipal taxes that you actually paid in the year (Section 21(3)). Then take 30% of the result and subtract the loan interest (Section 22).
| Sanjay, Nagpur (let-out flat) | Amount |
|---|---|
| Rent received for the year (₹25,000 a month) | ₹3,00,000 |
| Less municipal tax paid by Sanjay | ₹12,000 |
| Net annual value | ₹2,88,000 |
| Less 30% standard deduction | ₹86,400 |
| Less home loan interest | ₹1,40,000 |
| Income from house property | ₹61,600 |
Sanjay’s taxable income from house property is ₹61,600, and not ₹3 lakh. If his tenant paid municipal tax, he could not deduct it, because only the owner’s payment counts.
If part of the year the flat was empty, Section 21(2) limits the annual value to the rent actually received for that year. If the rent is above ₹50,000 a month, TDS rules apply, which we cover below.
Self-Occupied Property and Home Loan Interest: Nisha’s Flat in Bengaluru
Nisha lives in her own flat in Bengaluru. She pays ₹2,60,000 of home loan interest in a year, and her salary is in the 30% slab.
The mistake: assuming all ₹2.6 lakh of interest reduces her tax.
The way forward: for a self-occupied house, interest is capped at ₹2 lakh if the loan was for buying or building it, the work was finished within five years of the end of the tax year of borrowing, and the lender gives a certificate. For other cases, such as repairs, the cap is ₹30,000 (Section 22(2)).
| Nisha, Bengaluru (self-occupied) | Old regime | New regime |
|---|---|---|
| Home loan interest paid in the year | ₹2,60,000 | ₹2,60,000 |
| Interest allowed (Section 22(2)) | ₹2,00,000 (cap) | Nil |
| House property loss | ₹2,00,000 | Nil |
| Set-off against salary (Section 109, up to ₹2 lakh) | ₹2,00,000 | Not allowed |
| Tax saved at the 30% slab with cess | About ₹62,400 | Nil |
| Interest that gives no benefit | ₹60,000 | ₹2,60,000 |
In the old regime, Nisha’s loss of ₹2 lakh can be set off against her salary (Section 109, up to ₹2 lakh), saving about ₹62,400. In the new regime, there is no interest deduction on a self-occupied house (Section 202(2)). So her choice of regime changes her home loan benefit. Our old vs new tax regime guide shows how to compare the two.
If you live in a rented flat in one city and your own flat is in another, that flat may qualify as a house you cannot actually occupy. Ask your CA about your facts.
Deemed Let-Out Property: Vikram’s Third House in Jaipur
Vikram, in Jaipur, owns three houses. He lives in one. The second is his late father’s home, which he inherited and keeps vacant. The third is a flat he bought as an investment and is still looking for a tenant.
Vikram said, “I earn no rent from the third flat, so I pay no tax on it.” His CA disagreed.
The mistake: believing “no rent, no tax”.
The way forward: Section 21(7) lets you choose two houses to treat as self-occupied. Vikram should choose the two that give him the best result, and the third is a deemed let-out property. It is taxed on the rent it could earn.
| Vikram, Jaipur (third house, vacant) | Amount |
|---|---|
| Expected yearly rent (₹20,000 a month) | ₹2,40,000 |
| Less municipal tax paid | ₹6,000 |
| Net annual value | ₹2,34,000 |
| Less 30% standard deduction | ₹70,200 |
| Less home loan interest on this flat | ₹1,00,000 |
| Income taxed, with no rent received | ₹63,800 |
Vikram is taxed on ₹63,800 even though no rent came in. Since the third flat is not a self-occupied house, its loan interest is allowed in full and is not held to the ₹2 lakh cap. Once he finds a tenant, the actual rent will be used if it is higher than the expected rent.
Note that a house that is let at any time in the year cannot be one of your two (Section 21(7)).
Co-Owned Property, Arrears and Unrealised Rent: Hasmukh and Reena in Ahmedabad
Hasmukh and Reena own a flat in Ahmedabad in equal shares. The rent is ₹40,000 a month. The tenant paid for 10 months and then stopped for 2 months.
The mistake: one of them reporting all the rent, and both ignoring the unpaid months.
The way forward: when co-owners have definite shares, each is taxed on their own share (Section 24). Rent that cannot be recovered is left out of actual rent if the conditions in Rule 21 of the Income-tax Rules 2026 are met: a genuine tenancy, the tenant has left or steps are taken to evict, the tenant has no other property of yours, and you took reasonable legal steps or would find them useless.
| Hasmukh and Reena, Ahmedabad (50:50 co-owners) | Each owner |
|---|---|
| Share of rent received (10 months at ₹40,000, halved) | ₹2,00,000 |
| Less municipal tax paid by each | ₹8,000 |
| Net annual value | ₹1,92,000 |
| Less 30% standard deduction | ₹57,600 |
| Income from house property | ₹1,34,400 |
| Next year: share of the 2 months of unrealised rent received (₹40,000), after 30% | ₹28,000 taxable (Section 23) |
If the unpaid rent is recovered later, it is taxed in the year you receive it, with a 30% deduction (Section 23). The next section shows how this works for a joint home loan.
Co-Owner and Co-Borrower: Who Claims the Home Loan Deduction?
Arjun and Meera in Chennai took a joint home loan and live in the flat. Arjun said, “Only one of us can claim the interest, right?” That is a common belief, and it is not correct for co-owners.
The mistake: one spouse claiming the whole interest and the other claiming nothing.
The way forward: when both are co-owners with definite shares and both are co-borrowers who pay the EMI, each can claim the deduction on their own share. Each also gets the ₹2 lakh self-occupied limit separately (Section 24(2)).
| Arjun and Meera, Chennai (joint loan, self-occupied, 50:50) | Sole owner | Co-owners |
|---|---|---|
| Home loan interest in the year | ₹4,00,000 | ₹4,00,000 (₹2,00,000 each) |
| Interest allowed in the old regime (cap ₹2 lakh each) | ₹2,00,000 | ₹2,00,000 + ₹2,00,000 = ₹4,00,000 |
| Interest allowed in the new regime | Nil | Nil |
As a sole owner, Arjun would have got ₹2 lakh of interest relief in the old regime. As co-owners, Arjun and Meera claim ₹4 lakh together. This works only in the old regime, because the new regime gives no self-occupied interest deduction to either of them.
| Situation | What happens |
|---|---|
| Both are co-owners and co-borrowers, both pay the EMI | Each is taxed on their own share (Section 24(1)). Each gets the self-occupied relief separately (Section 24(2)). Each can claim interest on their own share, up to ₹2 lakh each for a self-occupied house in the old regime. |
| Both are co-owners, but only one repays the loan | Keep the lender’s certificate and proof of who paid each EMI. Ask your CA how to split the claim. It should follow ownership and actual payment. |
| A parent is a co-borrower only, for loan eligibility, and is not on the sale deed | The interest deduction goes against income from the property, which belongs to the owner. A co-borrower who is not an owner generally cannot claim it. Please confirm with your CA. |
| A let-out house owned jointly | Each reports their own share of rent, municipal tax paid and interest. The ₹2 lakh loss set-off limit applies to each person separately in the old regime. |
Keep the ownership share in the sale deed, the share of the loan and the share of rent (if let) in line with each other. Ask the lender for an interest certificate that shows each borrower’s share, and pay your EMI share from your own bank account. Please confirm the details with your CA.
House With Services, Furniture or Other Assets: How the Rent Is Treated
Not every rent is house property income. The answer depends on what you are letting out and what else you give the tenant.
The question: “I let my flat with furniture and charge maintenance. Is it all house property?”
The way forward: a simple letting of a residential house is always house property, even if the rent includes services such as maintenance (Section 26(4)). The treatment changes when you also let out other assets, or run a service business.
| Case | Where the income is taxed | Reference |
|---|---|---|
| Residential house let out, rent includes maintenance or parking | Income from house property | Section 26(4) |
| Residential house let with furniture, with the furniture rent fixed separately | Building rent: house property. Furniture rent: other sources | Section 92(2)(f) |
| Building let with machinery, plant or furniture, and the letting of the building cannot be separated (a fully equipped factory or office) | The whole income: other sources, unless it is business income | Section 92(2)(g) |
| Shop or office let out, owner only collects rent | Generally income from house property | Section 20 |
| Serviced apartment, guest house, paying-guest house or co-working space with housekeeping, meals or reception | Generally business or profession income. The 30% deduction is not used | Ask your CA |
| Part of your own house used for your business or profession | That part is outside house property | Section 20(2) |
| Flats held as stock-in-trade by a builder, not let | Annual value is nil for up to the period in Section 21(5) | Section 21(5) |
If the furniture or machinery rent is not separable from the building rent, the whole income can move out of house property. If it is separable, the building rent and the furniture rent are taxed under different heads. These are the cases where a CA’s view matters most, so please share your tenancy agreement with them.
Other Situations: How Each One Is Treated
Here is a quick guide to the cases readers ask about most.
| Situation | How it is treated |
|---|---|
| Part of a house let, part self-occupied | Treat each part separately. Section 21(6) covers “a house or any part of it”. |
| House let to a relative or an employee at a very low rent | The annual value is the higher of expected rent and actual rent (Section 21(1)), so a low rent does not lower the tax. |
| Let house vacant for part of the year | The annual value is the actual rent received if the vacancy reduced it (Section 21(2)). |
| Rent the tenant never pays | Left out if the Rule 21 conditions are met (Section 21(4)). Taxed in the year you recover it (Section 23). |
| Principal repayment of a home loan | May qualify under Section 123 in the old regime, within the ₹1.5 lakh limit. |
| Extra interest deduction for first-time buyers | Section 131 applies only to loans sanctioned from 1 April 2019 to 31 March 2022, with conditions. It works in the old regime only. |
| GST on rent, or tax when you sell | These are separate subjects. Ask your CA. |
House Property Loss: Set-Off and Carry Forward
The question: “My interest is more than my rent. Can I use the loss against my salary?”
- Old regime: loss from house property can be set off against other heads of income up to ₹2 lakh in a year (Section 109).
- The balance: it is carried forward for 8 years, to be set off against house property income only (Section 110).
- New regime: no set-off of house property loss against other heads (Section 202(2)). As we read the Act, the loss can still be carried forward. Please confirm with your CA.
| House type | Old regime | New regime |
|---|---|---|
| Self-occupied: interest | Up to ₹2 lakh (Section 22(2)) | Not allowed (Section 202(2)) |
| Let-out or deemed let-out: interest | Allowed in full | Allowed in full |
| Loss set off against salary or other income (Section 109) | Up to ₹2 lakh | Not allowed (Section 202(2)) |
| Loss carried forward for 8 years against house property income (Section 110) | Yes | As we read the Act, yes (confirm with your CA) |
Carry-forward of a loss under income from house property needs a return filed on time, and the same rule applies to other losses. Our salary income guide shows what else counts in the salary head.
Pre-Construction Interest: Claiming It in 5 Instalments
If you took a loan before the house was complete, the interest you paid during construction is not lost. It is added up and claimed in five equal yearly instalments, starting in the year the house is completed (Section 22). For a self-occupied house, it forms part of the overall ₹2 lakh cap together with the current year’s interest. Ask your lender for a yearly interest certificate and keep it with your records.
Who Is the Owner? Gifts to Spouse and Minor Child
Section 25 widens the meaning of “owner” for this head. If you give a house to your spouse (outside a separation) or to a minor child without adequate payment, the income can still be taxed in your hands. It also covers a society allottee and a buyer holding a lease of 12 years or more. So putting a house in your spouse’s name does not by itself move the tax. Our Will in Gujarat guide covers planning ownership in the family.
TDS on Rent: What Landlords and Tenants Should Know
TDS on rent sits in the Section 393 table. The rent is still house property income in your hands, and the TDS is only an advance that you claim in your return.
| Tenant | TDS on rent (Section 393) | When |
|---|---|---|
| Individual or HUF, not subject to audit | 2% if rent is above ₹50,000 a month | Once, in the last month of the tax year or of the tenancy; Form 141 (earlier Form 26QC) |
| Business or professional tenant (specified person) | 10% on land and building rent, 2% on machinery, if rent is above ₹50,000 a month | Under the usual TDS due dates |
Check TDS entries against your e-Filing portal data before you file. Rent from a shop or office is generally house property income as well. If letting is itself your business, with services, it can be business income, so please ask your CA.
7 Common Mistakes With House Property Income, and the Way Forward
- Mistake: “No rent, no tax” on a third house. Way forward: pick your best two houses as self-occupied, and calculate expected rent for the rest.
- Mistake: claiming self-occupied interest in the new regime. Way forward: check your regime first.
- Mistake: taking 30% of the rent received. Way forward: take it on the net annual value, after municipal tax you paid.
- Mistake: deducting municipal tax the tenant paid. Way forward: only the owner’s payment in the year counts.
- Mistake: expecting a big loss to cut salary tax. Way forward: remember the ₹2 lakh limit, the 8-year carry-forward, and no set-off in the new regime.
- Mistake: ignoring unrealised rent and arrears. Way forward: check the Rule 21 conditions, and note the tax when the rent is recovered.
- Mistake: thinking a house in a spouse’s name moves the tax. Way forward: check Section 25 with your CA.
House Property Income Checklist
- List all your houses and mark each as self-occupied, let-out or deemed let-out.
- Choose your two self-occupied houses carefully.
- Collect rent receipts, tenancy agreements and municipal tax receipts.
- Get the lender’s interest certificate for each loan, with the pre-construction details.
- Compute the net annual value and the 30% deduction for each let house.
- Check your regime before counting self-occupied interest.
- Check co-ownership shares and who pays what.
- Match TDS on rent with the data on the portal.
- Track any house property loss for carry-forward.
- Share the final numbers with your CA before filing.
Who Can Use This Guide, and Who Should Take Extra Help
This guide works well for:
- Home loan borrowers who live in their own house
- Investors who rent out a flat or a shop
- Families with a second or third property, including inherited ones
- Retired couples who depend on rent, along with our retirement planning guide and retirement schemes guide
You should take extra help from a CA if:
- You own a property while living abroad. Our NRI investment guide covers SIF, PMS and AIF rules, and your CA should confirm the tax position.
- You let out through a business or a company
- You are selling a house, since capital gains rules apply
- Your tenant has stopped paying, or you have received a tax notice
How SR Wealth Can Help
Shree Radha Financial Services (SR Wealth) is an AMFI Registered Mutual Fund and SIF Distributor and an APMI Registered PMS Distributor. We are distributors, not tax consultants. Your CA or tax consultant should confirm your income from house property and your return.
What we can do for you:
- Help you look at how a home loan or a rental property fits with your savings and SIPs
- Explain, in general terms, how investment income is taxed, so you can compare it with rental income
- Connect you with a competent CA or tax consultant if you need one for your property tax, return or notice
Rules and regulations change from time to time, so please connect with your CA or tax consultant for your own situation.
Income From House Property FAQ
Can I claim home loan interest in the new tax regime for a self-occupied house?
No. Section 202(2) does not allow the interest deduction on a self-occupied house in the new regime. Interest on a let-out house is still allowed.
What happens if I own three houses?
You choose two to treat as self-occupied, with nil annual value. The third is a deemed let-out property, and expected rent is taxed (Section 21(7)).
How is the rent of a deemed let-out property worked out?
It is the sum the house might reasonably be expected to fetch from year to year (Section 21(1)(a)). You subtract municipal taxes you paid and the 30% deduction, and then the loan interest.
Is house property loss allowed against salary in 2026-27?
In the old regime, up to ₹2 lakh a year (Section 109). In the new regime, no. The balance can be carried forward for 8 years against house property income (Section 110).
How much home loan interest can I claim on a let-out property?
The whole interest is allowed against the rent. The loss you can set off against other income is limited as above.
Can both husband and wife claim ₹2 lakh on a joint home loan?
Yes, if both are co-owners with definite shares and both are co-borrowers who pay. Each gets the self-occupied relief separately (Section 24(2)) in the old regime, so a couple can claim up to ₹4 lakh together. A co-borrower who is not an owner generally cannot claim. Please confirm with your CA.
Is municipal tax deductible if the tenant pays it?
No. Only taxes actually paid by the owner during the tax year reduce the annual value (Section 21(3)).
Is rent from a shop house property income?
Generally yes, with the 30% deduction. If letting is itself your business with services, it can be business income, so ask your CA.
Is rent for a house with furniture or services taxed as house property?
Rent from a residential house stays house property even if it includes maintenance (Section 26(4)). Furniture, plant or machinery let on hire can fall under other sources (Section 92(2)(f) and (g)), and serviced accommodation is generally business income.
Is TDS cut on rent?
Yes, if the rent is above ₹50,000 a month: 2% from an individual tenant, and 10% on land and building rent from a business tenant (Section 393).
This article is also available on Medium for wider reading: [add Medium link after publishing]
Buying or Letting a Second Home? Plan the Money Side First
A second house affects your loan, your savings and your SIPs long before it affects your tax return. Before you commit, talk to us about how it fits with your investments and your goals. For anything about your property tax, your CA is the right person, and if you do not have one, we can connect you with a competent CA.
📞 Call / WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services (SR Wealth), Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN: 05763
IRDAI Licensed Insurance Distributor
BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Last verified on 27 October 2026 against the Income-tax Act 2025 (as amended by Finance Act 2026), the Income-tax Rules 2026 and the Income-tax Act 1961. Official sources: Income Tax Department, the e-Filing portal and the Income Tax Department website for the Rules.
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN: 05763). It is for education only and is not tax, legal or investment advice. Tax rules, rates, limits and section numbers change from time to time. Please connect with your tax consultant or CA for details specific to your situation. The people in the stories are fictional and the numbers are illustrations only. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully.