Retirement Schemes in India: Why Six Products Feel So Confusing
Most retirement schemes in India look the same from outside. They all promise “pension”, “tax saving” and “a safe future”. But inside, they do very different jobs.
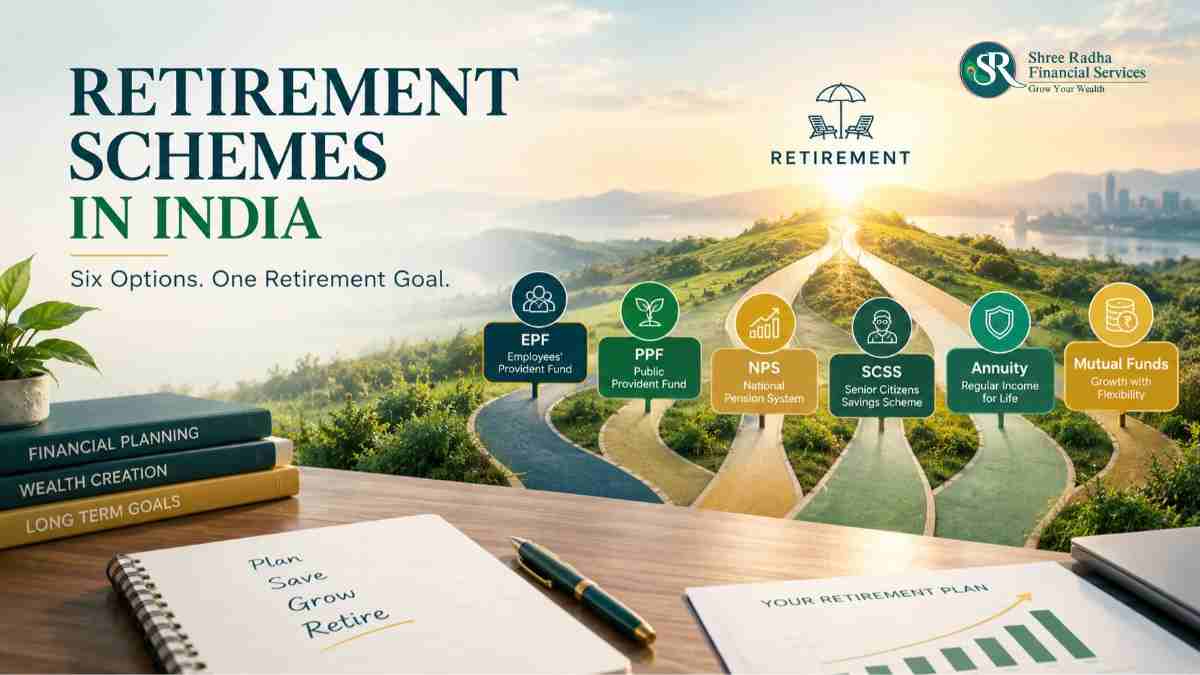
EPF, PPF, NPS, SCSS, annuity and mutual funds. Many families hold two or three of these retirement schemes without knowing why. Some overlap. Some leave gaps. And a few were picked only because a colleague, an agent or a bank manager mentioned them.
This guide on retirement schemes is for salaried people, business owners and retirees who want one clear picture. No jargon. No ranking of “best” and “worst”. Just what each scheme is for, how it is taxed at every stage, and where your own money fits.
“I meet families in Surat every week who own four or five retirement products and still cannot tell me what their monthly income will be at 60. The problem is rarely too little money. It is that nobody told them what each product is meant to do, or how it is taxed when the money finally comes out.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
Retirement Schemes: The One Idea That Makes It Simple
Think of your retirement money as three buckets. Each bucket has a different job.
- Safety bucket: money that should not fall in value. Examples: EPF and PPF.
- Growth bucket: money that has time to grow, and can go up and down on the way. Examples: NPS and mutual funds.
- Income bucket: money that pays you regularly after you stop working. Examples: SCSS, annuity, and mutual fund SWP.
Good retirement schemes planning usually uses more than one bucket. The right mix depends on your age, your job, your family and your comfort with ups and downs. That is why the same scheme can suit one person and not another. Let us see how these retirement schemes work out for three families.
Retirement Schemes Story 1: Hitesh in Surat, “The Business Is My Pension”
Hitesh is 38. He runs a textile trading business in Varachha, Surat. The business has grown every year since 2013, and that made him confident. One Sunday evening, while counting cloth bales at his godown, his CA friend asked a simple question: “Hitesh, what will your monthly income be at 60 if the shop is not there?”
Hitesh laughed. “Arre, the shop is my pension. And PPF? Seven percent? My business gives me three times that.”
He carried three beliefs, and he had never questioned any of them. First, business returns will always beat any scheme. Second, NPS is a trap because “the money is locked till 60”. Third, with no employer, retirement schemes were not really meant for people like him. Years ago he had opened a PPF account, put in ₹50,000 once, and forgotten about it.
His friend then asked two uncomfortable things. What if a big buyer defaults? What if health stops him from working for a year? Hitesh went quiet. Stock, two plots, the shop, even his gold: almost everything he owned was tied to one business. There was no steady pot sitting outside it. Sooner or later, every business owner has to ask which retirement schemes sit outside the business.
That was his mistake, and it is a common one among Surat traders. Business returns are not low. But they come with business risk, and retirement needs a floor that does not depend on the shop.
When he walked into our Dindoli Road office the next week, the conversation went like this. PPF is not meant to beat his business. It is meant to be the one pot that a bad season cannot touch. And its tax story is the best of all retirement schemes: the money you put in can earn a deduction under the old tax regime, the interest is tax-free, and the final maturity amount is tax-free. That is EEE. Under the new regime the deduction on your contribution is not available, but the interest and maturity stay tax-free.
Because Hitesh is self-employed, no employer adds a share. Nobody matches his contribution. The discipline has to come from him. For NPS, a self-employed person’s own contribution can earn a deduction of up to 20% of gross income under the old regime, within the overall limit. And yes, NPS is locked until exit age, but for someone who spends every spare rupee on stock, that lock is exactly the discipline he lacked.
Hitesh did not buy everything that day. He restarted his PPF with a fixed date every year, and asked for the NPS exit rules in writing before deciding anything further. For someone in his situation, these are the retirement schemes usually discussed first.
Retirement Schemes Story 2: Neha in Vadodara and Her Cousin Rohan in Government Service
Neha is 34 and works for an IT company in Vadodara. Her salary slip shows EPF every month, so she felt she was “done with retirement”. At a family function in Ahmedabad she met her cousin Rohan, 36, who works in a state government office.
“Rohan, my company gave an NPS form,” she said. “I tore it up. EPF is enough, no?”
Rohan frowned. “My department puts money into my NPS every month. You are saying no to free money?”
Neha had two beliefs. First, NPS is “just another EPF”. Second, every March she put ₹1.5 lakh into PPF and tax-saving funds because “that saves my tax”. What she had not noticed was that her payroll team had defaulted her to the new tax regime in April. Her March investments were saving her no tax at all.
On a WhatsApp video call a few days later, the pieces were put in order, the way it works for most private employees.
Among her retirement schemes, EPF has a clear job: safety. The share she contributes earns a deduction only under the old regime. Her employer’s share is not taxed in her hands up to 12% of her basic salary and dearness allowance. The growth is tax-free up to a yearly limit, and the final withdrawal after five years of continuous service is fully tax-free. So EPF is EEE, with conditions.
NPS is a different bucket. If her employer offers NPS, its own contribution can be deducted under both regimes, up to 14% of basic plus dearness allowance for a private employee under the new regime and 10% under the old. Her own NPS contribution, though, is deductible only under the old regime. So the torn form might have been a lost benefit, if her company allows it. That depends on her employer’s policy.
Rohan’s case is different, and it shows how retirement schemes treat government and private employees differently. A central or state government employer can contribute up to 14% of salary, and it is deductible under both regimes. At exit, a government employee takes up to 60% as a lump sum and uses the rest for an annuity. Neha, as a private-sector subscriber, can now take up to 80% as a lump sum under the December 2025 PFRDA rules. Whether the extra 20% is tax-free is a separate question. As things stand, only 60% is exempt under current tax law.
The correction for Neha was simple. She had been buying PPF and tax-saving funds for a tax deduction she was not getting. Those retirement schemes can still be useful for their job, safety and growth, but the purchase should be for that job, not for a deduction that does not exist in her regime. She and her CA then compared the two regimes with her actual numbers before April.
Retirement Schemes Story 3: Dilipbhai in Rajkot and the ₹60 Lakh Question
Dilipbhai is 61. After 28 years in an engineering firm in Rajkot, he retired. His EPF came to him as a lump sum, fully tax-free because he had served well over five continuous years. Together with gratuity, the total was about ₹60 lakh.
His wife Kokila asked the question every retiree asks. “Now what do we live on?”
Dilipbhai had three beliefs. An agent had told him, “Put everything in an annuity and relax, pension for life.” A neighbour had told him that SCSS gives 8.2%, “better than any bank”. And he assumed that all government-backed retirement schemes are tax-free, just like PPF.
Over a phone call, since we have no office in Rajkot, each belief was gently tested.
The annuity does give a lifelong income. But the money is handed to the insurer and is difficult to take back, and the pension is fully taxable at his slab rate. The payout also depends on his age, the option he picks and the insurer. Putting all ₹60 lakh there would leave nothing for a hospital bill or a daughter’s wedding.
SCSS is government-backed, but it has a ₹30 lakh limit per person. The interest is paid every quarter and is taxable. So it is not EEE at all. It follows an E-T-E pattern: the amount you deposit can earn a deduction under the old regime, the interest is taxed each year, and the principal comes back to you with no extra tax.
Among all retirement schemes, the tax-free label fits PPF and, with conditions, EPF. It does not fit SCSS, annuity income or mutual fund withdrawals. In an SWP, only the gain portion of each withdrawal is taxed.
One more number changed the mood in the room. If their monthly expense of ₹50,000 rises by 6% a year, they would need about ₹1.6 lakh a month after 20 years for the same life. A fixed income alone does not grow.
Dilipbhai did not look for the “best” scheme after that. He and Kokila split the money into three jobs: a steady-income pot, a lifelong-income pot after comparing written annuity quotes, and a flexible pot for emergencies and inflation. They also asked their CA to estimate the tax on the interest before signing anything. They chose a mix they could explain to each other in two minutes.
What Is EEE? Retirement Schemes and Tax in Plain Words
Tax is where retirement schemes differ the most. EEE stands for Exempt, Exempt, Exempt. It describes three moments in the life of your money:
- First E: when you put money in, you get a deduction.
- Second E: while it grows, the interest or growth is not taxed.
- Third E: when you take it out, the amount is not taxed.
Among all retirement schemes, only PPF is fully EEE in the real sense. EPF is EEE with conditions. NPS is exempt in the first two stages and only partly exempt at exit. SCSS is taxed in the middle. Annuity income and mutual fund gains are taxed when you receive them.
The Income-tax Act, 2025 came into effect on 1 April 2026. The old Section 80C basket (limit ₹1.5 lakh) now sits in Section 123. Earlier this was Section 80C under the 1961 Act. Section 123 benefits are available only under the old tax regime. You can see the law on the Income Tax Department website.
Retirement Schemes EEE Scorecard: Contribution, Growth and Final Withdrawal
| Scheme | Your contribution | Employer contribution | Interest or growth | Final withdrawal | EEE? |
|---|---|---|---|---|---|
| PPF | Old regime: deduction under Section 123. New regime: none | Not applicable. No employer share in PPF | Tax-free in both regimes | 100% tax-free at maturity | Yes, EEE (deduction only in old regime) |
| EPF | Old regime: deduction under Section 123. New regime: none | Not taxed in your hands up to 12% of basic plus DA. If employer contributions to EPF, NPS and superannuation together exceed ₹7.5 lakh a year, the excess and its interest are taxable | Tax-free on your contribution up to ₹2.5 lakh a year (₹5 lakh where there is no employer contribution). Interest on the excess is taxable | 100% tax-free after 5 years of continuous service. Before 5 years it can be taxable, and TDS may apply above ₹50,000 | EEE with conditions |
| NPS | Old regime: counts within the overall ₹1.5 lakh limit (earlier 80CCD(1)), plus an extra ₹50,000 under Section 124(3) (earlier 80CCD(1B)). New regime: none | Section 124(1)-(2) (earlier 80CCD(2)), works in both regimes. Private employer: up to 10% of basic plus DA (old regime), 14% (new regime). Government employer: up to 14% in both | No tax while it grows inside NPS | 60% lump sum is tax-free. The annuity part is not taxed when bought, but the pension is taxable. For private subscribers, the extra 20% permitted by PFRDA may be taxable | Partly (E-E, then part tax-free) |
| SCSS | Old regime: deduction under Section 123. New regime: none | Not applicable | Interest is taxable at your slab rate every year | Principal comes back with no extra tax | No (E-T-E) |
| Annuity | Depends on the plan. From NPS money, no tax on purchase | An employer-linked annuity depends on the employer’s plan | Not applicable | Pension is fully taxable at your slab rate | No |
| Mutual funds | No deduction, except tax-saving funds under Section 123 (old regime) | Not applicable | No tax until you sell | Equity funds: gains above ₹1.25 lakh a year taxed at 12.5% if held over 12 months; shorter holding is taxed at 20%. Other fund types differ | No, taxed only on gains |
Tax treatment of these retirement schemes depends on your regime, income, holding period and employer policy. Please confirm the exact position for your case with your tax consultant or CA.
Retirement Schemes for Government and Private Employees: What Changes
| Point | Private employee | Government employee |
|---|---|---|
| Provident fund | EPF with employer share. ₹2.5 lakh yearly limit on tax-free interest | GPF (for those under the old pension) has no employer share, so the limit is ₹5 lakh |
| Employer NPS deduction | Up to 10% (old regime) or 14% (new regime) of basic plus DA | Up to 14% in both regimes |
| NPS exit | Up to 80% lump sum and at least 20% annuity (corpus above ₹12 lakh) | Up to 60% lump sum and the rest for annuity |
| Tax-free part at exit | 60% under current tax law. Confirm the extra 20% | 60% |
Retirement Schemes Explained One by One
Rates and limits for these retirement schemes were last verified on 26 October 2026. They can change.
EPF (Employees’ Provident Fund)
What it is: A retirement fund for salaried employees. A part of your salary goes in every month and your employer adds a matching amount. Read the rules on the EPFO website.
Rate: Declared every year. For FY 2025-26 it is 8.25%.
Withdrawals: From October 2025, EPFO merged 13 partial-withdrawal reasons into three groups: essential needs, housing needs and special circumstances. A 25% minimum balance must stay in the account, and 12 months of service are needed.
Suits this kind of situation: Salaried employees in covered establishments.
PPF (Public Provident Fund)
What it is: A long-term government savings scheme you can open at a bank or post office. Details are on the India Post website.
Rate: 7.1% for October to December 2026. The government reviews it every quarter.
Lock-in: 15 years. Partial withdrawals from the 7th financial year, within limits. After 15 years you can extend in blocks of 5 years.
Suits this kind of situation: Anyone who wants a steady, low-risk bucket, including business owners and homemakers.
NPS (National Pension System)
What it is: A market-linked pension account under PFRDA rules. Your money goes into a mix of equity and debt that you choose. See the NPS Trust website.
Exit rules (updated December 2025): Non-government subscribers can take up to 80% as a lump sum, with at least 20% for an annuity when the corpus is above ₹12 lakh. Smaller corpus sizes have more flexibility. Government employees have a 60% lump sum limit. You can stay invested up to age 85.
Suits this kind of situation: Long-term savers who want forced discipline and a growth bucket.
SCSS (Senior Citizens Savings Scheme)
What it is: A government scheme for people aged 60 and above, with interest paid every quarter.
Rate and limit: 8.2% for October to December 2026, with a ₹30 lakh limit per person. Tenure is 5 years, extendable by 3.
Suits this kind of situation: Retirees who want regular income from a low-risk source.
Annuity
What it is: You give a lump sum to an insurer and the insurer pays you a regular amount, often for life. The payout depends on your age, the option you choose and the insurer. Always ask for a written quote and compare.
Suits this kind of situation: People who value a fixed income they cannot outlive more than flexibility.
Mutual Funds
What they are: Pooled investments in shares, bonds or both. You can invest through a monthly SIP and take money out through an SWP (Systematic Withdrawal Plan) after retirement.
Watch out: Among retirement schemes, mutual funds are the most flexible, but returns are not fixed. If markets fall in the early years of retirement while you are withdrawing, your money can run down faster. Our hybrid SIF vs fixed deposit guide shows how one more option looks next to a bank deposit. We also cover SIP step-up and SIP vs SWP in separate guides.
Retirement Schemes Compared: Lock-in, Risk and Who They Suit
Use this table to see which of these retirement schemes does which job.
| Scheme | Main job | Lock-in and access | Risk | Suits this kind of situation |
|---|---|---|---|---|
| EPF | Safety | Partial withdrawals for set reasons; 25% minimum balance | Low | Salaried employees |
| PPF | Safety | 15 years; partial from year 7 | Low | Anyone wanting a steady safe bucket |
| NPS | Growth with discipline | Locked until exit age; annuity rules apply | Market-linked | Long-term savers |
| SCSS | Income | 5 years, extendable by 3; age 60+ | Low | Retirees needing quarterly income |
| Annuity | Lifelong income | Money handed to the insurer | Low market risk, inflation risk | People who value a fixed income for life |
| Mutual funds | Growth and flexible income | Usually no lock-in (tax-saving funds have 3 years) | Market risk | Long-term investors needing flexibility |
Retirement Schemes: A Worked Example with Numbers
Let us look at ₹10,000 a month for 20 years. You put in ₹24 lakh in total. What it becomes depends on the yearly growth rate. These rates are examples, not promises. None of these retirement schemes is guaranteed to give any of them.
| Example yearly growth | Total invested | Value after 20 years (approx.) |
|---|---|---|
| 6% | ₹24 lakh | ₹46.4 lakh |
| 8% | ₹24 lakh | ₹59.3 lakh |
| 10% | ₹24 lakh | ₹76.6 lakh |
| 12% | ₹24 lakh | ₹99.9 lakh |
Illustrative only. Calculated with monthly investing and monthly compounding. Tax and charges are not included.
Two more numbers to keep in mind:
- Inflation matters. If your monthly expense is ₹50,000 today and prices rise 6% a year, you will need about ₹1.6 lakh a month after 20 years for the same lifestyle.
- SCSS income example. ₹30 lakh at 8.2% pays about ₹2.46 lakh a year, or roughly ₹61,500 a quarter, before tax. The rate for a new deposit depends on the quarter in which you deposit.
Try your own numbers on our calculator. For how much corpus a Surat family may need, read our retirement planning guide for Surat investors and Is ₹2 crore enough to retire.
Retirement Schemes: Which Situation Suits What
These mixes of retirement schemes suit these kinds of situations:
- Salaried people: EPF as the base, with NPS or mutual funds on top for growth.
- Business owners and professionals with no EPF: PPF, NPS and mutual funds, built step by step.
- Retirees: SCSS, annuity and SWP in a mix that matches income needs and tax position.
- Gulf and other NRIs planning a return: rules differ for NRIs, so read our NRI retirement planning guide first.
Be careful with retirement schemes in these situations:
- Putting everything in one scheme because it feels safe or saves tax.
- Buying an annuity or locking money for 15 years without checking your cash needs for the next 5 years.
- Choosing only for tax benefit, especially under the new tax regime where many deductions do not apply.
Families with young children should also plan for education costs alongside retirement. We explain this in Child Education and Retirement Fund: 5 Costly Mistakes to Avoid.
Retirement Schemes Checklist: Six Questions Before You Choose
Use this list before you add any new retirement schemes to your plan.
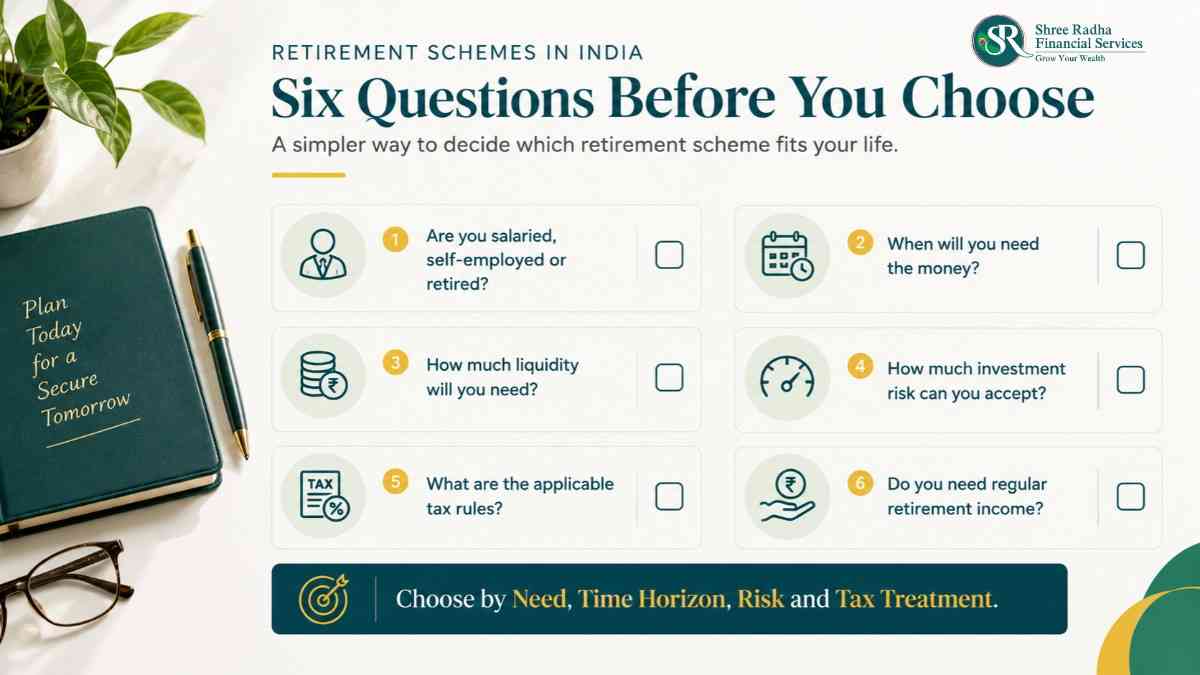
- How many years do I have? A 30-year gap and a 5-year gap need different tools.
- Which bucket is missing? Safety, growth or income. Look at what you already hold.
- When might I need cash? Check the lock-in before you commit.
- Which tax regime am I in, and does my employer contribute? Many deductions apply only to the old regime.
- How much of the final withdrawal is tax-free? Check each scheme, not just the headline.
- Have I written down my monthly need at 60? Include inflation.
Rules and regulations change from time to time. Please connect with your tax consultant / CA for details specific to your situation. Figures in this article were last verified on 26 October 2026.
Retirement Schemes: Frequently Asked Questions
Which is the best of all retirement schemes in India?
There is no single best one. Each scheme does a different job. EPF and PPF give safety, NPS and mutual funds give growth, and SCSS, annuity and SWP give income. The right mix depends on your age, income and needs.
Which retirement schemes are EEE?
PPF is fully EEE, although the deduction on your contribution is available only under the old tax regime. EPF is EEE with conditions. NPS is exempt in the first two stages and only partly exempt at exit. SCSS, annuity and mutual funds are not EEE.
Is EPF interest taxable?
Interest is tax-free on your contribution up to ₹2.5 lakh a year, or ₹5 lakh where there is no employer contribution. Interest on the excess is taxable. Please confirm your case with your tax consultant.
Can I take my full NPS money at 60?
Not always. Under the December 2025 PFRDA rules, non-government subscribers with a corpus above ₹12 lakh can take up to 80% as a lump sum, and at least 20% must buy an annuity. Government employees can take up to 60%. Under current tax law only 60% is tax-free, so confirm the tax position with your CA.
What is the SCSS limit and who can invest?
The limit is ₹30 lakh per person. You generally must be 60 or above. Interest is paid quarterly and is taxable.
Is PPF useful if I am in the new tax regime?
PPF interest and maturity are tax-free either way. The deduction on the amount you invest is available only under the old regime.
Can a business owner or self-employed person get EPF?
EPF is linked to employment, so most business owners do not have it. Among retirement schemes, they usually look at PPF, NPS and mutual funds instead.
This article is also available on Medium for wider reading: https://medium.com/@shreeradha.services/retirement-schemes-in-india-which-one-does-what-epf-ppf-nps-scss-and-more-951cf1b73f27
Want to See How Your Retirement Schemes Fit Together?
Connect with Shree Radha Financial Services for a personalized discussion.
📞 Call/WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services, Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN05763
Investing since 2012 | BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN05763). All content is strictly for educational purposes only and does not constitute individualized investment advice. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing. Tax treatment is based on current laws and subject to change. Please consult a qualified tax professional before investing. The characters in this article (Hitesh, Neha, Rohan, Dilipbhai and Kokila) are fictional and used only to explain situations. Numbers in the worked example are illustrative and are not a promise of returns.