Gifting Shares to Family: Four Stories, Four Surprises
Gifting shares to family feels like the simplest thing in the world. You love someone, you hold shares, you move them across. Where is the tax?
The tax is in three places that people forget: the cost the receiver will use later, the income the shares keep earning, and who the receiver is in the eyes of the law.
Four families, four cities, four surprises. Read the stories first. The rules and tables come after.
Note: The families and numbers in these stories are illustrative, to explain the rules. They are not real clients. We keep prices constant to make the sums simple.
“Gifting shares to family is a good thing to plan. But plan it with the tax in front of you. The surprise is almost never at the time of the gift. It comes later, when someone sells.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
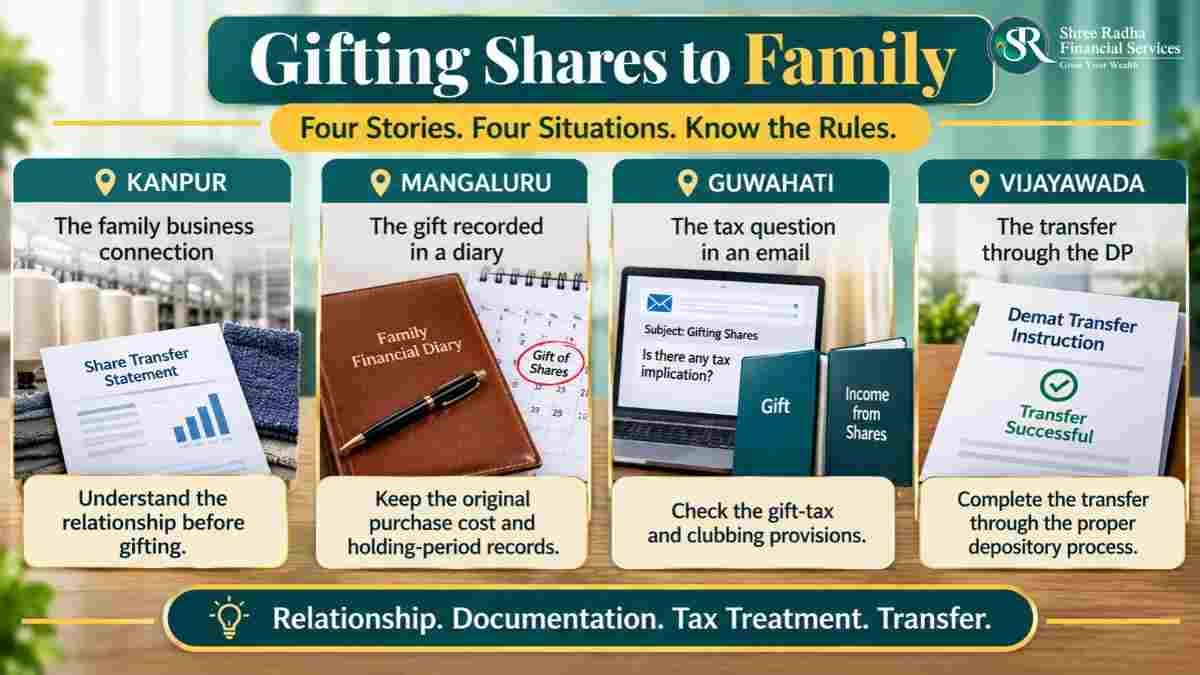
Story 1: Kanpur, a Chat Across the Mill Office Counter
Pankaj Seth, 58, owns a textile mill in Kanpur. His daughter Ananya was getting married in the spring. He wanted to give her something that would last. In 2020 he had bought shares for Rs 20 lakh. Today they were worth Rs 1.2 crore.
His CA, Mr. Dwivedi, had dropped by the mill office. Pankaj leaned on the counter.
“If I gift these shares to Ananya, I pay no tax, right?”
“Right,” said Mr. Dwivedi. “A gift is not a sale. You pay no capital gains tax.”
“And she pays nothing for receiving it?”
“Not from her father. A parent is a relative. No tax on receipt.”
Pankaj smiled. It seemed done. Eight months later, Ananya decided to sell the shares to buy a flat. She called her father, happy and relaxed. “Papa, the shares were worth Rs 1.2 crore when you gave them. So I have no gain, no tax.”
Pankaj frowned and phoned Mr. Dwivedi. The CA was kind but clear. “Ananya’s cost is your cost, Rs 20 lakh, not Rs 1.2 crore. Her gain is Rs 1 crore. The good news: your five years of holding count as hers, so it is a long-term gain.”
The tax came to about Rs 12.84 lakh before any surcharge. At this size, surcharge is likely to apply as well, so the number needs a CA.
Ananya went quiet on the phone. Then she said, “Papa, I am glad we asked before the flat money was spent.”
What to remember: a gift does not reset the cost. The receiver uses the giver’s cost and the giver’s holding period.
Useful to know about gifting shares to family:
- The giver pays no capital gains tax on a gift (Section 70(1)(b)).
- If the shares were bought before 1 February 2018, an extra cost rule in Section 90(7) may apply. Ask your CA.
- Keep the giver’s purchase records. The receiver will need them when selling.
The same gifting shares to family calculation in formula form:
| Step | Formula | Numbers | Result |
|---|---|---|---|
| 1. Gain on sale | Sale value − father’s cost | 1,20,00,000 − 20,00,000 | Rs 1,00,00,000 |
| 2. Gain that is taxed | Gain − Rs 1,25,000 | 1,00,00,000 − 1,25,000 | Rs 98,75,000 |
| 3. Tax at 12.5% | Taxed gain × 12.5% | 98,75,000 × 12.5% | Rs 12,34,375 |
| 4. Cess at 4% | Tax × 4% | 12,34,375 × 4% | Rs 49,375 |
| 5. Total tax (before any surcharge) | Tax + cess | 12,34,375 + 49,375 | Rs 12,83,750 |
| Gain if cost had “reset” (wrong idea) | Sale value − gift-day value | 1,20,00,000 − 1,20,00,000 | Rs 0 (not correct) |
Story 2: Mangaluru, a Diary Page
Dr. Sunita Prabhu, 44, is a gynaecologist in Mangaluru. Her husband Devdas, 48, looks after their home and the family’s small coconut farm. He has almost no income of his own. This is a page from her diary.
Tuesday, late night. Gifting shares to family felt smart. I gifted shares worth Rs 1 crore to Devdas today. He has no income, so the dividends will be taxed lightly in his name. Smart. I should have done this years ago.
Friday. Told our CA about it. He listened, then said one sentence: “Sunita, the dividends will be added to your income, not Devdas’s.”
Friday, later. I asked how. He opened the Act. When a person gives an asset to a spouse without payment, the income from that asset is added to the giver’s income. The gift itself is exempt, since a spouse is a relative. But the dividend, about Rs 3 lakh a year, comes back to me.
Saturday. I worked it out. At my 30% slab, Rs 3 lakh of dividend means Rs 90,000 of tax, and Rs 93,600 with cess. Surcharge may add to this. I felt foolish for a minute, and then relieved that I had asked in the first week, not the first year.
Sunday. The CA also said he is not sure how capital gains on these shares will be treated if Devdas sells them. “Let us check before he sells,” he said. Good idea.
What to remember: after gifting shares to a spouse, the income from them is still taxed with the giver.
Useful to know about gifting shares to family:
- Section 99 also covers a son’s wife and a minor child.
- The gift to a spouse is exempt. Only the income from it is added to the giver.
- Whether capital gains on gifted shares are also added is a point to confirm with your CA.
The same calculation in formula form:
| Step | Formula | Numbers | Result |
|---|---|---|---|
| 1. Dividend from gifted shares | Value × dividend rate | 1,00,00,000 × 3% | Rs 3,00,000 |
| 2. Whose income it is | Added to the giver’s income | Section 99(1)(a)(ii) | Dr. Sunita’s |
| 3. Tax if taxed at 30% | Dividend × 30% | 3,00,000 × 30% | Rs 90,000 |
| 4. Cess at 4% | Tax × 4% | 90,000 × 4% | Rs 3,600 |
| 5. Total tax (before any surcharge) | Tax + cess | 90,000 + 3,600 | Rs 93,600 |
Story 3: Guwahati, an Email
Biren Bora, 39, runs a small tea-packaging unit in Guwahati. His first cousin, Rohit, lives in Dubai and is doing well. One evening Rohit transferred listed shares to Biren’s demat account to help him expand the unit. Biren was moved. Then he wrote this email to his CA.
From: Biren Bora
To: CA Mahanta
Subject: My cousin gifted me shares, any tax?
Dear Sir, my first cousin Rohit has gifted me shares worth about Rs 80 lakh. He is family, so it should be tax-free like a gift from my father. Please confirm.
From: CA Mahanta
To: Biren Bora
Subject: Re: My cousin gifted me shares, any tax?
Dear Biren, I wish I could say yes. But the law does not use the word “family”. It uses a fixed list of relatives. A first cousin is not on that list. Gifts from non-relatives are taxed if the total in the year is more than Rs 50,000. And then the whole value is taxed, not just the part above Rs 50,000. Here, the whole Rs 80 lakh is added to your income for the year. Had the gift come from your uncle, your father’s or mother’s brother, it would have been exempt. Please do not do anything with the shares until we speak.
Biren read the reply twice. He called Rohit that night. “I am glad you did not send more,” he said, laughing. But he also asked a good question: “Is it still fine to accept the gift?” The CA’s answer was simple. “Yes. But gifting shares to family who are not on the list needs a plan for the tax, before the shares are sold.”
What to remember: the law has a fixed list of relatives. A cousin is not on it, so the whole gift can be taxed once it crosses Rs 50,000.
Useful to know about gifting shares to family:
- Direction matters. An uncle or aunt is a relative of the nephew or niece. A nephew or niece is not a relative of the uncle or aunt.
- Section 92(2)(m) taxes the whole value, not only the excess, once gifts from non-relatives in the year cross Rs 50,000.
- The value of listed shares for this rule is set by the Rules. Ask your CA how it is worked out.
The same calculation in formula form:
| Step | Formula | Numbers | Result |
|---|---|---|---|
| 1. Value of the shares on the gift date | Market value as per the Rules | Cousin’s gift of listed shares | Rs 80,00,000 |
| 2. Is the total from non-relatives above Rs 50,000? | Compare with Rs 50,000 | 80,00,000 > 50,000 | Yes |
| 3. Amount added to Biren’s income | The whole value, not just the excess | Whole Rs 80,00,000 | Rs 80,00,000 |
| 4. Tax on it | Slab rates on his total income | Ask your CA; surcharge may apply at this size | — |
| For comparison: same gift from an uncle | Gift from a relative | Exempt (Section 92(3)) | Rs 0 |
Story 4: Vijayawada, Five Steps at the DP Office
Rao, 47, lives in Vijayawada. His mother, Lakshmi, 72, wanted to buy a flat in her own name near the temple. She had no savings except what Rao could help with. Rao held shares that he had bought for Rs 15 lakh, now worth Rs 75 lakh. He decided to move them to his mother, and went to his DP office with her.
Step 1. The clerk asked, “Does your mother have a demat account?” She did, opened last week with full KYC.
Step 2. “Then it is an off-market transfer,” said the clerk. “Mark it as a gift.” Rao asked about charges, and the clerk quoted the DP’s fee. Rao noted it down and asked his CA about stamp duty.
Step 3. They both signed a short gift letter. Rao’s CA had asked them to keep it for the record.
Step 4. The shares moved. Lakshmi later sold them to fund the flat. The gain was Rs 60 lakh, using her son’s cost of Rs 15 lakh. After the Rs 1,25,000 limit, her tax came to about Rs 7.64 lakh before surcharge.
Step 5. Rao’s CA reminded them of two things. First, tax follows the person who sells. Second, the law has anti-avoidance rules, so any gift made mainly to reduce tax should be looked at by a CA before it is made.
For gifting shares to family, the reason matters as much as the numbers. Rao said, “We did it for the flat, not for the tax.” The CA smiled. “Good. Then keep the reason in writing.”
What to remember: tax follows the person who sells, and the cost is the giver’s cost.
Useful to know about gifting shares to family:
- Section 99 does not add a parent’s or an adult child’s income to yours. But a CA should look at the whole arrangement.
- Each person has their own Rs 1,25,000 yearly limit on long-term gains from equity shares.
- Mutual fund investments are subject to market risks. Read all scheme-related documents carefully.
The same gifting shares to family calculation in formula form:
| Step | Formula | Numbers | Result |
|---|---|---|---|
| 1. Gain when the mother sells | Sale value − son’s cost | 75,00,000 − 15,00,000 | Rs 60,00,000 |
| 2. Gain that is taxed | Gain − Rs 1,25,000 | 60,00,000 − 1,25,000 | Rs 58,75,000 |
| 3. Tax at 12.5% | Taxed gain × 12.5% | 58,75,000 × 12.5% | Rs 7,34,375 |
| 4. Cess at 4% | Tax × 4% | 7,34,375 × 4% | Rs 29,375 |
| 5. Total tax (before any surcharge) | Tax + cess | 7,34,375 + 29,375 | Rs 7,63,750 |
How Gifting Shares to Family Is Taxed: Giver and Receiver
The tax depends on who the receiver is. Here is the position under the Income-tax Act 2025 (Tax Year 2026-27).
| Gift given to | Receiver’s tax on the gift | Income from the gifted shares | Giver’s capital gains tax |
|---|---|---|---|
| Spouse | Exempt (Section 92(3)) | Added to giver’s income (Section 99(1)(a)(ii)) | None (Section 70(1)(b)) |
| Son’s wife | Exempt | Added to giver’s income (Section 99(1)(b)) | None |
| Adult son or daughter, parent | Exempt | Taxed in their own hands; Section 99 does not add it. A CA should check the arrangement | None |
| Minor child | Exempt | Added to the parent with the higher income, after Rs 1,500 per child (Section 99(1)(c)) | None |
| Cousin, friend, neighbour, or a nephew or niece giving to an uncle or aunt | Whole value taxed if gifts in the year exceed Rs 50,000 (Section 92(2)(m)) | Taxed in the receiver’s hands | None |
Seen from the receiver, an uncle or aunt (brother or sister of either parent) is a relative. A nephew, niece, cousin or friend is not. The list is in Section 92(5)(g). Our income from other sources guide explains the Rs 50,000 rule, and our clubbing of income guide covers Section 99.
Rules and rates change from time to time. Please confirm with your tax consultant / CA.
Cost and Holding Period After Gifting Shares to Family
This is where most families doing gifting shares to family get surprised, as Pankaj and Ananya did.
| Point | Rule | Section |
|---|---|---|
| Cost of the shares for the receiver | The cost the giver paid, not the value on the gift day | 73 (Table Sl. 1) |
| Holding period for the receiver | The giver’s holding period is counted too | 2(101) |
| Shares bought before 1 February 2018 | An extra cost rule using the 31 January 2018 value may apply. Ask your CA | 90(7) |
| Long-term gain on listed equity shares | 12.5% on gains above Rs 1,25,000 in the year, if STT is paid | 198 |
| Short-term gain on listed equity shares | 20%, if STT is paid | 196 |
For gains and rates on mutual funds and shares, see our mutual fund taxation guide. For how SWP payouts are taxed, read our SWP taxation guide.
How to Do Gifting Shares to Family: The Steps
Here is the usual path. Details differ by DP and fund house, so please ask them directly.
| Step | What to do |
|---|---|
| 1. Demat accounts | Both giver and receiver need KYC-complete demat accounts for shares and for units held in demat |
| 2. Off-market transfer | Ask your DP to move the shares by an off-market transfer and mark it as a gift. Ask the DP about charges and any stamp duty |
| 3. Gift letter or deed | Keep a signed gift letter for the record. For large gifts, ask a lawyer about a gift deed |
| 4. Units held in a folio | Ask the fund house or its registrar whether and how units can be transferred. Locked-in or pledged units may not move |
| 5. Records | Keep demat statements and the consolidated account statement. The transfer may appear in your AIS |
For property gifts and the paperwork around them, see our gift deed guide. For what happens to holdings after death, read our nominee vs legal heir guide. If your gift is for a minor, our guardian for minor mutual fund account guide explains the folio rules.
Five Points to Remember About Gifting Shares to Family
- The giver pays no capital gains tax on a gift.
- The receiver uses the giver’s cost and the giver’s holding period.
- Income from gifted shares stays with the giver when the receiver is a spouse, a son’s wife or a minor child.
- A gift from a non-relative, above Rs 50,000 in the year, is taxed in full in the receiver’s hands.
- Tax follows the person who sells. Ask your CA before any gift whose main reason is tax.
Check Before You Gift: Five Questions
- Who is the receiver, and is that person on the relative list?
- What was the giver’s cost and purchase date for these shares?
- Will the receiver sell soon? If yes, what will the tax be on the giver’s cost?
- Does the income from the shares come back to me under Section 99?
- Have I written down the reason for the gift?
Gifting shares to family works best when these answers are clear before the transfer. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully.
| Subject | 1961 Act | 2025 Act |
|---|---|---|
| Gift is not a transfer for capital gains | Section 47(iii) | Section 70(1)(b) |
| Cost of an asset received by gift | Section 49(1) | Section 73 |
| Holding period includes the giver’s | Section 2(42A) | Section 2(101) |
| Gift received: tax and exemptions | Section 56(2)(x) | Sections 92(2)(m), 92(3) |
| Definition of relative | Explanation to Section 56(2) | Section 92(5)(g) |
| Clubbing of income | Section 64 | Section 99 |
| Cost rule for shares bought before 1 February 2018 | Section 55(2)(ac) | Section 90(7) |
Official Sources to Read
- Income Tax Department: the Income-tax Act page, Sections 70, 73, 90, 92 and 99.
- e-Filing portal: incometax.gov.in for your AIS and return forms.
- AMFI: amfiindia.com for mutual fund scheme information.
- SEBI: sebi.gov.in for rules on demat accounts and securities.
The Act text on gifting shares to family sits mainly in Sections 70, 73, 92 and 99. Read these with our estate planning guide and family settlement agreement guide.
How SR Wealth Can Help
Shree Radha Financial Services is an AMFI Registered Mutual Fund and SIF Distributor and an APMI Registered PMS Distributor. We are not tax consultants. What we do:
- Explain the products you hold, and the steps for gifting shares to family, in simple language
- Help you collect purchase records and statements, so your CA can work out the cost and gain
- Connect you with a competent CA or tax consultant if you need one for your salary tax, return or notice
Gifting Shares to Family: Frequently Asked Questions
1. Do I pay tax when I gift shares to my family?
No. A gift by an individual is not treated as a transfer for capital gains (Section 70(1)(b)). The giver pays no capital gains tax.
2. Does the receiver pay tax on gifted shares?
Not if the giver is a relative (Section 92(3)). If the giver is not a relative and the total in the year is above Rs 50,000, the whole value is taxed.
3. What is the cost when the receiver sells gifted shares?
The cost the giver paid (Section 73). It does not reset to the value on the gift day.
4. How is the holding period of gifted shares counted?
The giver’s holding period is added to the receiver’s (Section 2(101)). Gifting shares to family can therefore lead to a long-term gain on the first day of sale.
5. Is the income from shares gifted to a spouse added to my income?
Yes. Income from assets given to a spouse without payment is added to the giver’s income (Section 99(1)(a)(ii)). Whether capital gains are also added is a point to confirm with your CA.
6. What about gifting shares to a minor child?
The child’s income is added to the parent with the higher income, after Rs 1,500 per child (Section 99(1)(c) and Schedule III).
7. Is a gift from a cousin taxable?
Yes, if gifts from non-relatives in the year are above Rs 50,000. A cousin is not on the list of relatives.
8. Can mutual fund units be gifted?
Units held in demat can move by off-market transfer. For units in a folio, ask the fund house or its registrar. Units in lock-in or pledged units may not move.
9. Is there stamp duty on gifting shares?
Please ask your DP and your CA about charges and any stamp duty before you transfer.
10. Do the 31 January 2018 rules apply to gifted shares?
They may apply to shares bought before 1 February 2018 (Section 90(7)). Please confirm with your CA how it works with a gift.
This article is also available on Medium for wider reading:https://medium.com/@shreeradha.services/a-gift-of-shares-is-tax-free-the-surprise-comes-when-someone-sells-cf5eb624f135
Planning Your Family’s Investments?
If you want to talk about mutual funds, SIP, SIF or planning the transfer of investments within your family, connect with Shree Radha Financial Services for a personalized discussion.
📞 Call/WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services, Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN05763
IRDAI Licensed Insurance Distributor
Investing since 2012 | BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN05763). All content is strictly for educational purposes only and does not constitute individualized investment, legal or tax advice. The characters in this article are fictional. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing. Rules and rates change from time to time. Please confirm with your tax consultant / CA. Tax treatment is based on current laws and subject to change.