How to Invest When Market Is Down or Sideways — Why Most People Only Know How to Act in a Bull Run
Almost everyone knows what to do when markets are climbing: stay invested, maybe add more, feel good about the statements. Almost nobody has a plan for the other two-thirds of a market cycle — the correction, and the long, directionless stretch in between where nothing seems to be happening at all.
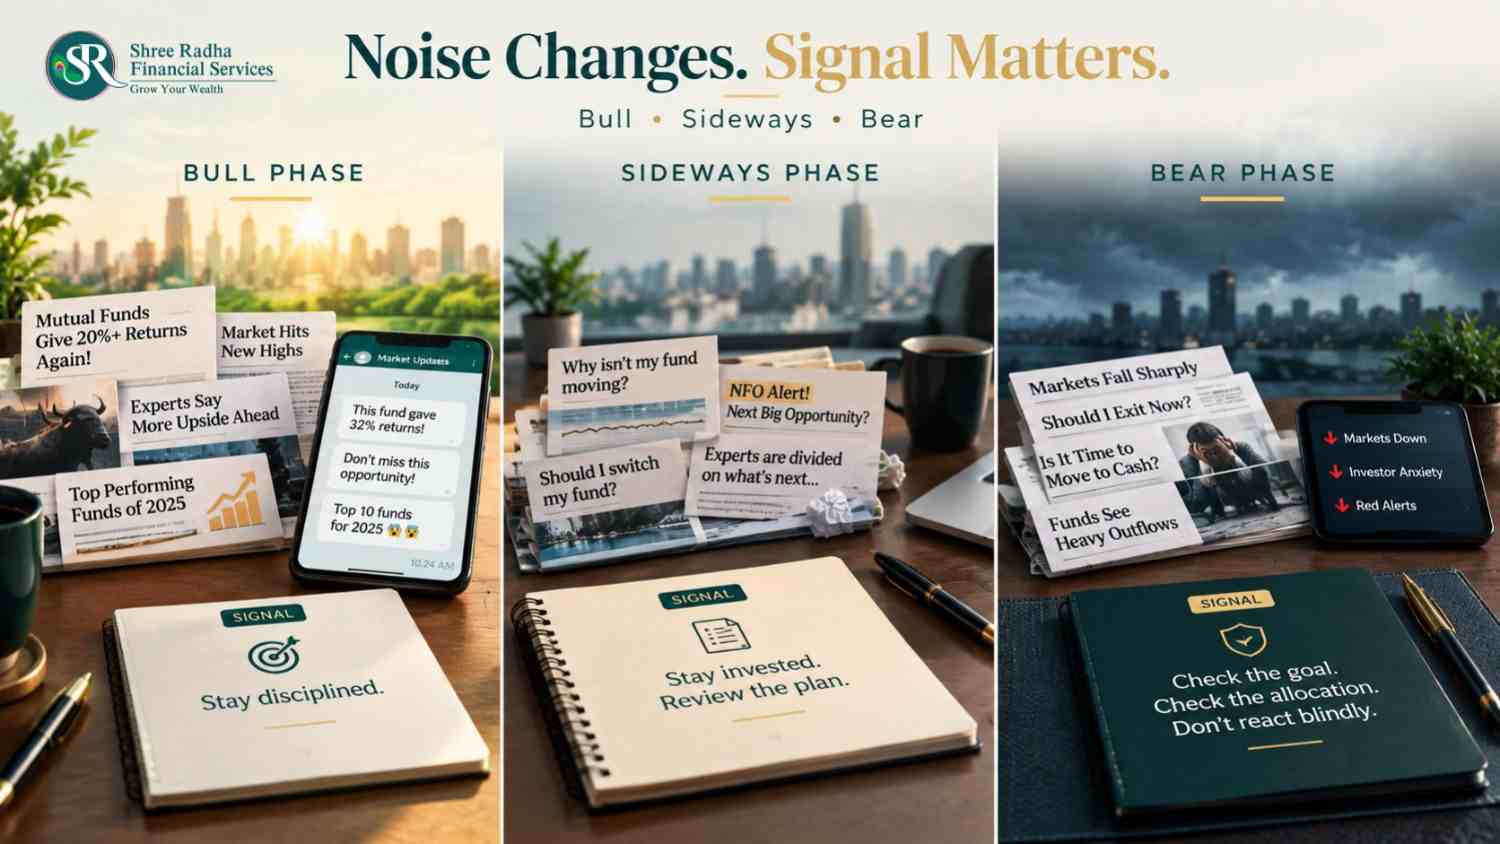
Into that gap walks the news. A falling market comes wrapped in headlines built to alarm you; a flat market comes wrapped in boredom and a fresh “opportunity” pitch. Neither is actually telling you how to invest when market is down or standing still — both are just noise, and most investors end up reacting to the noise because nobody ever showed them what the signal actually looks like.
Here’s the difference, phase by phase:
| Market phase | What the noise sounds like | What actually matters |
|---|---|---|
| Bull market | “Fresh record high,” NFO ads everywhere, every relative asking which stock to buy | Whether your equity allocation has drifted above your actual target |
| Down market / correction | “Worst day in years,” VIX spiking, forwards predicting further crashes | Whether your goal and timeline have changed — the day’s headline hasn’t changed either |
| Sideways / range-bound market | “Market going nowhere,” a shiny new NFO pitch, your fund’s 1-year return looking flat | Whether you’re still on track for your goal — this quarter’s flat return isn’t the measure |
Four people, in four cities, ran into one phase each of this cycle. None of them made a “wrong” investment — they made the right kind of decision at the wrong kind of moment, because they were reading the noise instead of the signal. You’ve likely lived through at least one of these four moments yourself — the only question is whether you caught it in time, or found out later, the way they did.
Ahmedabad — Nikunj Bhai’s ₹15 Lakh, Invested at the Exact Peak of the Noise
Nikunj Bhai, 41, runs a plastics and chemical trading business out of Ahmedabad’s Naroda industrial estate. His phone had been buzzing all week with the same story from three different directions — a cousin’s college friend showing off a defence stock screenshot, a supplier mentioning it twice at a routine meeting, an ad for a brand-new fund promising to ride the same wave at ₹10 a unit. Defence and PSU stocks had rallied as much as 385% between October 2022 and November 2023, and by the third mention that week, the ₹15,00,000 sitting untouched in his business account had stopped feeling like savings and started feeling like a missed opportunity.
He invested the full amount that same week, into the newest fund he could find in the space. For a few weeks it felt like validation — the fund’s name kept coming up in the same conversations, and he’d nod along, quietly pleased he’d finally acted instead of just listening.
Then the NAV started sliding. First below ₹9.50, then closer to ₹9. He told himself it was temporary — sectors correct, then they recover — and stopped bringing it up at those same supplier meetings. What he didn’t stop doing was opening the app late at night, doing the mental math on how much of the ₹15 lakh had already evaporated on paper.
It was on a routine review call — one he’d almost postponed — that he finally said it out loud, half-defensive, half-hoping to be told it would bounce back. Instead of a verdict on the fund, the question that came back was simpler: when exactly had this fund launched, relative to when the rally itself had started?
Nikunj Bhai didn’t need to look it up. He already knew — the Nifty India Defence Index had peaked in July 2024 after more than doubling in the previous nine months, and his fund had launched into the market in that very same window, alongside four others chasing the identical story. Saying the dates out loud was the moment the pattern became obvious to him: he hadn’t picked a bad fund. He’d bought in at the loudest possible point of a story that had already been running for the better part of a year.
Business owners sitting on surplus cash after a strong year face this same pull often — our Investment Guide for Gujarat Business Owners covers how to put idle cash to work without it becoming a bet on whatever story is loudest that quarter.
Before and After — Nikunj Bhai’s ₹15,00,000
| Before | After |
|---|---|
| Full amount into a brand-new sector NFO, chosen because it was the loudest story in the market at the time | Redirected toward a diversified fund matched to his actual goal, with any future sector exposure capped as a small, deliberate satellite position — never the whole decision |
“Everyone around me was talking about the same stocks,” Nikunj Bhai says. “I didn’t stop to ask why a brand-new fund was being launched right when the rally was already old news.”
Pune — Sameer’s Bonus, Frozen by Noise for Eight Months
Sameer, 36, works at an auto component manufacturer near Pune’s Chakan belt. He had a ₹6,00,000 bonus ready to invest right as markets turned sharply lower — the kind of stretch where the Nifty 50 dropped over 5% in a single week and India VIX jumped past 40%. Every evening for the next eight months, he did the same thing: opened a news app, scanned for some sign the worst was over, and closed it again without doing anything.
The factory canteen didn’t help. A colleague forwarded a message about the rupee one week, another shared a chart with red arrows the next, his father-in-law called twice to ask if his own retirement money was safe. Each conversation left Sameer more convinced this wasn’t the week to invest — there’d surely be a clearer week coming.
What finally moved him wasn’t a headline calming down — headlines rarely fully do. It was noticing, almost by accident, that a colleague who’d invested his own bonus straight through the worst of the fall — without waiting for anything to feel safe — was now sitting on a gain Sameer hadn’t come close to matching with ₹6 lakh still parked in a savings account earning almost nothing.
When he finally brought this up on a call with the SR Wealth team, half-embarrassed to admit he’d been sitting on the money that long, the question that came back wasn’t about where the market would go next — it was about his own eight months. What, specifically, would have had to happen — which headline, which number — for him to have finally felt ready?
Sameer sat with that question and didn’t have an answer. There wasn’t a signal that was ever going to arrive clean enough to satisfy the waiting. This is exactly the well-documented pattern behind why so many people get it wrong when they try to invest when market is down: investors who exited during the 2008 crash and waited for a clearer signal to re-enter often found the market 40% higher within roughly 24 months — the recovery, once it starts, almost never announces itself clearly enough to be worth waiting for.
Sameer didn’t invest the full ₹6 lakh on that call. What changed was smaller than that, and easier to actually do: a portion went in that same week, and the rest was set on a fixed schedule to follow over the coming months — taken out of his hands entirely, so no future headline would get another vote on the decision. That, in the end, is the entire answer to how to invest when market is down: not a better prediction, just a plan that doesn’t need one.
Before and After — Sameer’s ₹6,00,000
| Before | After |
|---|---|
| 8 months in cash, waiting for the news to “clear up” before investing anything | A tranched deployment — a portion invested straightaway, the rest staggered in over the following months on a fixed schedule, regardless of that week’s headlines |
“I kept telling myself I’d invest once things looked clearer,” Sameer says. “They never look clear enough in the moment — I understand that now.”
Vadodara — Ritu’s SIP, Switched Right Before It Would Have Paid Off
Ritu, 34, works at a pharmaceutical company in Vadodara and has been running a SIP toward her daughter’s future for six years. For almost two years, her monthly statement told the same story: the number barely moved — a genuinely range-bound stretch, not unlike the real 2015-2016 period, when the Nifty 50 fell roughly 4% one year and rose barely 3% the next. She’d open the statement out of habit, feel a small flicker of disappointment, and close it again.
Then, one month, her distributor’s app pushed a notification about a brand-new fund — ₹10 a unit, built around a story that sounded far more exciting than “still flat.” She switched that same afternoon, relieved to finally be doing something instead of just watching a number sit still. For a while, it felt like she’d fixed something.
The sting came almost a year later, in the middle of an unrelated conversation — a colleague mentioned, in passing, that her own fund in that same category had quietly climbed out of its two-year rut. Ritu went home and checked her old fund’s numbers, half out of curiosity, half already knowing what she’d find. It hadn’t failed her. It had just been waiting out the same flat stretch as everything else in its category — and she’d walked away from it right before that stretch ended.
On her next call with SR Wealth, she didn’t ask which fund to buy next. She asked something closer to the real question: how was she supposed to have known the fund itself wasn’t the problem?
The answer came back as a question of her own, turned around — had her old fund actually underperformed its category and benchmark, or had the entire market just gone quiet for a while? Knowing how to invest when market is down is one skill; recognising when it’s simply gone flat, and doing nothing, turned out to be the harder one. She realized, sitting with that, that she’d only ever checked her own statement. She’d never once checked whether everyone else’s statement looked the same that year. It hadn’t been a genuinely bad fund — it had been the market pausing, the same pause every fund in that category was living through together.
Before and After — Ritu’s SIP
| Before | After |
|---|---|
| Switched out of a flat-performing fund into a freshly launched one, right before her original category broke out of its range | Going forward, holding through range-bound stretches and reviewing on a fixed schedule (e.g. annually) instead of reacting to a quiet quarter |
“The new fund’s pitch made my existing one look like it had failed,” Ritu says. “It hadn’t — the whole market had just gone quiet for a while.”
Surat — Dr. Falguni’s Rule That Made All Three Phases Simple
Dr. Falguni, 39, runs her own physiotherapy clinic in Surat. She’ll tell you she felt every bit of what Nikunj Bhai, Sameer and Ritu felt — she’s not immune to any of it. When the correction hit and her portfolio sat in red for weeks, there were nights she opened the app more than once before bed, the same way anyone would. When the market later ran hot and half her patients seemed to be talking about some fund that had doubled, she felt the same itch to chase it that pulled Nikunj Bhai in.
What kept her from acting on either feeling wasn’t willpower. It was a number she’d agreed to years earlier with SR Wealth and had mostly forgotten about until the day it mattered: 70% equity, 30% debt, with a standing instruction to only ever act if that ratio drifted more than about 5% in either direction.
When the correction pulled her equity share down to 63%, it wasn’t a headline or a hunch that told her to move money from debt into equity — it was that number, quietly saying she’d drifted. When a later rally pushed the same ratio past 76%, the number spoke again, and she trimmed equity back toward target instead of letting the rally decide for her. This is really the whole answer to how to invest when market is down or running hot — not a sharper instinct, just a number that doesn’t care what the market is doing that week.
She still feels the pulls, every time. She just stopped letting them be the ones who make the call. If you’ve never actually checked whether your own portfolio has drifted this far from where you meant it to be, our Portfolio Review guide walks through exactly how to check.
How to Invest When Market Is Down or Sideways — What to Actually Do in Each Phase
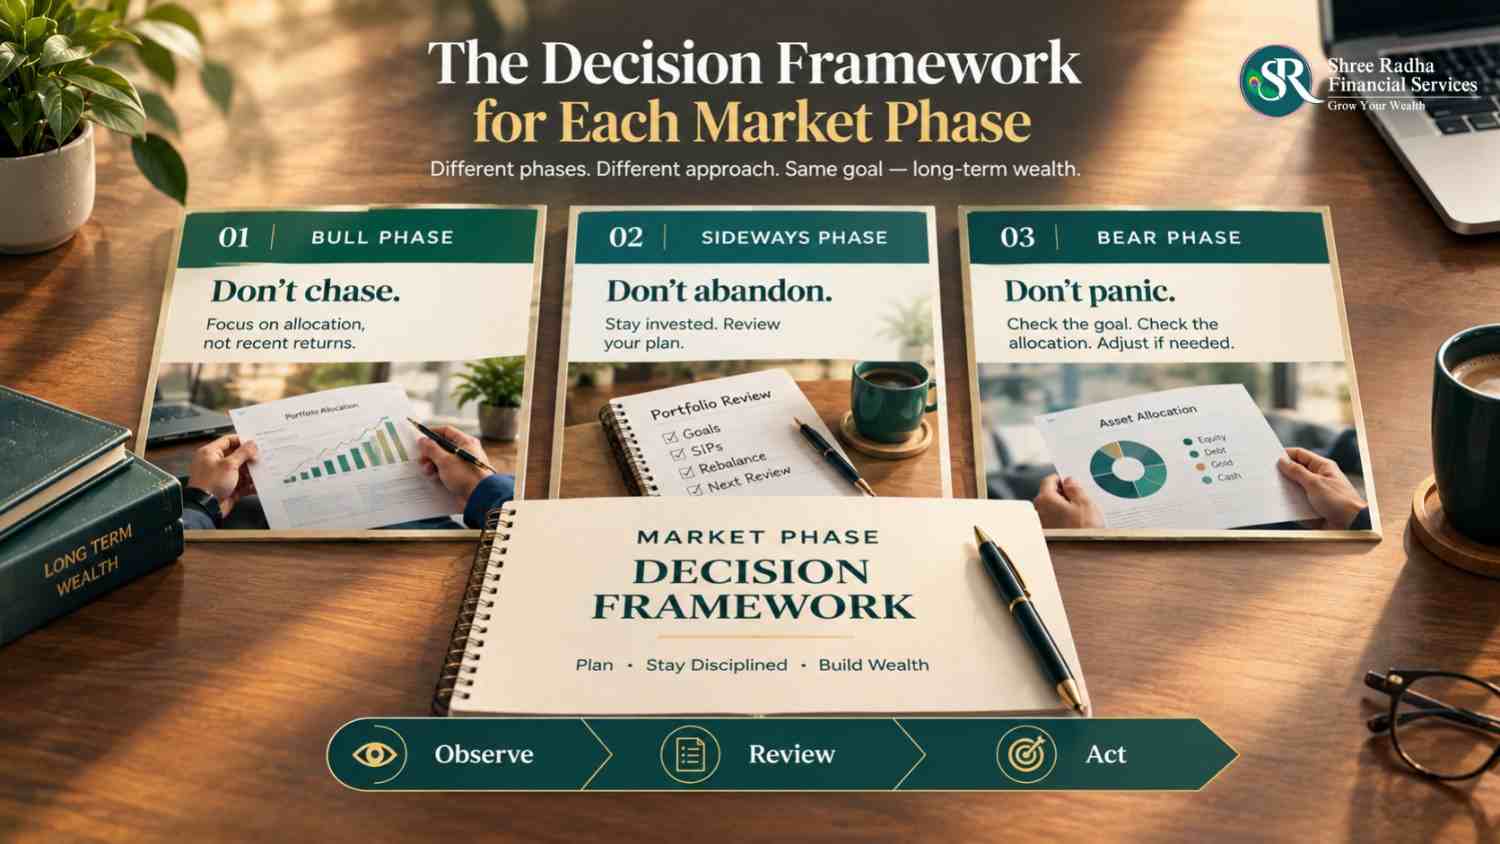
Strip away the headlines and the answer to how to invest when market is down, running hot, or going nowhere comes down to the same three moves, one per phase:
| Phase | What to actually do |
|---|---|
| Bull market | Check your allocation against your target — trim overweight equity back to plan rather than adding more; be extra skeptical of any brand-new NFO in whatever sector is dominating the headlines |
| Down market / correction | Keep existing SIPs running without pause; deploy any lump sum in tranches over weeks or months rather than waiting for an all-clear that never comes clearly; rebalance from debt into equity if your allocation has drifted more than roughly 5% below target |
| Sideways / range-bound market | Keep SIPs running — this is exactly where steady unit-buying within a range does its quiet work; resist fund-switching urges and new NFO pitches; use the calm to review goals, nominees, and paperwork instead of your fund choices |
Quick checklist before you react to any market headline: whether you’re trying to invest when market is down, sitting through a flat stretch, or tempted by a rally, these five checks come first.
- Ask whether your goal or timeline has actually changed — not whether the headline is dramatic
- Check your current equity:debt allocation against your target before deciding to act at all
- If deploying a lump sum during a fall, split it into tranches rather than picking one “perfect” entry point
- If a fund’s return looks flat, check whether the whole market is flat too — before assuming the fund has failed
- Treat any brand-new NFO in a headline-dominating theme with extra scrutiny, not extra excitement
FAQs: How to Invest When Market Is Down or Sideways
Should I stop my SIP when the market is falling?
No — this is the single most well-documented mistake in Indian retail investing, and it’s covered in depth in our guide to SIP, STP, SWP and Switch. A falling market means your fixed SIP amount buys more units at a lower price; stopping breaks exactly the mechanism that makes a SIP work.
How do I invest a lump sum when the market is down, without trying to time the bottom?
Split it. A common approach to how to invest when market is down is investing a meaningful portion immediately and staggering the rest into the market over the following weeks or months via a systematic transfer, regardless of what happens in between — removing the need to correctly guess when the fall has ended.
My fund’s return has been flat for a year — does that mean it’s a bad fund?
Not necessarily. Check whether its entire category and benchmark have also been flat over the same period. A genuinely sideways market can hold an otherwise good fund’s return flat for a year or two before a breakout — switching funds at that point often means leaving right before the flat period ends.
Why do so many new mutual funds (NFOs) launch when the market is going nowhere?
Existing funds showing flat trailing returns are a harder sell, so a new, story-driven fund becomes the easier pitch — priced at ₹10, it creates a sense of a fresh start. That doesn’t make the new fund wrong, but the timing of the pitch says more about distribution pressure than about the fund’s merit.
How do I know when to rebalance my portfolio?
A common, news-blind rule: rebalance when your actual equity allocation drifts more than roughly 5% away from your target mix, in either direction — buying more equity when a fall has pulled the ratio down, and trimming equity when a rally has pushed it up.
Is it ever right to invest more during a market correction?
Yes, if your goal and timeline haven’t changed and the money isn’t needed soon — a correction lowers the entry price for the same long-term goal. If you’re wondering how to invest when market is down without overcommitting, the risk isn’t investing during a fall; it’s investing more than your allocation and timeline can support, or investing based on a prediction of exactly where the bottom is.
“Every client conversation during a falling or flat market starts the same way — with whatever headline or forward they saw that morning. My job in that conversation is almost never about the headline. It’s asking one question: has anything about your actual goal changed? Almost always, the answer is no — which means the right action was already decided long before the headline showed up.” — Paresh Chaudhary, Founder, SR Wealth
Why Ignoring the Noise Is Harder Alone Than It Sounds
Every mistake above looks avoidable in hindsight — Nikunj Bhai should’ve been more skeptical of a brand-new NFO at the loudest point of a rally, Sameer should’ve split his lump sum instead of waiting for certainty, Ritu should’ve recognised a flat market rather than a flat fund. In the moment, with a headline in front of you and money on the line, knowing how to invest when market is down never feels as obvious as it looks afterward.
This is specifically where a distributor’s role earns its place — not in predicting the next headline, but in applying the same rules regardless of what that headline says: checking allocation drift instead of reacting to a rally, staggering a lump sum instead of waiting for a perfect entry, and recognising a sideways market for what it is before a fund gets switched for the wrong reason. At SR Wealth, that check happens the same way whether the market’s headline that week is euphoric, alarming, or boring — because the rule was never supposed to depend on the headline in the first place.
Trying to work out how to invest when market is down, or not sure whether your portfolio has drifted from your actual plan? A quick review can tell you within an hour whether the noise around you should change anything at all — reach out to SR Wealth:
📞 +91 98791 13255
✉️ shreeradha.services@gmail.com
🌐 www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
✉️ shreeradha.services@gmail.com
🌐 www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
About the Author:
Paresh Chaudhary
Founder, Shree Radha Financial Services (SR Wealth), Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN: 05763
IRDAI Licensed Insurance Distributor
BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
This Article is also availble on Medium: https://medium.com/@shreeradha.services/the-market-doesnt-announce-when-it-s-safe-to-invest-again-a4350fab2222
Disclaimer: This article is for educational purposes only and does not constitute investment advice. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully. Data and figures cited are as available at the time of writing and are subject to change; please consult a qualified professional for advice specific to your situation.