If your mutual fund app has been showing red all week and you’re wondering should I stop SIP when market falls, here’s a better question to start with: has the thing you were saving for changed? For most people the honest answer is no — the flat is still three years away, the wedding is still eight years away, the child still needs that education fund in 2038. The market moved. The goal didn’t.
That distinction matters more than any NAV chart, because a SIP was never a bet on this month’s market. It’s a plan built around your own date and your own number. Four people below are running exactly that kind of plan right now — and instead of asking should I stop SIP when market falls, each of them asked a different question: how do I buy a little more, a little cheaper, this month?
If you’ve already stopped a SIP in the past and are wondering how to get back on track, our guide on restarting a SIP after stopping is the better starting point than this one. And if you haven’t started a SIP at all yet, it’s worth reading what delaying that first SIP actually costs before deciding to wait for calmer markets.
Priya, 26, Ahmedabad — a home that’s finally hers, 7 years away
Priya grew up moving houses. Twice her family had to shift because a landlord raised the rent beyond what they could manage, and she remembers her mother crying the second time, packing boxes for a home they’d made comfortable over six years. When Priya started earning, the first thing she did was start a SIP of ₹12,000 a month with one number in her head — ₹18 lakh, enough for the down payment on a 1BHK that no one can ask her to leave. Seven years, one number, no negotiation.
This week, watching that SIP turn red for the first time, her instinct was to pause it “until things look better.” Instead, she did something smaller but sharper — she took the ₹8,000 she’d set aside for a phone upgrade and added it as a one-time top-up into the same fund. Her phone can wait another few months. Her flat, bought a little cheaper this week because of the fall, cannot un-happen.
Sanjay Bhai, Surat — a wedding promise made the day his daughter was born, 8 years away
Sanjay Bhai has run a textile trading business for over fifteen years, and the day his daughter Kavya was born, he made himself one promise — whatever her wedding needed, there would be no compromise. His SIP of ₹50,000 a month, running four years now, is built around that promise: a target of ₹45 lakh by the time Kavya turns 24.
What kept him from panicking this week is something he already knows from his own shop floor. When yarn prices drop, a trader who understands his business doesn’t sit on his hands — he buys more stock, because he knows the discount won’t last and the demand for cloth always comes back. He applied the exact same instinct to his SIP. This month, instead of even considering a pause, he added a one-time lumpsum top-up of ₹2 lakh from his business’s surplus reserve into the same fund — at the lower price.
The numbers make the point better than the sentiment does. If the fund’s NAV was ₹20 last month and has fallen to ₹18 this month, that same ₹2 lakh buys 11,111 units instead of the 10,000 units it would have bought a month ago — 1,111 extra units, for the same money, simply because he moved when the price dropped instead of waiting for it to recover. Those 1,111 units don’t cost him anything extra. They cost him nothing but the willingness to buy on sale, the same instinct that’s kept his shop profitable through every cotton-price cycle for fifteen years.
Should I Stop SIP When Market Falls? The Real Question to Ask First
Every version of this question — should I stop SIP when market falls, should I pause it, should I just wait it out — comes down to the same test: is this about the market, or is this about you? A market fall is temporary; India’s benchmark indices have absorbed sharper corrections than this one before and recovered. A genuine change in your income or your goal is a different problem entirely, and no amount of SIP theory fixes that one. Ritu’s situation below is a good example of staying firmly in the first category.
Ritu, Pune — a foreign education for her son that she never got to have, 12 years away
Ritu wanted to study abroad after her engineering degree. Her family couldn’t afford it at the time, and she’s carried that “what if” quietly for years. When her son was born, she promised herself he wouldn’t have to carry the same one. She’s running an STP — moving a bonus of ₹9 lakh from a liquid fund into equity over eight months — building toward a ₹60 lakh fund for his education twelve years from now.
Watching the equity side of that transfer dip this week, her first thought was to pause the STP the way she’d pause a SIP. Instead, she did the opposite — she moved one additional, out-of-cycle transfer into the equity fund this month, on top of her scheduled instalment, specifically because the price was lower. Twelve years is a long runway. A cheaper entry point somewhere in the first year of that runway is not a risk to avoid — it’s the kind of head start she never had, and one her son now will.
Rajendra, Rajkot-origin, Dubai — coming home to retire, 15 years away
Rajendra has worked in Dubai for eleven years, and the plan has always been the same one his father asked him about on his last visit home — come back, settle near family in Rajkot, retire with dignity. His SIP, funded by a fixed monthly remittance, is built around a ₹2 crore retirement corpus fifteen years out.
This week’s headlines made it sound like bad news twice over for him — a falling Indian market and a weaker rupee. He read it the other way. With the rupee near ₹95 to the dollar, the same AED transfer he sends every month converts into more rupees than it did earlier this year — and those extra rupees are now also buying fund units at a lower NAV.
So this month, on top of his regular SIP, he sent one additional remittance specifically to add a lumpsum into the same fund — a rare month where the currency and the market moved in his favour at the same time, and he didn’t want to let it pass. His retirement number is a large one, and pieces like is ₹2 crore actually enough to retire on are worth reading alongside this one.

Three ways to add more when the market falls — not just continue
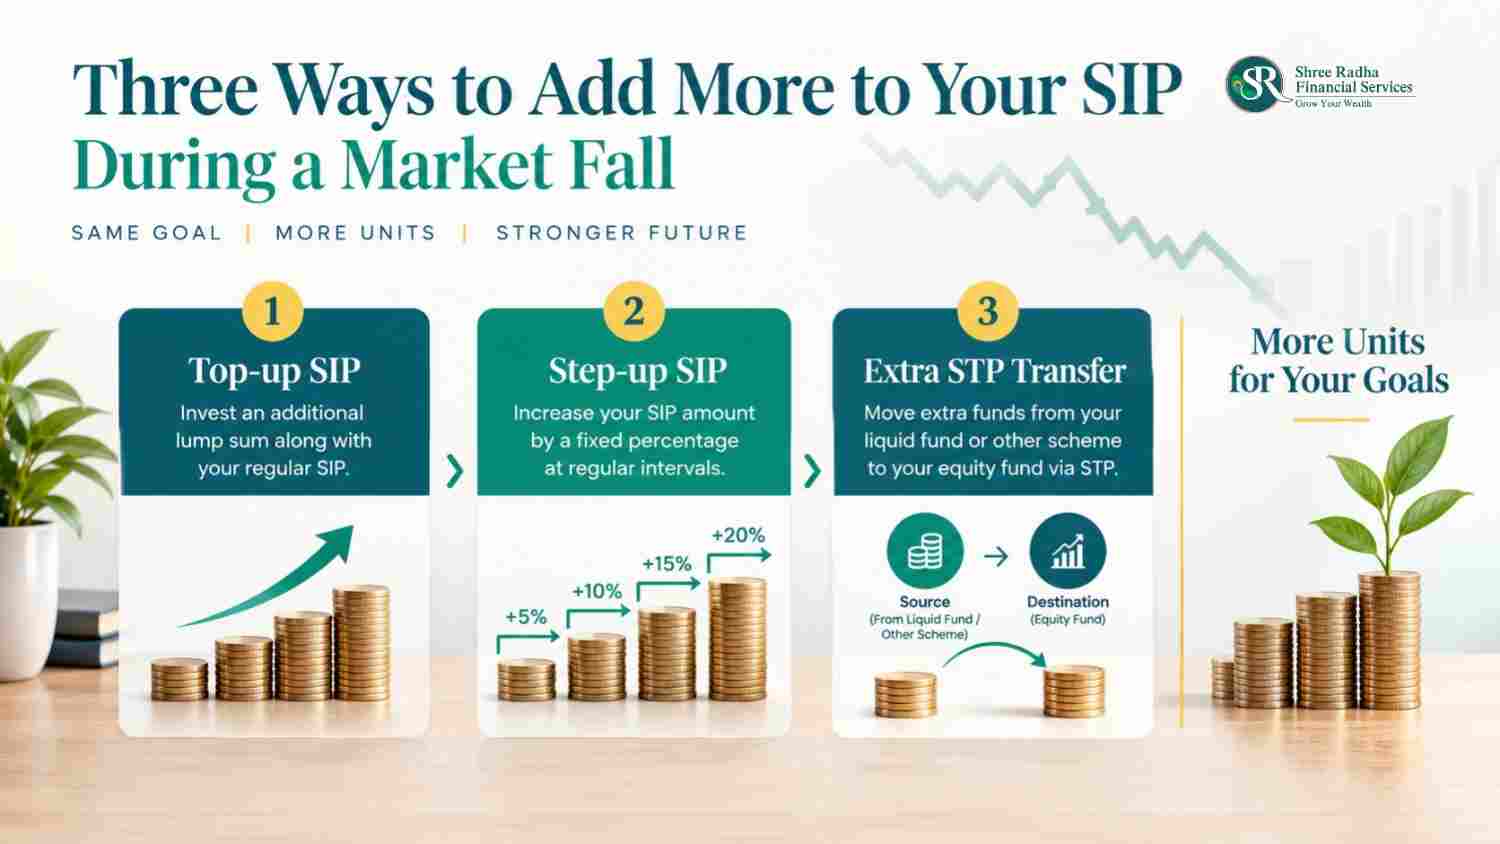
Each of the four stories above used a slightly different route to the same idea, and none of them started from the question should I stop SIP when market falls — they started from how do I buy at a cheaper price, the same way you’d stock up on something you were always going to buy anyway, the moment it goes on sale. Here are the three practical ways to do it.
- One-time lumpsum top-up. Use a bonus, a business surplus, or money set aside for a discretionary purchase, and add it into your existing SIP fund as a single additional investment — the way Priya and Sanjay Bhai did. This is the simplest way to buy extra units at today’s lower price without disturbing your regular monthly SIP at all.
- Temporary step-up of your monthly SIP. Increase your existing SIP amount for a few months during the fall — the way our step-up SIP guide explains — say from ₹15,000 to ₹20,000, and step it back down once you’re comfortable. This spreads your extra buying across a few months instead of one lumpsum, useful if you’d rather not commit a large amount all at once.
- An extra or accelerated STP transfer. If you’re running an STP like Ritu, move one additional transfer out of cycle, or increase the transfer amount for a month or two, so more of your money crosses into equity while the price is lower.
For NRIs, there’s a fourth lever worth watching alongside these three — timing a remittance for months when the rupee itself is favourable, the way Rajendra did, so the currency and the market discount work together rather than separately.
When a pause genuinely does make sense
None of this means every SIP should be topped up no matter what. A pause is the right call when the situation has actually changed, not just the market.
- A genuine income shock — job loss, business closure, a medical emergency — where the SIP amount is needed for survival, not comfort.
- The goal itself has changed or disappeared, not just gotten temporarily more expensive to reach.
- You’re within 2-3 years of needing the money and haven’t yet shifted to a more conservative allocation — this is a planning gap to fix regardless of what the market is doing this week, not a reason to stop investing altogether.
“In three and a half years of doing this, the investors who’ve done best through a fall aren’t the ones who found a clever exit. They’re the ones who kept their eyes on the date and the number they were saving for, and treated the dip as a chance to add a little more toward it — not a reason to stop.” — Paresh Chaudhary, Founder, Shree Radha Financial Services
Frequently Asked Questions
Should I stop SIP when market falls?
Usually not — your goal and horizon haven’t changed just because the market has. A running SIP is designed to buy more units when prices are lower, so a fall works in its favour rather than against it, unless you’re facing a genuine income emergency or the underlying goal itself has changed.
What is the best way to add more to my SIP during a market fall?
There’s no single best way — it depends on how much extra you have and how comfortable you are committing it at once. A one-time lumpsum top-up suits a bonus or surplus; a temporary step-up spreads the extra buying over a few months; an additional STP transfer suits anyone already staggering a lumpsum into equity.
Is it better to do a lumpsum top-up or a step-up SIP during a dip?
A lumpsum top-up buys more units immediately at today’s price, which suits money you already have on hand. A step-up spreads the extra investment across a few months, which suits money you’re setting aside gradually. Neither is wrong — the choice depends on your cash flow, not the market.
Should I redeem my mutual funds when the market falls?
Redeeming converts a temporary, on-paper drop into a permanent, realised loss. Unless the money is needed immediately for its intended goal, a fall is generally not the moment to redeem.
Can I pause my SIP for a few months instead of stopping it completely?
Yes, most fund houses allow a temporary pause of one to three months without cancelling the mandate entirely. If you genuinely need a break, this is a better option than a full stop, since it keeps the SIP structure intact.
How do NRIs benefit from a market fall combined with a weaker rupee?
When the rupee weakens against an NRI’s earning currency, the same remittance converts into more rupees — and if the market has also fallen, those extra rupees buy units at a lower NAV too. It’s one of the few situations where two separate headlines end up working in the same direction.
Talk to SR Wealth about topping up your SIP the right way
📞 +91 98791 13255
✉️ shreeradha.services@gmail.com
🌐 www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
📞 +91 98791 13255
✉️ shreeradha.services@gmail.com
🌐 www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
About the Author:
Paresh Chaudhary
Founder, Shree Radha Financial Services (SR Wealth), Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN: 05763
IRDAI Licensed Insurance Distributor
BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
This Artical is Also availble on Medium: https://medium.com/@shreeradha.services/the-textile-trader-who-bought-1-111-extra-mutual-fund-units-on-purpose-7436991005ad
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN: 05763). It does not provide stock-specific advice and is not a SEBI Research Analyst or Investment Adviser; nothing here should be construed as a recommendation to buy, sell, or hold any security, or an endorsement or criticism of any named platform. Registration details for third-party platforms mentioned are cited as publicly disclosed by those platforms as of the time of writing and should be independently re-verified on sebi.gov.in. The personas in this article (Om, Chetan Bhai, and Sagar) are illustrative composites, not real clients, and their figures are for illustration only. Please consult a SEBI-registered Research Analyst or Investment Adviser for stock-specific guidance, and a qualified professional for any investment decision.