Income From Other Sources: Four Mistakes That Begin With “Nothing Was Deducted”
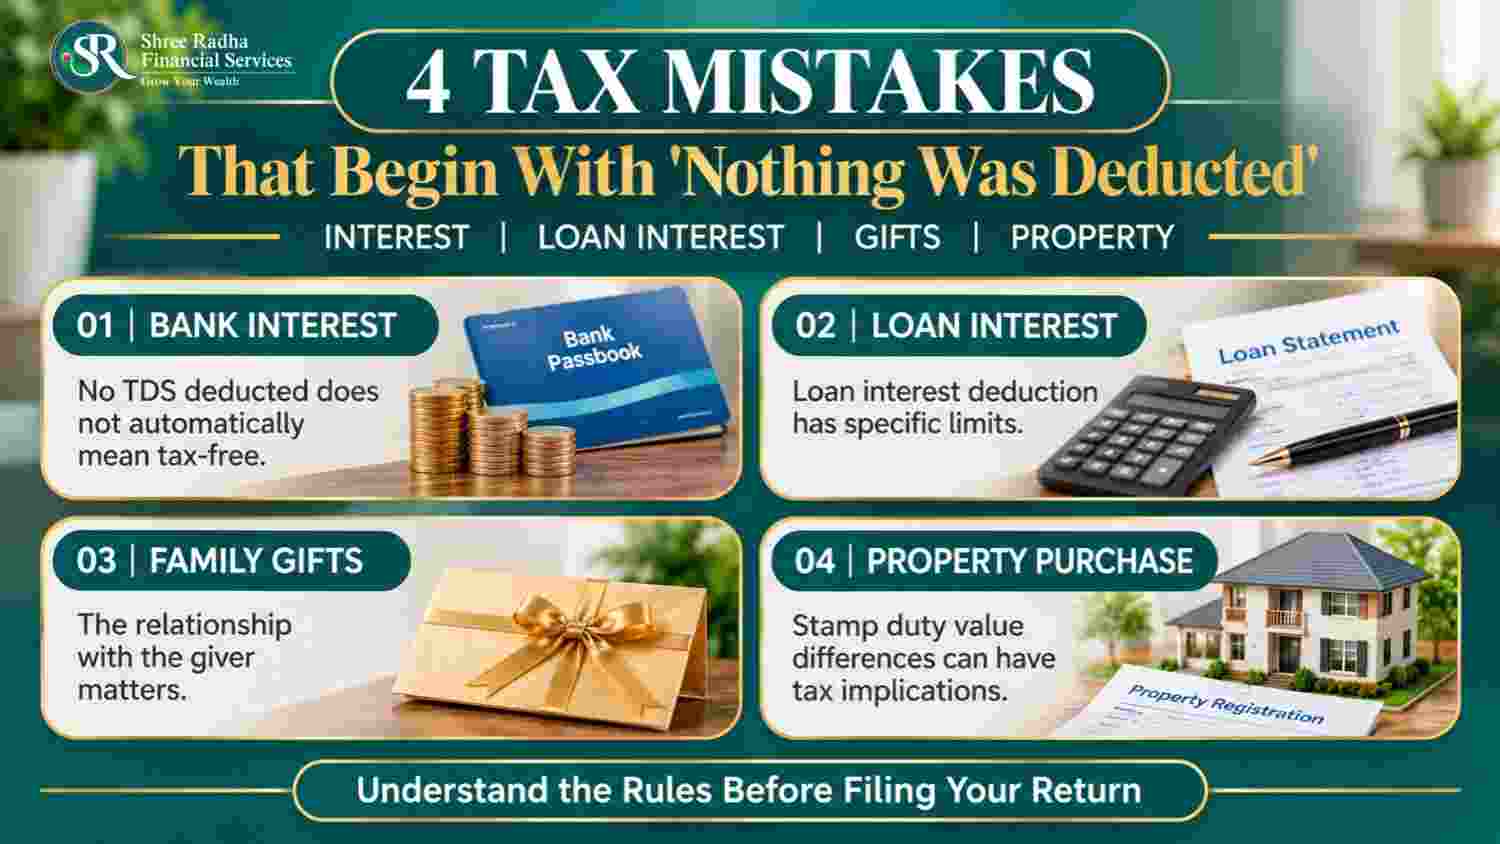
Income from other sources is the part of your tax return that most people forget until a notice arrives. It covers bank interest, dividends, certain gifts and a few other receipts that do not fit under salary, house property, business or capital gains.
The trouble is simple. Money comes in quietly, no TDS is cut, and it feels like it does not count. Under the Income-tax Act 2025 (Tax Year 2026-27), it often does.
Note: The people and numbers in the four stories below are illustrative, to explain the rules. They are not real clients.
“Most families I meet watch the salary slip carefully. The small credits are the ones that cause trouble: a bank interest entry, a dividend, a gift from a relative. Know which of these the law treats as income before the tax return, not after.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
Story 1: Nashik, the Retired Teacher Whose Banks Cut No TDS
Mr. Deshmukh, 62, retired from a school in Nashik. He keeps fixed deposits in four different banks. Each bank pays him about Rs 60,000 interest a year, so the total is about Rs 2,40,000.
No bank cut TDS, because each one paid less than the TDS limit for senior citizens. He took this to mean the interest was not taxable.
What went wrong
TDS is only a collection method. Whether tax is due depends on his total income, not on whether a bank deducted anything. His Annual Information Statement (AIS) showed all four interest amounts, and his return did not. The mismatch led to a notice.
The right way
Add up interest from every bank, post office and deposit before filing. Compare the total with AIS. Report all of it under income from other sources.
One more point for seniors. The deduction on deposit interest in Section 153 (earlier Section 80TTA / 80TTB) is not available under the new regime in Section 202. Whether the old or new regime suits him is a calculation to do with your CA. Our old vs new tax regime guide explains the basics.
Story 2: Bengaluru, the Investor Who Expected to Deduct Loan Interest
Vivek, 41, works in IT in Bengaluru. He took a loan against his shares and used it to buy more dividend-paying stocks. In the year he paid Rs 1,60,000 interest on that loan and received Rs 1,20,000 in dividends.
He planned to deduct the loan interest from the dividends and show no income. His older tax guide said up to 20% of the dividend could be claimed as interest expense.
What went wrong
That old rule is gone. Section 93(2) of the Income-tax Act 2025 now says no deduction is allowed against dividend income or income from specified mutual fund units. The change applies from 1 April 2026. Demat charges and other costs also cannot be claimed against dividend.
The company had deducted 10% TDS on the dividend. Vivek assumed that was his final tax. Dividend is added to total income and taxed at slab rate, so a higher-slab taxpayer can owe more.
The right way
Show the full gross dividend as income. Do not claim expenses against it. Check whether advance tax applies if the tax still payable after TDS is Rs 10,000 or more (Section 404; instalment dates in Section 408). Ask your CA before filing.
For mutual fund investors: income from fund units follows the same no-deduction rule, and mutual fund investments are subject to market risks. Read all scheme-related documents carefully. Our mutual fund taxation guide covers capital gains separately.
Story 3: Kolkata, the Cousin Who Gave Rs 5 Lakh
Debasish, 34, lives in Kolkata and was buying his first flat. His first cousin, the son of his father’s brother, sent Rs 5 lakh by bank transfer to help with the down payment. “He is family,” said Debasish. “Family gifts are tax-free.”
What went wrong
The law does not use the word “family”. It uses the word “relative”, and the list is fixed. A first cousin is not on it. Under Section 92(2)(m), money received without consideration is taxable in full if the total from non-relatives in the tax year is more than Rs 50,000. The whole Rs 5 lakh is taxed, not just the part above Rs 50,000.
Debasish’s uncle, his father’s brother, is a relative. If the uncle had sent the money, it would have been exempt.
The right way
Check the relative list before accepting a large gift. Use bank transfers and keep a written record. If the money is genuinely a loan, a written loan agreement with clear terms is different from a gift. Whether it fits your case is a point to confirm with your CA. For gifts of property, our gift deed guide explains the paperwork side.
Story 4: Nagpur, the Flat Bought Below Stamp Duty Value
Mr. Gokhale, 38, from Nagpur, bought a flat from a seller in a hurry. The agreed price was Rs 60 lakh. The stamp duty value on the registration records was Rs 70 lakh.
He felt he had got a good deal. His accountant said it might also create a tax bill.
What went wrong
Under Section 92(2)(m)(ii)(B), when immovable property is bought for less than its stamp duty value, the excess can be taxed in the buyer’s hands. The test: the excess must be more than the higher of Rs 50,000 or 10% of the price.
Here the excess is Rs 10 lakh. Ten percent of Rs 60 lakh is Rs 6 lakh. Rs 10 lakh is more than Rs 6 lakh, so Rs 10 lakh is taxed as income from other sources.
The right way
Check the stamp duty value before fixing the price. Section 92(4)(a) says that if the agreement date and registration date differ, the stamp duty value on the agreement date can apply, but only if part of the payment was made by a specified banking or online mode on or before the agreement date. If the value is disputed, Section 92(4)(b) allows a reference to a Valuation Officer. Take your CA’s view before signing.
The seller’s side is a capital gains matter. See our Section 54 capital gains guide.
What Income From Other Sources Covers Under Section 92
Section 92(1) of the Income-tax Act 2025 (earlier Section 56 of the 1961 Act) works as a catch-all. Income that is taxable but does not belong to any other head goes here. Section 92(2) lists examples.
| Receipt | Section (2025 Act) | What to remember |
|---|---|---|
| Bank, post office and other deposit interest | Section 92(1) | Taxable at slab rate unless it belongs to business income |
| Dividend | Section 92(2)(a) | Gross dividend is taxed; no deduction under Section 93(2) |
| Interest on securities | Section 92(2)(e) | Only banker’s commission can be claimed (Section 93(1)(a)) |
| Life insurance sum above premiums paid | Section 92(2)(l) | Applies only if not exempt under Schedule II (Sl. 2); check with your CA |
| Gifts of money or property | Section 92(2)(m) | Rs 50,000 test; exempt categories in Section 92(3) |
Rules and rates change from time to time. Please confirm with your tax consultant / CA.
Income From Other Sources: Gifts, Relatives and the Rs 50,000 Test
Gifts are where most reader mistakes sit. Section 92(2)(m) applies to anyone who receives money or property without paying for it. All amounts from all givers in the tax year are added together.
| What you receive | When it is taxable | Amount taxed |
|---|---|---|
| Money, no payment made | Total in the year is more than Rs 50,000 | The whole sum |
| Land or building, no payment made | Stamp duty value is more than Rs 50,000 | The stamp duty value |
| Land or building, bought for less than stamp duty value | Excess is more than the higher of Rs 50,000 or 10% of the price | The excess over the price |
| Shares, jewellery, bullion and similar property, no payment made | Total fair market value is more than Rs 50,000 | The whole fair market value |
| Such property, bought for less than fair market value | Shortfall is more than Rs 50,000 | The shortfall |
Now, the exemptions. Section 92(3) says the gift rule does not apply to the cases below.
| Exempt case (Section 92(3)) | Plain meaning |
|---|---|
| From any relative | Any amount, if the giver is on the fixed relative list |
| On the occasion of marriage of the individual | Gifts at your own wedding, not at a sibling’s or friend’s |
| Under a will or by inheritance | Received after a person’s death |
| In contemplation of death of the giver | Given because death is expected |
| From a local authority or registered non-profit organisation | Subject to the conditions in the Act |
| Certain transactions not treated as a transfer, and trusts solely for relatives | Section 92(3)(g) and (h); check with your CA |
Birthdays, anniversaries and housewarming parties are not on this list. Gifts from non-relatives on those days follow the Rs 50,000 test.
| Person | Relative? | Basis in Section 92(5)(g) |
|---|---|---|
| Spouse | Yes | Item (A) |
| Brother or sister | Yes | Item (B) |
| Brother or sister of your spouse | Yes | Item (C) |
| Brother or sister of either parent (uncle, aunt) | Yes | Item (D) |
| Parents, grandparents, children, grandchildren | Yes | Item (E) |
| Parents, grandparents and descendants of your spouse | Yes | Item (F) |
| Spouse of any person in items (B) to (F) | Yes | Item (G) |
| First cousin | No | Not in the list |
| Friend, neighbour, employer | No | Not in the list |
For a Hindu undivided family, any member is a relative.
What Can Be Deducted Under Section 93
Section 93 (earlier Section 57) allows only a short list of deductions. For interest on securities, banker’s commission is allowed. For family pension, the deduction is the lower of one-third or Rs 25,000 where tax is computed under Section 202(1), and the lower of one-third or Rs 15,000 otherwise.
For dividend and income from specified mutual fund units, nothing is allowed. This is the single biggest change from the 1961 Act for investors who borrow to invest.
TDS on Interest and Dividend: What Is Deducted and What Is Not
| Payment | TDS limit seen in the Act text | Remember |
|---|---|---|
| Bank interest | Rs 1,00,000 for senior citizens; Rs 50,000 for others | TDS below the limit is not the same as no tax |
| Interest on securities | Rs 10,000 | Tax still applies on the full amount |
| Mutual fund income | Rs 10,000 at 10% | Part of total income at slab rate |
| Dividend from a domestic company | 10% (limit shown as nil in the downloaded text; confirm) | 10% TDS is not the final tax |
These limits come from the Act text on the Income Tax Department website. They may be updated, so please check the current position with your CA. People whose total income is below the taxable limit can look at Form 121 under Section 393(6) (earlier Form 15G / 15H).
| Subject | 1961 Act | 2025 Act |
|---|---|---|
| Income from other sources | Section 56 | Section 92 |
| Gifts of money and property | Section 56(2)(x) | Section 92(2)(m) |
| Exempt gifts and “relative” | Provisos and Explanation to Section 56(2) | Sections 92(3) and 92(5)(g) |
| Deductions from other sources | Section 57 | Section 93 |
| Deduction on deposit interest | Sections 80TTA / 80TTB | Section 153 (not in the new regime) |
| New tax regime | Section 115BAC | Section 202 |
| Forms to avoid TDS | Section 197A (Form 15G / 15H) | Section 393(6) (Form 121) |
Official Sources to Read
- Income Tax Department: the Income-tax Act page with Section 92 and Section 93.
- e-Filing portal: incometax.gov.in, where you can view your AIS.
- AMFI: amfiindia.com for mutual fund scheme information.
Read these along with our guides on income tax computation and fixed deposit tax. This head is easier to follow once you see how it fits into total income.
How SR Wealth Can Help
Shree Radha Financial Services is an AMFI Registered Mutual Fund and SIF Distributor and an APMI Registered PMS Distributor. We are not tax consultants. What we do:
- Explain the products you hold or are considering, such as mutual funds, SIF, PMS and deposits
- Help you understand how your investments may create income from other sources, so you can discuss it with your CA
- Connect you with a competent CA or tax consultant if you need one for your salary tax, return or notice
Income From Other Sources: Frequently Asked Questions
1. Is savings account interest tax-free in the new tax regime?
No. Interest is part of income from other sources. The deduction in Section 153 (earlier 80TTA / 80TTB) is not available under the new regime in Section 202.
2. Is a gift from a cousin or friend taxable?
Yes, if the total received from non-relatives in the tax year is more than Rs 50,000. The whole amount is taxed. A first cousin is not on the relative list in Section 92(5)(g).
3. Are wedding gifts exempt?
Gifts received on the occasion of your own marriage are exempt under Section 92(3)(b). Gifts at a brother’s or friend’s wedding are not covered by that clause.
4. Are birthday and anniversary gifts exempt?
There is no separate exemption. If the giver is a relative, it is exempt. If not, the Rs 50,000 test applies.
5. How is dividend taxed?
Dividend is added to your total income and taxed at your slab rate. TDS at 10% may be cut, but it is not the final tax for everyone.
6. Can I claim expenses or loan interest against dividend?
No. Section 93(2) allows no deduction against dividend or income from specified mutual fund units. The earlier limited interest deduction ended on 1 April 2026.
7. If no TDS was deducted, do I still pay tax on interest?
Yes. TDS limits decide whether the bank deducts tax, not whether the income is taxable. Check AIS for all banks.
8. What is the stamp duty value rule when buying property?
If the stamp duty value is higher than the price you paid and the excess is more than the higher of Rs 50,000 or 10% of the price, the excess is taxed in your hands under Section 92(2)(m)(ii)(B).
9. Do I need Form 15G or 15H?
These forms were used to ask a bank not to deduct TDS when income is below the taxable limit. In the 2025 Act the provision is Section 393(6) with Form 121. Ask your CA if you qualify.
10. Who pays tax on interest from money I gave my spouse?
Income earned from assets given to a spouse can be clubbed with the giver’s income under Section 99. This is a separate topic, so please check with your CA.
This article is also available on Medium for wider reading:https://medium.com/@shreeradha.services/nothing-was-deducted-so-nothing-is-due-a-common-tax-mistake-in-india-1c44c0353b8b
Planning Your Investments and Income?
If you want to talk about SIPs, mutual funds, SIF or retirement income planning, connect with Shree Radha Financial Services for a personalized discussion.
📞 Call/WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services, Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN05763
IRDAI Licensed Insurance Distributor
Investing since 2012 | BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN05763). All content is strictly for educational purposes only and does not constitute individualized investment or tax advice. The characters in this article are fictional. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing. Rules and rates change from time to time. Please confirm with your tax consultant / CA. Tax treatment is based on current laws and subject to change.