NRI Land Property Rules in India: Four Families, One Land Record They Never Checked
NRI land property rules India are more misunderstood than almost any other compliance area NRIs deal with — not because the rules are hidden, but because land back home means something different once you’ve left it. A plot near the ancestral house, a flat bought for a parent, or the family home sold after a parent’s passing isn’t really a “real estate transaction” to an NRI. It’s a piece of belonging, handled long-distance, usually through someone else’s hands.
That distance is exactly where the mistakes happen. Four families, four cities, four completely different mistakes — all sitting inside the same set of NRI land property rules India that almost nobody reads until something goes wrong.
Biju’s Land That Was Never His to Buy
Biju Varghese has spent eleven years in Doha, working in project engineering for a construction firm. Every trip home to Kochi, he’d drive past a stretch of land near his ancestral house — coconut groves, a stream at the edge, the kind of plot he pictured retiring on someday.
Two years ago, a broker told him the owner was selling, and that the land had been “converted” — meaning, in the broker’s words, it was fine for an NRI to buy. Biju wired the token amount from his NRE account and signed the agreement to sell on his next visit.
It was only when his brother-in-law, a local lawyer, pulled the actual land records before registration that the truth surfaced. The land was still classified agricultural in the revenue records. No conversion order had ever been passed — the broker had confused “not currently farmed” with “converted to non-agricultural use.” Two very different things, and only one of them matters to the law.
Under the Foreign Exchange Management Act and RBI’s rules on acquisition of immovable property, read with the Foreign Exchange Management (Non-Debt Instruments) Rules, 2019, an NRI or OCI simply cannot purchase agricultural land, plantation property, or a farmhouse in India — regardless of intent, budget, or how long the transaction has been in the works. It isn’t a paperwork formality to work around.
If the deal had gone through anyway, the sale would have been void from the start, with no legal title ever passing to Biju. Under Section 13 of FEMA, the penalty for the violation can run up to three times the transaction value.
The land Biju actually wanted came to him a different way. His own mother later chose to gift a portion of the family’s ancestral plot directly to him. A gift from a resident Indian relative is one of only two lawful routes for an NRI to hold agricultural land — the other is inheritance, the same route our NRI Will for Indian Assets guide walks through for NRIs planning ahead. Both routes exist because the law isn’t blocking NRIs from ever owning agricultural land — it’s blocking them from buying it as an outsider with foreign capital.
“Most NRI land mistakes I see aren’t about people trying to break a rule. They’re about someone trusting a broker’s version of the rule instead of the land record itself. The record doesn’t care what the broker called it.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
Nikhil’s Power of Attorney — Two Mistakes, Not One
Nikhil Deshpande moved to Muscat eight years ago and has worked his way up to a senior role at an auto-ancillary manufacturer. When his parents in Pune decided to sell their ageing bungalow and move into a smaller flat, Nikhil — co-owner on the property alongside his father — couldn’t fly down for the registration in the middle of a plant audit at work.
Mistake one: the wrong kind of Power of Attorney. Nikhil did what he’d heard many NRIs do. He signed a General Power of Attorney in favour of his father, notarised quickly at the Indian consulate before a work trip, authorising his father to “act on his behalf in all matters.” It felt thorough. It felt like it covered everything.
The buyer’s lawyer flagged it at the sub-registrar’s office. A General POA — broad, not tied to the specific property or transaction — is exactly the kind of document sub-registrars increasingly reject outright, and the kind that can get a completed sale deed challenged later. What the transaction needed was a Special Power of Attorney: specific to that one property, listing the transaction details, executed abroad, attested by the Indian consulate, and adjudicated (stamped) in India within three months of receipt.
Nikhil had to redo the POA from Muscat — a fresh document, properly scoped this time — which pushed the registration back by five weeks while his parents’ moving timeline sat in limbo.
Mistake two: assuming the POA holder could also receive the money. With the corrected POA finally in place, a second assumption nearly slipped through unnoticed. The buyer’s family, eager to close quickly, suggested transferring the sale proceeds directly to Nikhil’s father — “since he’s handling everything anyway, why complicate it with an NRO transfer.” Nikhil’s father, trusting and eager to help his son, almost agreed.
It was Nikhil’s bank that caught it before any funds moved. A Power of Attorney authorises someone to sign and execute documents on the NRI’s behalf — it does not transfer ownership of the sale proceeds. Payment for an NRI’s property must go directly into the NRI’s own NRE or NRO account, never to the POA holder, however close the relationship. Route it any other way, and the transaction opens itself up to disputes over whose money it actually is, questions about TDS compliance, and — in less honest situations — outright misappropriation.
Both mistakes traced back to the same instinct: treating “someone I trust is handling it” as the same thing as “the transaction is compliant.” It usually isn’t, and the fix for both was the same — read what the document and the payment route are actually supposed to look like, before signing or wiring anything.
Srikanth’s ₹17 Lakh Notice — For Buying, Not Selling
Srikanth Rao lives in Hyderabad’s Gachibowli belt, works in a mid-sized IT firm, and bought a resale flat last year from a seller named Deepak — an old family acquaintance who’d moved to New Jersey a decade earlier. Deepak had a PAN card, an Aadhaar card, and every document looked exactly like a resident seller’s paperwork.
Srikanth deducted 1% TDS on the ₹1.4 crore sale value under Section 194-IA — the rule he’d heard applies to property purchases — and filed it through his bank as usual.
Eight months later, an income tax notice arrived, addressed to Srikanth, not Deepak. Deepak was, in fact, an NRI under the Income Tax Act, having spent under 182 days in India that financial year. Having Aadhaar and PAN means nothing about residential status — an NRI can hold both and still be a non-resident for tax purposes.
When the seller is an NRI, Section 194-IA’s 1% rule doesn’t apply at all. The purchase falls under Section 195 of the Income Tax Act instead, and three things change at once.
First, there’s no ₹50 lakh exemption threshold the way there is for resident sellers — Section 195 applies to the transaction regardless of size. Second, the buyer needs a TAN, not just a PAN, to deduct this correctly. Third, and this is what caught Srikanth out most: without a Lower Deduction Certificate from the seller under Section 197, TDS is calculated on the entire sale consideration, not just the profit.
Since Deepak had owned the flat for over 24 months, the gain counted as long-term, taxed at a flat 12.5% following the 2024 Budget changes, plus applicable surcharge and 4% cess. On the ₹1.4 crore sale value, that worked out to roughly ₹18.2 lakh in correctly-computed TDS. Srikanth had deducted just ₹1.4 lakh — a shortfall of close to ₹17 lakh, and the notice demanded the difference along with interest.
What Srikanth eventually did was work with a chartered accountant to file a corrected Form 27Q — the quarterly filing used for payments to non-residents, distinct from the simpler Form 26QB used for resident sellers — and pay the differential with interest. For future transactions, his rule now is simple: ask a seller directly, in writing, whether they qualify as an NRI under the Income Tax Act before assuming the 1% rate applies.
Where the seller can obtain a Section 197 certificate in advance, it also caps the TDS to the actual gain rather than the full sale value, preventing this kind of shortfall from happening in the first place.
Meenal’s ₹2.3 Crore, Stuck Mid-Transfer
Meenal Sharma’s family runs a gems and jewellery export business from Jaipur’s old city. When her father passed away without leaving instructions on how the family’s assets should be split, the ancestral haveli near Johari Bazaar went to Meenal and her younger brother Rajendra, who has lived in Kuwait for over a decade — a situation our Family Settlement Agreement guide covers in detail for families dividing an inherited property this way.
They agreed to sell the property and split the proceeds. Meenal would keep her share in India, and Rajendra needed his share — roughly ₹2.3 crore — moved to his account in Kuwait to fund a business expansion there.
The sale went through smoothly. The surprise came at the bank. Rajendra assumed the entire amount was his to move freely, since it was his own inherited share. But money from an NRO account — which is what inherited property proceeds route through — can only be repatriated up to USD 1 million per financial year, verified through Form 15CA/15CB with a chartered accountant’s certification. Rajendra’s ₹2.3 crore share worked out to roughly USD 2.7 million — well over the cap.
He wasn’t stuck permanently, but the timeline changed. The amount within the USD 1 million limit moved that financial year with the standard 15CA/15CB paperwork, the same process our NRO Repatriation guide walks through step by step.
The remainder needed prior RBI approval, routed through the family’s authorised dealer bank, with documentation proving the property was legitimately inherited and all applicable Indian taxes had been paid. That process took closer to ten weeks rather than the few days he’d expected, meaning the transfer had to be split across two financial years to stay within the annual cap for the balance.
NRI Land Property Rules in India — Quick Reference Table
| Property Type | Can an NRI Buy? | Lawful Routes |
|---|---|---|
| Agricultural land | No | Inheritance, or gift from a resident Indian relative |
| Plantation property | No | Inheritance, or gift from a resident Indian relative |
| Farmhouse | No | Inheritance, or gift from a resident Indian relative |
| Residential property | Yes — any number of units | Purchase via NRE/NRO/FCNR funds or normal banking channels, no RBI approval needed |
| Commercial property | Yes — any number of units | Same as residential; no two-property repatriation cap |
An OCI cardholder is treated the same as an NRI for all of the above. A foreign citizen who does not hold OCI status generally needs prior RBI approval even to buy residential property. State-level stamp duty and registration rules for gifts and transfers vary too — our Gift Deed in Gujarat guide is a useful worked example of how a gift-route transfer is actually taxed and registered, though the exact duty and process should always be checked against the specific state the land sits in.
Who Should Care About NRI Land Property Rules in India
- Any NRI eyeing land near their native place for a future home or retirement plot
- Anyone signing or receiving a Power of Attorney for a property transaction while abroad
- Resident Indians buying property from an NRI seller — the TDS obligation is the buyer’s, not the seller’s
- NRI siblings splitting or selling an inherited family property, especially across more than one country
- Anyone assuming “converted land” or “resident-looking documents” without checking the actual record
Between the four stories above and the table earlier, that covers most of what NRI land property rules India actually involve day to day. Getting the inheritance and gifting side of this right from the start is also part of a broader plan — our Estate Planning guide covers how property, Wills, and family structures like HUF fit together for exactly this kind of cross-border family situation.
NRI Land Property Rules in India — Do This, Not That
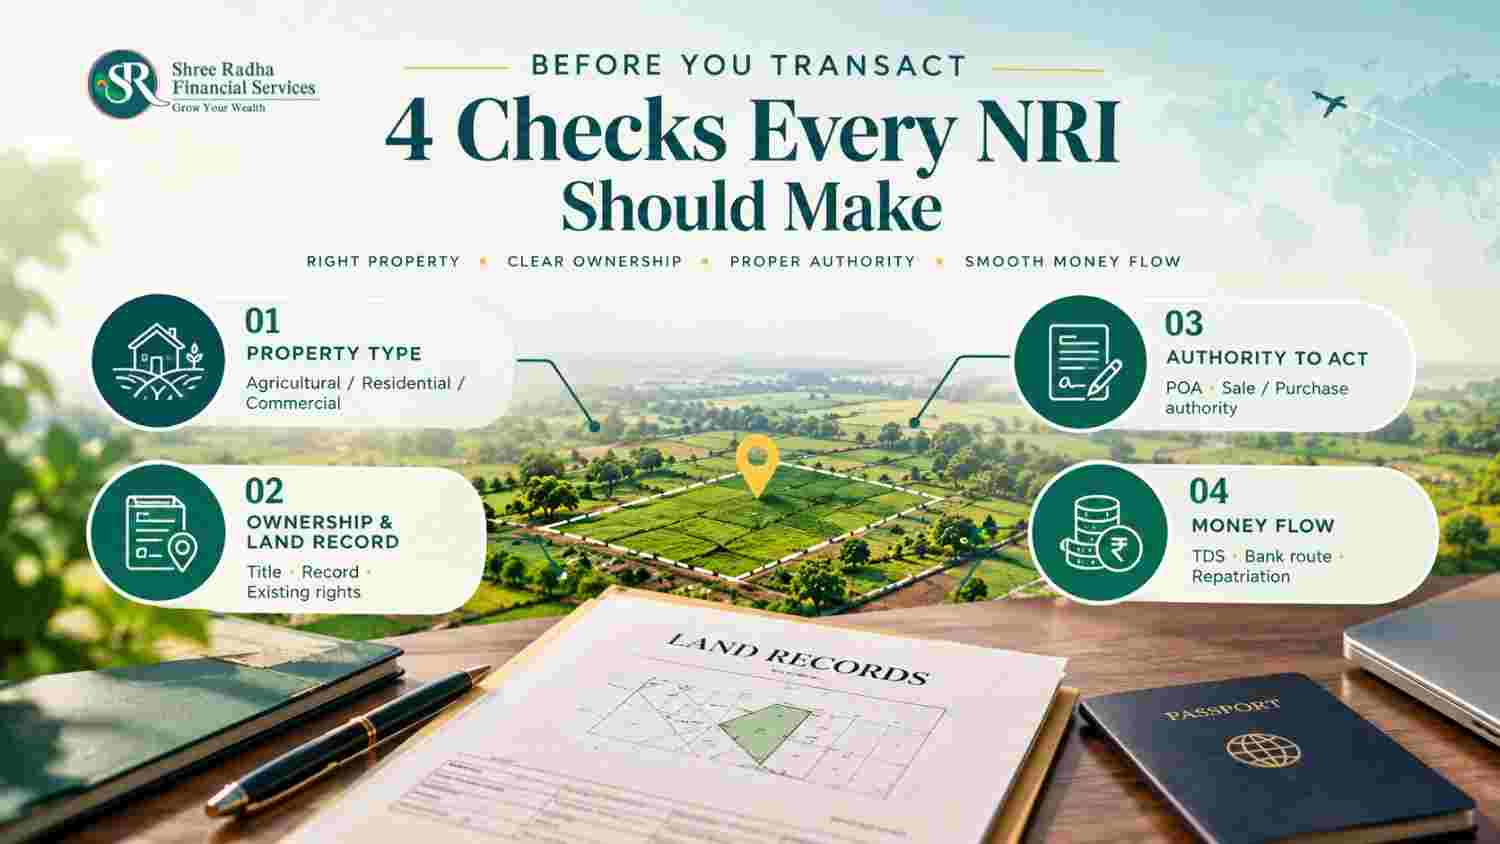
- Before paying anything toward land, pull the actual revenue/land record yourself — never rely on a broker’s description of “converted” or “non-agricultural” status.
- If the land is agricultural, plantation, or a farmhouse, the only lawful path is inheritance or a gift from a resident relative — not a purchase agreement of any kind.
- Use a Special Power of Attorney, specific to one property and one transaction — never a General POA — and get it consulate-attested and stamped in India within three months.
- Insist payment goes directly to the NRI’s own NRE/NRO account, never to a POA holder, however close the relationship.
- If you’re a resident buying from a seller who has lived or worked abroad, confirm their tax residency status in writing — Section 195, not Section 194-IA, applies the moment the seller is an NRI, at any deal size.
- Before moving inherited or NRO-linked sale proceeds abroad, check the USD 1 million per financial year cap and plan the transfer — and the paperwork — well ahead of when the money is actually needed.
Frequently Asked Questions — NRI Land Property Rules in India
What are the NRI land property rules India for agricultural land?
Not by direct purchase. The only lawful ways for an NRI to hold agricultural land, plantation property, or a farmhouse are inheritance, or receiving it as a gift from a resident Indian relative. Land already owned before becoming an NRI can also simply be retained.
Can an NRI sell agricultural land they’ve inherited?
Yes, but only to a resident Indian citizen — never to another NRI or OCI, even a sibling.
Does an NRI need RBI approval to buy a flat or an office in India?
No. Residential and commercial property purchases by NRIs and OCIs are covered under general permission — no prior RBI approval is required, and there’s no cap on the number of units.
What’s the actual risk of using a General Power of Attorney instead of a Special POA?
A General POA is broader and vaguer than what most registrars will accept for a specific property sale, and it increases the risk of the transaction — or even the sale deed itself — being challenged later. A Special POA, scoped to the exact transaction and properly consulate-attested, is the safer route.
Who is responsible for deducting the correct TDS when buying property from an NRI?
The buyer is legally responsible, regardless of what the seller’s documents look like. Buying from an NRI seller falls under Section 195, not the 1% Section 194-IA rule for resident sellers — it requires a TAN, applies at any deal size, and by default is calculated on the full sale value (not just the gain) unless the seller has obtained a Section 197 Lower Deduction Certificate.
How much money can an NRI repatriate from selling inherited property in India?
Up to USD 1 million per financial year from an NRO account, verified through Form 15CA/15CB. Amounts above that require prior RBI approval routed through an authorised dealer bank, and can take several weeks longer to process.
Need Help With NRI Land Property Rules in India?
Whether it’s a plot you’re being told is “converted,” a Power of Attorney you’re about to sign, or sale proceeds you need moved home — get the rules checked against your specific situation before you commit to anything.
No obligation. No pressure. Just a clear look at your specific numbers.
📞 Call / WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
The article is also available on Medium: https://medium.com/@shreeradha.services/the-17-lakh-mistake-nobody-sees-coming-until-its-their-money-4eaddfa5183a
About the Author
Paresh Chaudhary
Founder, Shree Radha Financial Services (SR Wealth)
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN: 05763
IRDAI Licensed Insurance Distributor
BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN: 05763). All content is strictly for educational purposes only and does not constitute individualised investment, legal, or tax advice. Property, FEMA, and tax rules are subject to change; consult a qualified legal or tax professional and verify the current regulations before any transaction. Mutual fund and PMS investments are subject to market risks — read all scheme-related documents carefully before investing. Rupee and TDS figures used are illustrative examples only and will vary by transaction. All characters, cities, and scenarios described in this article — including Biju, Nikhil, Srikanth, and Meenal — are entirely fictional and used solely for illustrative purposes; any resemblance to actual persons, living or dead, or to any real transaction, is purely coincidental.