Mutual Fund Taxation Mistakes: Do You See Yourself in These 5 Stories?
Mutual fund taxation looks simple until the day you redeem. Then the questions come fast. Which units get sold? Is a switch a sale? What is my cost? Which rate applies?
Here are five people from five cities. Four made a mistake, and one used the rules with a plan. Read their stories and ask yourself: “Am I doing the same?”
These stories are illustrative, based on common situations. Names, amounts and details are changed, and they are not individual tax advice. The tax amounts are simple examples and ignore surcharge and cess unless stated.
“Most investors check how much a fund has returned. Very few check how each unit will be taxed on the day they sell. That one check can change what you keep.” — Paresh Chaudhary
Story 1: Arjun in Bengaluru – “My SIP Is Over a Year Old, So It Is All Long-Term”
Arjun started a monthly SIP of ₹10,000 in an equity fund on 5 September 2025. On 10 December 2026, he redeemed all his units. He had invested ₹1.6 lakh in 16 instalments, and the value was about ₹1.9 lakh.
He thought, “My SIP started more than a year ago, so every unit is long-term.”
What went wrong. Each SIP instalment is a separate purchase with its own date. Only the older ones had crossed 12 months.
| Instalments | Bought on | Held on 10 Dec 2026 | Gain type |
|---|---|---|---|
| 4 (Sept to Dec 2025) | 5th of each month | More than 12 months | Long-term |
| 12 (Jan to Dec 2026) | 5th of each month | 12 months or less | Short-term |
The right way.
- For shares and units held in demat form, the cost and the holding period follow the first-in-first-out method, called FIFO (Section 67(7)(c)). The earliest units are treated as sold first.
- Short-term gains on an equity fund are taxed at 20% (Section 196). Long-term gains are taxed at 12.5% only on the part above ₹1,25,000 in a year (Section 198).
- Get the capital gains statement from the fund house or your CAS, and check each batch before you redeem. Our guide on how to download your CAS can help.
- Please ask your CA how FIFO is applied for units that are not held in demat form.
Story 2: Neha in Pune – “A Switch Is Not a Sale”
Neha held a flexicap fund bought two years ago for ₹6 lakh. It was worth ₹8 lakh. Her fund house offered a switch to a hybrid fund, to rebalance her money.
She thought, “I am only moving money inside the same fund house. I did not sell anything.” She did not include it in her return.
What went wrong. A switch means the units of the first fund are redeemed, and new units of the second fund are bought. The law treats sale, exchange or relinquishment of an asset as a transfer (Section 2(109)).
Her gain was ₹2 lakh, and it was long-term. After the ₹1.25 lakh exemption, ₹75,000 was taxable at 12.5%. That is about ₹9,375, plus cess.
The right way.
- Treat every switch as a sale and a fresh purchase.
- Check the gain before you switch, and add it to your return.
- Ask yourself whether the switch is needed. Our guide on SIP vs STP vs SWP vs Switch explains the options.
- Please ask your CA about special cases, such as the merger of plans under SEBI rules.
Story 3: Meenakshi in Chennai – “My Old Units Gave Me a Big Gain”
Meenakshi bought 1,000 units of an equity fund in 2016 at ₹100 each, so her cost was ₹1 lakh. She sold them in November 2026 at ₹250 each, for ₹2.5 lakh.
She worked out her gain as ₹1.5 lakh. That is ₹25,000 above the ₹1.25 lakh limit, so she expected to pay 12.5% on ₹25,000, about ₹3,125 plus cess.
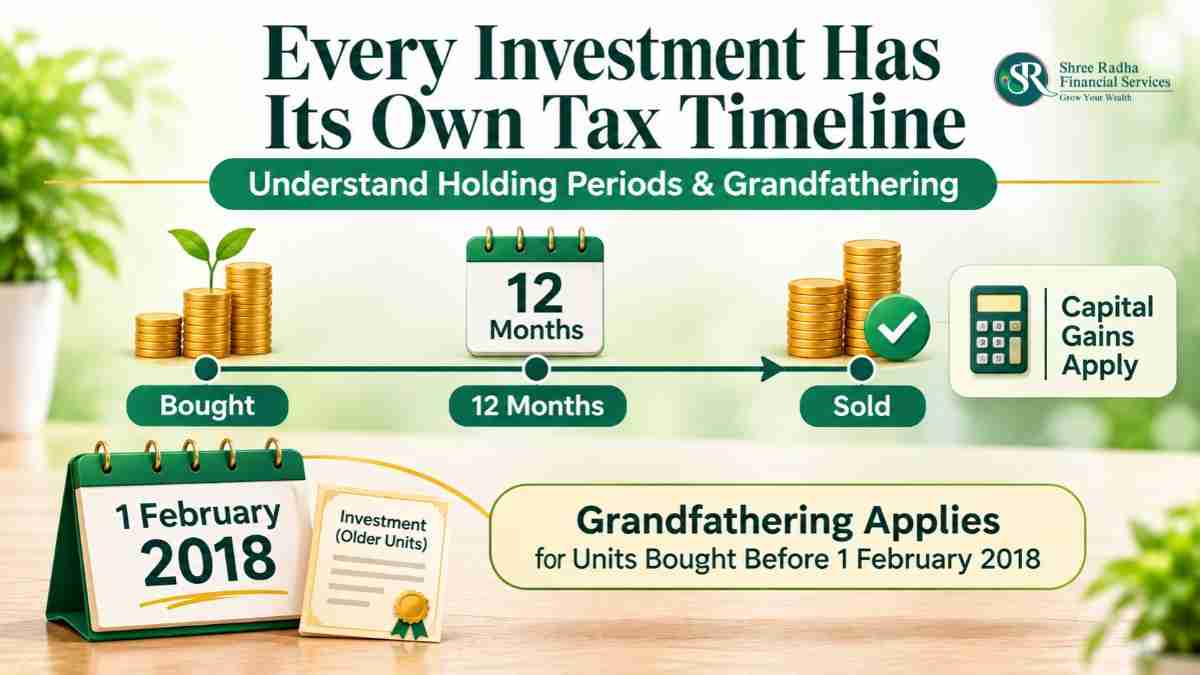
What went wrong. She used her old cost. For units bought before 1 February 2018, the law uses a higher cost, called the grandfathered cost.
The fund’s NAV on 31 January 2018 was ₹160 (example). Her cost became ₹1.6 lakh. Her gain was ₹90,000, which is within ₹1.25 lakh. So there was no tax on this gain, if she had no other long-term gains that year.
The right way. See the full explanation in the grandfathering section below. In short:
- Find the NAV on 31 January 2018 from your fund house or AMFI.
- Apply the formula in Section 90(7).
- Keep the proof with your records, and ask your CA to check the working.
Story 4: Rohit in Jaipur – “More Than Two Years, So It Must Be Long-Term”
Rohit invested ₹10 lakh in a debt fund in June 2024. In November 2026 he sold it for ₹11.2 lakh. The gain was ₹1.2 lakh.
He thought, “It is more than two years, so I will pay 12.5%.” That would have been ₹15,000.
What went wrong. Debt funds bought on or after 1 April 2023 are treated differently. His gain was taxed as a short-term gain at his slab rate. At a 30% slab, that was ₹36,000, plus cess.
The right way.
- A fund that invests more than 65% in debt and money market instruments is a “specified mutual fund”. If it was bought on or after 1 April 2023, the gain is always short-term and taxed at slab rates (Section 76).
- Check the fund’s asset mix on its factsheet before you plan a sale.
- Hybrid funds depend on their mix, so please ask your CA how yours is treated.
Story 5: Sanjay in Nagpur – A Gain Used With a Plan
This one is not a mistake. Sanjay sold shares and mutual fund units that he had held for more than 12 months. His net sale value was ₹1.2 crore, and his long-term gain was ₹40 lakh.
He was already planning to buy a home. Within the time limit, he bought a house for ₹80 lakh. He spoke to his CA first.
How it worked. People call this “Section 54”. But for gains from shares and mutual funds, the section is Section 86 (earlier Section 54F). Section 82 (earlier Section 54) is for gains from selling a house.
- Exempt gain = ₹40 lakh × (₹80 lakh ÷ ₹1.2 crore) = about ₹26.67 lakh.
- The remaining gain of about ₹13.33 lakh stays taxable as a long-term gain.
- If he had invested the full ₹1.2 crore in the house, the whole ₹40 lakh could have been exempt.
The conditions, in simple words (Section 86).
- It applies to an individual or HUF, for a long-term gain from an asset other than a residential house.
- The house must be bought one year before or two years after the sale, or built within three years after it.
- It does not apply if you own more than one other house on the date of sale, or buy or build another house within the stated time limits (Section 86(5)).
- If you sell the new house within three years, the exemption is withdrawn.
- Money not yet used must be deposited in the notified scheme before the return due date (Section 86(2)).
This is not a suggestion to buy a house for tax reasons. A house is a big decision, and the exemption depends on conditions. In our next article we will explain Sections 82, 85 and 86 in detail, with examples. Please talk to your CA before you plan.
Mutual Fund Taxation in Simple Words: Short-Term and Long-Term
Whether a gain is short-term or long-term depends on how long you held the asset and what it is (Section 2(101)). Short-term means held for 24 months or less. For listed shares, equity-oriented fund units and some other listed securities, it means 12 months or less.
| What you hold | Short-term | Long-term |
|---|---|---|
| Listed shares and equity-oriented funds (more than 65% in domestic equity), with STT paid | 12 months or less. Taxed at 20% (Section 196). | More than 12 months. 12.5% on gains above ₹1,25,000 in a year (Section 198). |
| Specified mutual funds (more than 65% in debt and money market), bought on or after 1 April 2023 | Always short-term. Taxed at your slab rate (Section 76). | Not applicable |
| Other mutual funds (for example, some hybrid funds) | 24 months or less. Taxed at slab rates. | More than 24 months. 12.5% (Section 197). |
| Unlisted shares | 24 months or less. Taxed at slab rates. | More than 24 months. 12.5% (Section 197). |
These rates are from the Act text as amended by Finance Act 2026. Surcharge and cess are extra, and the figures can change in future Finance Acts. Please check before you sell.
The ₹1.25 Lakh Limit, Explained
- It applies to long-term gains on listed shares and equity-oriented funds taken together for the whole tax year. It is not per fund.
- It does not apply to short-term gains.
- An unused part cannot be carried to the next year.
- A resident individual or HUF can also use unused basic exemption limit against these gains (Sections 196(2) and 197(2)).
- The new-regime rebate is limited to tax at the normal slab rates (Section 156(3)), so it does not reduce tax on gains taxed at 20% or 12.5%. Please ask your CA how it applies to you.
What Is an “Equity-Oriented Fund”?
It is a mutual fund that invests more than 65% of its money in equity shares of domestic companies, measured as an annual average (Section 198(8)). Please check your fund’s factsheet for its equity share. It can change over time.
Grandfathering Explained: Units Bought Before 1 February 2018
Long-term gains on listed equity were made taxable from 1 April 2018. This matters most for old investors in mutual fund taxation. To be fair to them, the law does not tax the gain made up to 31 January 2018.
For equity shares, equity-oriented fund units and business trust units bought before 1 February 2018, the Act sets the cost as (Section 90(7)):
Cost = the higher of (a) your actual cost, and (b) the lower of (i) the value on 31 January 2018 and (ii) your sale value.
The value on 31 January 2018 is the highest quoted price for listed shares, or the NAV for fund units.
| Actual cost | Value on 31 Jan 2018 | Sale price | Cost used | Gain taxed |
|---|---|---|---|---|
| ₹100 | ₹160 | ₹250 | ₹160 | ₹90 (not ₹150) |
| ₹100 | ₹160 | ₹140 | ₹140 | ₹0, no loss is created |
| ₹180 | ₹160 | ₹250 | ₹180 | ₹70 |
Grandfathering does not apply to debt funds, and it does not apply to assets bought on or after 1 February 2018. Please keep proof of the 31 January 2018 value, and ask your CA to check your working.
Switching, Redemption and SIP: What Is a Sale?
In mutual fund taxation, a redemption is a sale. A switch from one fund to another is a sale of the first and a purchase of the second. A stop of the SIP, by itself, is not a sale.
With a SIP, each instalment has its own cost and its own date. When you redeem part of your holding, FIFO decides which units are sold. So the order of your purchases, and not your choice, decides the tax.
Unlisted Shares: One Paragraph You Should Know
Unlisted shares are outside normal mutual fund taxation, but many investors hold both. They are long-term only after 24 months. A long-term gain is taxed at 12.5% without indexation (Section 197), and a short-term gain is added to your income and taxed at your slab rate. The ₹1.25 lakh limit does not apply, because it is only for listed equity and equity funds (Section 198). For unquoted shares, the sale value can also be taken as the fair market value if your sale price is lower (Section 79). Please ask your CA before you sell unlisted shares.
Capital Losses: Set-Off and Carry Forward
- A short-term loss can be set off against any capital gain, short-term or long-term (Section 108(2)).
- A long-term loss can be set off only against long-term gains.
- A loss that is not set off can be carried forward for eight tax years (Section 111(2)).
- The return must be filed on time, or the loss cannot be carried forward (Section 121).
A simple example. An investor has a short-term loss of ₹50,000 and long-term gains of ₹1.8 lakh on listed equity. The loss is set off against the long-term gain, leaving ₹1.3 lakh. After the ₹1.25 lakh limit, ₹5,000 is taxable at 12.5%, which is ₹625, plus cess. Please ask your CA how to work out your own figures.
Which ITR Form for Capital Gains?
- ITR-1 (SAHAJ): only if your capital gains are long-term gains under Section 198 of up to ₹1,25,000, you have no loss to carry forward, and no other bar applies (Rule 164(2), (3)).
- ITR-2: for an individual or HUF with capital gains and no business or professional income (Rule 164(4)).
- ITR-3: if you also have business or professional income.
For the full form choice, read our guide on ITR 4 or ITR 3. For how your total tax is worked out, read our guide on old vs new tax regime 2026-27.
Common Mistakes and Myths in Mutual Fund Taxation
| What people believe | What the Act says |
|---|---|
| “A SIP is one investment with one date.” | Each instalment has its own date, and FIFO applies. |
| “A switch is not a sale.” | It is a sale and a purchase (Section 2(109)). |
| “Old units are taxed on the old cost.” | Units bought before 1 Feb 2018 get a grandfathered cost (Section 90(7)). |
| “Debt funds still get long-term tax.” | A specified mutual fund bought on or after 1 April 2023 is taxed at slab rates (Section 76). |
| “The ₹1.25 lakh limit is for each fund.” | It is for all listed equity and equity fund gains in the year (Section 198). |
| “The ₹1.25 lakh limit covers short-term gains too.” | It applies only to long-term gains. |
| “A long-term loss can reduce a short-term gain.” | It can be set off only against long-term gains (Section 108(2)). |
| “I can carry my loss forward even if I file late.” | The return must be filed on time (Section 121). |
Already Made a Mistake? Steps You Can Take
- Stay calm. Many filing issues can be corrected.
- Collect your capital gains statements, contract notes and your annual information statement.
- Meet your CA and ask whether a revised return (Section 263(5)) or an updated return (Section 263(6)) is suitable.
- Do not file a new return on guesswork. Time limits and extra tax can apply, so act early.
Before You Redeem: A Quick Checklist
- What type of fund is it: equity-oriented, specified mutual fund, or another type?
- How long has each batch of units been held?
- Were any units bought before 1 February 2018?
- Do I have other gains or losses this year?
- Is the sale a redemption, a switch, or both?
- Which ITR form will I file?
Official Sources to Read
- Sections 2(101), 76, 90, 196 to 198, 108, 111 and 121 of the Income-tax Act 2025, on the Income Tax Department website.
- Form rules in Rule 164 of the Income-tax Rules 2026, and the forms on the e-filing portal.
- Fund categories and NAV history on the AMFI website, and the rules for mutual funds on the SEBI website.
This is general education. For your own case, please talk to a competent CA or tax consultant before you decide.
How SR Wealth Can Help
We are an AMFI Registered Mutual Fund & SIF Distributor and an APMI Registered PMS Distributor. We do not give tax advice. Please keep your CA or tax consultant for all tax decisions and filing.
Many investors do not know which fund types they hold, what their units cost, or how mutual fund taxation applies to each. We help you understand your portfolio and plan your investments around your goals and your comfort with risk. We can:
- Help you collect and read your statements, so your records are ready when your CA asks
- Explain the fund categories you hold, and how SIPs, switches and redemptions work
- Set up mutual fund SIPs for long-term goals
- Explain SIF, PMS and AIF solutions, where they are suitable for you
- Arrange insurance solutions that protect family and business risk
- Connect you with a competent CA or tax consultant if you need one for your salary tax, return or notice
You can read more in our guides on SIF taxation in India and Ex-Top 100 SIF vs PMS: the tax difference.
Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing.
Rules and rates change from time to time. Please confirm with your tax consultant / CA. Last verified on 3 November 2026.
Frequently Asked Questions
1. What is mutual fund taxation in simple words?
When you sell mutual fund units at a profit, the profit is a capital gain. It is short-term or long-term depending on the fund type and how long you held the units, and it is taxed at different rates.
2. What are the capital gains tax rates on equity mutual funds for Tax Year 2026-27?
Short-term gains are taxed at 20% (Section 196). Long-term gains are taxed at 12.5% on the part above ₹1,25,000 in a year (Section 198). Surcharge and cess are extra, and rates can change with future Finance Acts.
3. How is a SIP taxed?
Each instalment is a separate purchase with its own date. When you redeem, FIFO decides which units are sold first (Section 67(7)(c)).
4. Is switching between funds taxable?
Yes. A switch is treated as a sale of the first fund and a purchase of the second, so gains can arise (Section 2(109)).
5. How does grandfathering work?
For equity shares and equity fund units bought before 1 February 2018, your cost is the higher of your actual cost and the lower of the 31 January 2018 value and your sale value (Section 90(7)).
6. How are debt funds and hybrid funds taxed?
A specified mutual fund (more than 65% in debt and money market) bought on or after 1 April 2023 is taxed at slab rates (Section 76). A hybrid fund depends on its mix. Please check the factsheet and ask your CA.
7. Can I use capital gains from shares or mutual funds to buy a house?
In some cases, yes. Section 86 (earlier 54F) can give an exemption if the net sale value is invested in a house, with conditions. We explain it in detail in our next article. Please talk to your CA before you plan.
8. How are unlisted shares taxed?
Long-term after 24 months, taxed at 12.5% without indexation. Short-term gains are taxed at slab rates. The ₹1.25 lakh limit does not apply.
9. Can I set off capital losses?
A short-term loss can be set off against any capital gain. A long-term loss can be set off only against long-term gains. Unused losses carry forward for eight tax years if you file your return on time.
10. Which ITR form do I file for mutual fund gains?
ITR-1 only if your gains are long-term, under Section 198, up to ₹1.25 lakh, with no loss to carry forward. Otherwise ITR-2, or ITR-3 if you also have business income.
This article is also available on Medium for wider reading: https://medium.com/@shreeradha.services/mutual-fund-taxation-4-costly-mistakes-investors-make-tax-year-2026-27-33d33b1549b7
Plan Your Investments With Shree Radha Financial Services
Connect with Shree Radha Financial Services for a personalized discussion on investments and financial planning.
📞 Call/WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services, Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN05763
Investing since 2012 | BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN05763). All content is strictly for educational purposes only and does not constitute individualized investment advice. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing. Tax treatment is based on current laws and subject to change. Please consult a qualified tax professional before investing.