Introduction:
Gratuity calculation looks hard, but it is a short sum. You need three things: your last salary (basic + DA), your years of service and the rule that applies to your job. This guide shows the gratuity calculation in easy steps. It follows two cousins and six other people from six cities, and each one makes a common mistake.
Reading time: about 10 minutes | Last verified: 5 November 2026
Quick answer: the gratuity calculation in short
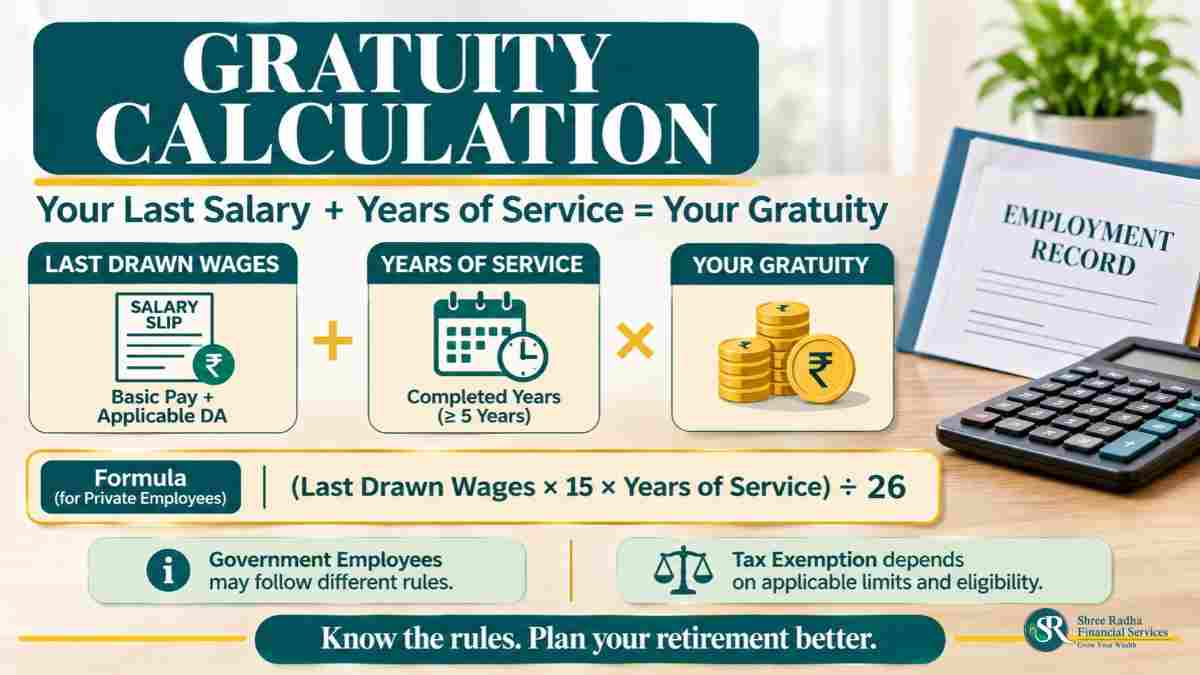
Private-sector gratuity = (last salary (basic + DA) ÷ 26) × 15 × completed years of service. Government gratuity = ¼ of emoluments × completed six-month periods. The tax-free part is the lower of what you received and the limits in the law. Read on for the steps and examples.
Private-sector gratuity = (last salary (basic + DA) ÷ 26) × 15 × completed years of service. Government gratuity = ¼ of emoluments × completed six-month periods. The tax-free part is the lower of what you received and the limits in the law. Read on for the steps and examples.
Who this guide is for: any employee who will leave a job or retire in the next few years, and anyone who wants to check the gratuity calculation on their own pay slip.
Four words to know for the gratuity calculation
Basic + DA: your basic pay plus dearness allowance. This is the salary used for gratuity.
Completed year: a year of service you have finished. In private jobs, a part-year of more than six months counts as a full year.
Emoluments: the pay a government rule counts for gratuity (basic pay and certain allowances).
Nominee: the person you name to receive your gratuity if you die.
Basic + DA: your basic pay plus dearness allowance. This is the salary used for gratuity.
Completed year: a year of service you have finished. In private jobs, a part-year of more than six months counts as a full year.
Emoluments: the pay a government rule counts for gratuity (basic pay and certain allowances).
Nominee: the person you name to receive your gratuity if you die.
“Many people say, ‘My company will give gratuity, so I am fine.’ But very few ask how the amount is worked out, or how much of it is tax-free. A few minutes with the rules can save a lot of disappointment on the last day of the job.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
Gratuity Calculation: Two Cousins, One Family Function
It is a wedding in Surat. Mahesh has come from Pune. He works for a private company and has decided to resign after 9 years and 7 months. Jignesh, his cousin, works in a central government office in Surat. He will retire in two years.
Over tea, Mahesh says, “My HR says I will get gratuity. I have no idea how much. How is the gratuity calculation done?” Jignesh smiles. “My gratuity is calculated in a different way. I think our rules are not the same.”
They make a plan. Mahesh will read the rules for his gratuity calculation and ask his company HR. Jignesh will read his rules and ask his office accounts section. They will compare notes next week.
Gratuity Eligibility: Who Gets It and When
Mahesh starts the gratuity calculation with the first question: “Do I even qualify?” He reads Chapter V of the Code on Social Security, 2020, on the India Code website. It replaced the old Payment of Gratuity Act, 1972 and came into force on 21 November 2025.
Step 1: Check you have 5 years of continuous service.
Step 2: Check why the job is ending: retirement, resignation, superannuation, death, disablement or end of a fixed-term contract.
Step 3: For death, disablement or the end of a fixed-term contract, the five years are not needed.
Step 2: Check why the job is ending: retirement, resignation, superannuation, death, disablement or end of a fixed-term contract.
Step 3: For death, disablement or the end of a fixed-term contract, the five years are not needed.
Law reference: Code on Social Security, 2020, Section 53(1).
“Continuous service” does not mean you never took a day off. Leave, sickness and lay-offs do not break it. A year also counts if you actually worked at least 240 days in the 12 months before (190 days for mines and for workplaces that run fewer than six days a week). Many people repeat “4 years and 240 days is enough”. The Code says five years. Whether your last part-year counts is a question for your HR or your CA. The Ministry of Labour and Employment publishes the notices on the Code.
Law reference: Code on Social Security, 2020, Sections 53 and 54.
Who is covered by the gratuity calculation rules?
| Your employer | Which gratuity rule applies |
|---|---|
| Factory, mine, oilfield, plantation, port or railway company | The Code on Social Security, 2020 (Chapter V) |
| Shop or establishment with 10 or more employees on any day in the last 12 months | The Code on Social Security, 2020 (Chapter V) |
| Central Government (civil) | CCS (Pension) Rules, 2021 |
| PSU, bank, port trust, RBI, autonomous body, university or State Government | Their own rules. The Central Government has said the CCS rules do not apply to them (DoPPW memorandum, 24 October 2025) |
| Other employers | Their own terms. The tax rules still apply (see the tax section) |
Gratuity Calculation for Private Employees: The 15/26 Formula
Mahesh goes to his HR to check the gratuity calculation. HR shows him the formula on one page. He reads it twice and understands that it is only three steps.
Step 1: Take your last drawn wages (basic + DA).
Step 2: Divide by 26, then multiply by 15. This is your gratuity for one year.
Step 3: Multiply by your completed years. A part-year of more than six months counts as one more year.
Step 2: Divide by 26, then multiply by 15. This is your gratuity for one year.
Step 3: Multiply by your completed years. A part-year of more than six months counts as one more year.
Law reference: Code on Social Security, 2020, Section 53(2) and Explanation 3.
Mahesh’s gratuity calculation. His last basic + DA is ₹80,000 a month. His service is 9 years and 7 months. The part of 7 months is more than six months, so it counts as 10 years.
| Step | Working | Result |
|---|---|---|
| One day’s rate for a year | ₹80,000 ÷ 26 × 15 | ₹46,154 (rounded) |
| Years counted | 9 years 7 months, rounded up | 10 years |
| Gratuity | ₹80,000 ÷ 26 × 15 × 10 | ₹4,61,538 (rounded) |
Rounding works both ways. A service of 9 years and 6 months stays at 9 years, because six months is not “in excess of six months”.
Wages in the gratuity calculation: what counts?
| Counted | Not counted |
|---|---|
| Basic pay, dearness allowance, retaining allowance | House rent allowance, conveyance, overtime, commission, bonus (if outside the pay terms), employer PF contribution |
There is one more rule in the gratuity calculation. If the items that are left out add up to more than half of your total pay, the extra is added back to your wages. Example: total pay ₹1,00,000, of which basic + DA is ₹40,000 and the other allowances are ₹60,000. The left-out items are 60%, which is ₹10,000 above the half. So gratuity wages become ₹50,000. Ask your HR how they apply this to your older service.
Law reference: Code on Social Security, 2020, Section 2(88).
Nagpur: Sandeep used his CTC in the gratuity calculation
Sandeep works for a pump maker in Nagpur. His CTC is ₹12 lakh a year. He thinks, “Gratuity is CTC ÷ 26 × 15 × years.”
The mistake
He used the whole CTC. Gratuity is not based on CTC.
He used the whole CTC. Gratuity is not based on CTC.
The correction
Sandeep asks his HR for his pay structure. Only basic + DA (and the 50% add-back rule) forms the wages. His basic + DA is far lower than his CTC, so his real gratuity is much smaller than he hoped. He now plans his exit budget with the correct number.
Sandeep asks his HR for his pay structure. Only basic + DA (and the 50% add-back rule) forms the wages. His basic + DA is far lower than his CTC, so his real gratuity is much smaller than he hoped. He now plans his exit budget with the correct number.
Gratuity Calculation for Government Employees: The Quarter Rule
Jignesh visits his office accounts section. They show him Rule 45 of the CCS (Pension) Rules, 2021. His gratuity calculation is different from Mahesh’s.
Step 1: Take your emoluments (basic pay + DA on the date of retirement).
Step 2: Count completed six-month periods of qualifying service.
Step 3: Retirement gratuity = ¼ × emoluments × number of six-month periods, up to 16½ times your emoluments.
Step 2: Count completed six-month periods of qualifying service.
Step 3: Retirement gratuity = ¼ × emoluments × number of six-month periods, up to 16½ times your emoluments.
Law reference: CCS (Pension) Rules, 2021, Rule 45(1)(a) and (6).
Jignesh’s gratuity calculation. Assume he retires with emoluments of ₹1,20,000 after 30 years of service. That is 60 six-month periods.
| Step | Working | Result |
|---|---|---|
| Retirement gratuity | ¼ × ₹1,20,000 × 60 | ₹18,00,000 |
| Cap of 16½ times | 16.5 × ₹1,20,000 | ₹19,80,000 |
| Amount payable | The lower figure (and within the overall limit) | ₹18,00,000 |
Two small rules help the gratuity calculation. A fraction of three months or more counts as a completed six-month period. A service of 4 years and 9 months or more (but under 5 years) is treated as 5 years.
Law reference: CCS (Pension) Rules, 2021, Rule 45(4) and (5).
The overall limit in Rule 45 was ₹20 lakh. The Department of Pension and Pensioners’ Welfare raised it to ₹25 lakh for central civil employees, as its office memorandum of 24 October 2025 records. If the employee dies in service, the family gets death gratuity instead:
| Qualifying service | Death gratuity |
|---|---|
| Less than 1 year | 2 times emoluments |
| 1 year to less than 5 years | 6 times emoluments |
| 5 years to less than 11 years | 12 times emoluments |
| 11 years to less than 20 years | 20 times emoluments |
| 20 years or more | Half of emoluments for every six-month period, up to 33 times |
Lucknow: Anita thought the ₹25 lakh limit was for everyone
Anita works in a State Government undertaking in Lucknow. She reads on social media that “government gratuity limit is ₹25 lakh” and thinks it applies to her.
The mistake
The ₹25 lakh limit is for central civil employees under the CCS Rules. The Central Government has said these rules do not apply to State Governments, PSUs, banks and similar bodies.
The ₹25 lakh limit is for central civil employees under the CCS Rules. The Central Government has said these rules do not apply to State Governments, PSUs, banks and similar bodies.
The correction
Anita asks her own department which rules govern her gratuity. She now plans her retirement with the limit that really applies to her.
Anita asks her own department which rules govern her gratuity. She now plans her retirement with the limit that really applies to her.
Gratuity Limit, Payment Time and Nomination: Your Rights
Mahesh also learns three more things from the Code. They matter as much as the gratuity calculation itself.
| Topic | What the Code says (Sections 53 to 56) |
|---|---|
| Maximum amount | The Central Government sets it by notification. The limit most employers follow today is ₹20 lakh, so confirm the current figure with your HR. |
| Payment time | The employer must pay within 30 days from the date it becomes payable. If late, simple interest is payable at a rate notified by the Central Government. |
| Employer’s duty | The employer must work out the amount and send you a written notice, even if you have not applied. |
| Nomination | Every employee with one year of service must nominate. If you have a family, the nominee must be a family member. If you had no family when you nominated and later get one, the old nomination becomes invalid and you must make a fresh one. |
| Better terms | If your contract offers better terms than the Code, you get the better terms. |
| Forfeiture | Gratuity can be cut only for damage or loss to the employer’s property (to that extent), or wholly or partly for riotous conduct, violence, or an offence involving moral turpitude committed in the course of employment. |
Kolkata: Debashis forgot to change his nomination
Debashis works for a jute mill in Kolkata. He made a nomination in favour of a friend when he was single, and thinks, “That is final.”
The mistake
He got married and never updated it. If you had no family when you nominated and later get one, the old nomination becomes invalid.
He got married and never updated it. If you had no family when you nominated and later get one, the old nomination becomes invalid.
The correction
Debashis asks his HR for the nomination form and names his wife. He keeps a copy. He also reads that the nominee can be changed any time by written notice.
Debashis asks his HR for the nomination form and names his wife. He keeps a copy. He also reads that the nominee can be changed any time by written notice.
Jaipur: Ritu was told her gratuity would be cut for a short notice period
Ritu works for a textile unit in Jaipur. She resigns without serving the full notice. Her manager says, “Your gratuity will be cut for the notice shortfall.”
The mistake
She believed it. Short notice is not one of the grounds the Code lists for cutting gratuity.
She believed it. Short notice is not one of the grounds the Code lists for cutting gratuity.
The correction
Ritu reads Section 53(6) and asks her HR in writing for the legal ground. The Code allows a cut only for damage or loss to property (to that extent) and for violence or serious misconduct. She keeps the reply for her records and asks her CA if anything is unclear.
Ritu reads Section 53(6) and asks her HR in writing for the legal ground. The Code allows a cut only for damage or loss to property (to that extent) and for violence or serious misconduct. She keeps the reply for her records and asks her CA if anything is unclear.
Indore: Faiz is on a fixed-term contract
Faiz works for a packaging company in Indore on a 2-year fixed-term contract. He thinks, “No gratuity, because I will not complete five years.”
The mistake
He assumed the five-year rule applies to everyone.
He assumed the five-year rule applies to everyone.
The correction
Faiz reads Section 53(1). For a fixed-term contract, five years are not needed. The gratuity is worked out pro rata for the period served. He asks his HR what minimum service his contract needs.
Faiz reads Section 53(1). For a fixed-term contract, five years are not needed. The gratuity is worked out pro rata for the period served. He asks his HR what minimum service his contract needs.
Gratuity Tax After the Gratuity Calculation: What Is Tax-Free
Mahesh’s company decides to pay him ₹6,00,000, which is more than the formula amount. He is happy, until his CA asks a simple question: “How much of this is tax-free?”
Tax-free part = the lowest of: (a) the gratuity you received, (b) the formula amount, (c) the limit notified by the government.
Taxable part = the rest. It is added to your salary income.
Taxable part = the rest. It is added to your salary income.
| Who you are | What is tax-free | Law reference (Income-tax Act 2025) |
|---|---|---|
| Government employee (CCS Rules, All-India Services, State civil services and similar schemes) | The entire death-cum-retirement gratuity | Section 19(1) Table, Sl. 3 and Section 19(2)(g) (earlier Section 10(10)(i)) |
| Employee covered by the gratuity law | The amount received, but only up to the amount worked out as per the law’s formula and limit | Section 19(1) Table, Sl. 5 (earlier Section 10(10)(ii)) |
| Any other employee (not covered by the gratuity law) | The lowest of the actual amount, the notified limit, and half a month’s salary for each completed year (average of the last 10 months) | Section 19(1) Table, Sl. 6 (earlier Section 10(10)(iii)) |
| Family of a deceased employee | Gratuity received on death | Schedule III, Sl. 38 |
Mahesh’s tax example after the gratuity calculation. The formula amount is ₹4,61,538. His company pays ₹6,00,000.
| Step | Amount |
|---|---|
| Gratuity received | ₹6,00,000 |
| Formula amount (the limit is higher, so it does not bind) | ₹4,61,538 |
| Tax-free part | ₹4,61,538 |
| Taxable part (added to salary income) | ₹1,38,462 |
If the company had paid exactly ₹4,61,538, the whole gratuity would have been tax-free.
An employee not covered by the gratuity law. Rajesh works for a small firm for 14 years. His average salary over the last 10 months was ₹60,000. He received ₹4,50,000.
| Step | Working | Result |
|---|---|---|
| Half a month’s salary for each year | ₹60,000 ÷ 2 × 14 | ₹4,20,000 |
| Actual gratuity received | ₹4,50,000 | |
| Tax-free part (lowest; the limit does not bind) | ₹4,20,000 | |
| Taxable part | ₹4,50,000 − ₹4,20,000 | ₹30,000 |
Law reference: Income-tax Act 2025, Section 19(1) Table Sl. 6 and Section 19(2)(b): salary includes DA if the terms of employment say so.
Two more points. First, if you get gratuity from more than one employer, the tax-free limit is shared across all of them, and amounts already exempted in earlier years are deducted (Section 19(2)(a)). Second, the gratuity exemption is still available in the new regime. Only the professional tax deduction in the same Table (Sl. 1) is not allowed there (Section 202(2)).
Compare the two regimes with numbers in our old vs new tax regime guide. Rules and rates change from time to time. Please confirm with your tax consultant / CA. Last verified on 5 November 2026 against the Income-tax Act 2025. The Income-tax Act text we checked still names the Payment of Gratuity Act, 1972 in Sl. 5. Your CA can confirm how it is applied to gratuity now paid under the Code.
Chennai: Lakshmi thought all gratuity is tax-free after her gratuity calculation
Lakshmi works for a software firm in Chennai. Her company pays her a generous gratuity. She thinks, “Gratuity is always tax-free.”
The mistake
Only the part up to the law’s limits is tax-free. The rest is taxed as salary.
Only the part up to the law’s limits is tax-free. The rest is taxed as salary.
The correction
Lakshmi asks her CA to compare the amount she received with the formula amount. The extra part is added to her income. She now keeps this in mind before she plans how to use the money.
Lakshmi asks her CA to compare the amount she received with the formula amount. The extra part is added to her income. She now keeps this in mind before she plans how to use the money.
Gratuity Calculation Mistakes: Myth vs Fact
Most mistakes happen in the gratuity calculation itself, or in what people assume about it.
| Myth | Fact |
|---|---|
| Gratuity is based on CTC | It is based on wages: basic + DA (plus the 50% add-back rule) |
| 7 years 7 months means 7 years | A part-year of more than six months counts as a full year (private-sector formula) |
| Five years are needed in every case | Not for death, disablement or the end of a fixed-term contract |
| The ₹25 lakh limit is for all government bodies | It is for central civil employees under the CCS Rules |
| A short notice period can cancel gratuity | Not a ground for cutting gratuity in the Code |
| Gratuity is always fully tax-free | Only up to the limits in the tax law |
| A nomination made years ago is always valid | It becomes invalid if you had no family at the time and later get one |
| The employer can pay whenever it likes | Payment is due within 30 days, with interest if late |
Gratuity Calculation Checklist: What to Ask Your HR
Mahesh and Jignesh meet again after a week. They write down what they learned. Here is their list.
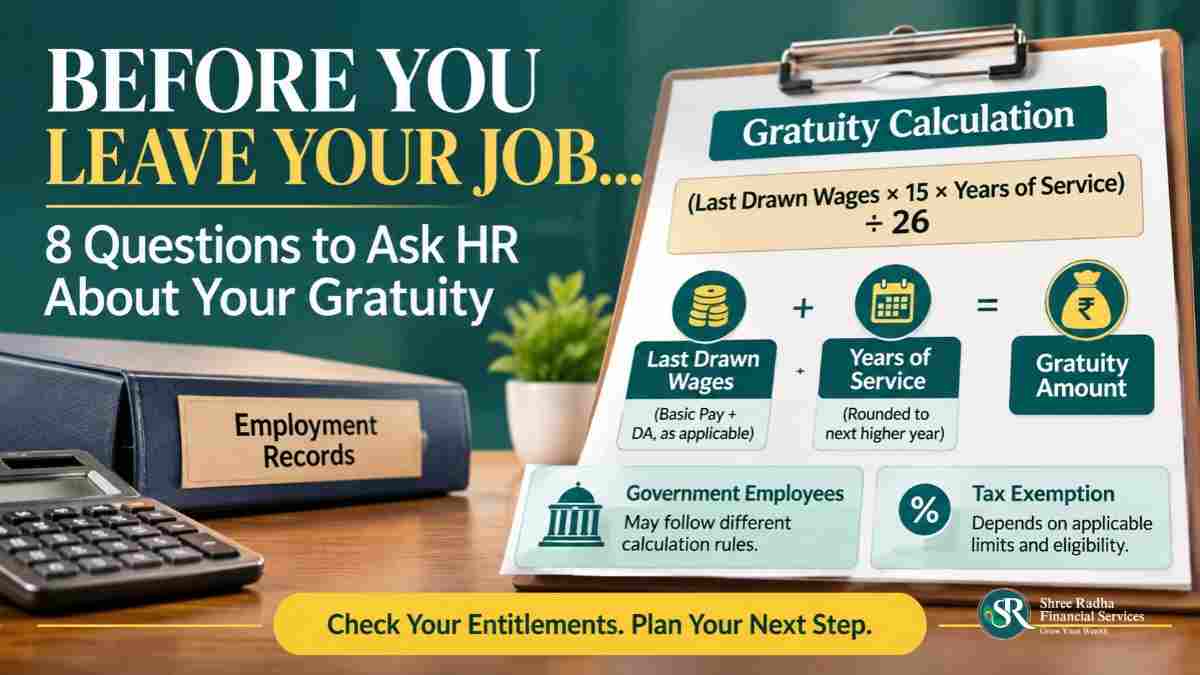
- Ask which rule covers you: the Code, the CCS Rules or your own scheme.
- Ask for the gratuity calculation in writing, with your last wages (basic + DA) and years counted.
- Check the years: rounding, continuous service and any break.
- Check your nomination and update it after any change in family.
- Note the 30-day payment limit and the date you left.
- Ask your CA about the tax-free part before the money arrives.
- Keep every letter from your employer about gratuity.
Once the gratuity calculation is done, plan the rest of your retirement. Read our retirement schemes guide and our NPS withdrawal rules guide. For a larger picture, see the retirement planning guide for Surat, the retirement SIP and SWP guide and is ₹2 crore enough to retire.
Gratuity Calculation: Frequently Asked Questions
What is the gratuity calculation formula for private employees?
Gratuity = (last drawn wages (basic + DA) ÷ 26) × 15 × completed years of service. A part-year of more than six months counts as one more year.
Is gratuity calculated on CTC or basic salary?
It is calculated on wages, which means basic pay, DA and any retaining allowance. If the excluded items exceed half of your total pay, the extra is added to wages.
Gratuity kab milti hai?
Gratuity is payable on retirement, resignation, superannuation, death, disablement, or the end of a fixed-term contract, usually after five years of continuous service. The employer must pay within 30 days from the date it becomes payable.
Does the gratuity calculation need five years in every case?
No. Five years of continuous service are not needed on death, disablement or the end of a fixed-term contract.
How is gratuity calculated for central government employees?
Retirement gratuity = ¼ × emoluments × completed six-month periods of qualifying service, up to 16½ times emoluments and the overall limit (₹25 lakh for central civil employees as per the DoPPW memorandum).
Is gratuity fully tax-free?
Not always. Government death-cum-retirement gratuity is fully exempt. For others, only the part up to the formula and the notified limit is exempt. The rest is taxed as salary.
Can the employer cut my gratuity for a short notice period?
The Code lists only specific grounds: damage or loss to property, violence or riotous conduct, and offences involving moral turpitude. Short notice is not listed.
What if the employer delays gratuity?
The employer must pay within 30 days from the date it becomes payable. If it is late, simple interest is payable at a rate notified by the Central Government.
Do I need to update my nomination after marriage?
If you had no family when you nominated and later get one, the old nomination becomes invalid and you must make a fresh one in favour of family members.
This article is also available on Medium for wider reading:https://medium.com/@shreeradha.services/gratuity-calculation-how-much-will-you-get-and-how-much-is-tax-free-ef68df2f26f8
Want a Clear Picture of Your Gratuity Calculation?
Connect with Shree Radha Financial Services for a personalized discussion on the investment side of your retirement plan. For your own gratuity, pension or tax case, please ask your employer, your office or your CA.
📞 Call/WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services, Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN05763
Investing since 2012 | BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN05763). All content is strictly for educational purposes only and does not constitute individualized investment advice. We do not advise on individual gratuity, pension or tax cases. Please confirm your own case with your employer, your office accounts section and a qualified tax professional. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing. Rules and rates change from time to time. Tax treatment is based on the Income-tax Act 2025 as verified on 5 November 2026 and is subject to change. The characters in this article are fictional.