NPS vs PPF is a question almost every Indian saver asks, and EPF turns it into a three-way choice. The three schemes look alike because all of them build a retirement fund. They are not alike. They differ on who can join, who sets the growth and how you can take the money out. Here is the short version of NPS vs PPF: PPF has a government-set rate, NPS depends on the fund, and EPF comes through your employer.
This guide explains NPS vs PPF vs EPF in easy words, in the same order for each scheme: deposit, growth, withdrawal. It uses the Income-tax Act 2025 (Tax Year 2026-27) and notes the earlier section numbers. It does not tell you which scheme to pick. It shows what each one does, so you can ask the right questions to your employer or CA.
“People ask me, ‘NPS vs PPF, which is better?’ That is the wrong first question. The right first question is: what do I already have, and what can I add? An employee already has EPF. A business owner has none. The answer starts from your situation, not from the scheme.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
NPS vs PPF vs EPF: The Basic Difference
Retirement fund = your deposits + employer deposits (if any) + growth
In NPS vs PPF vs EPF, the schemes differ on who can deposit, who sets the growth and how you can take the money out.
In NPS vs PPF vs EPF, the schemes differ on who can deposit, who sets the growth and how you can take the money out.
| EPF | PPF | NPS | |
|---|---|---|---|
| Who can join | Employees of establishments covered by the EPF Scheme 2026 | An individual, with one account, plus one for each minor as guardian (PPF Scheme 2019, Para 3) | Individuals; employers can offer it too |
| Who sets the growth | The Central Government sets the interest rate each year (EPF Scheme 2026, Para 42) | The government sets the rate every quarter (small savings rates) | Not fixed. The final amount depends on your deposits and the fund value |
| Does an employer deposit? | Yes, 12% of salary (basic + DA), or 10% for notified classes | No | Possible, if your employer offers it |
In NPS vs PPF, the biggest gap is the growth: PPF has a government-set rate, and NPS does not. For a wider comparison that also includes SCSS and annuity, read our retirement schemes guide.
NPS vs PPF vs EPF: How EPF Works
EPF deposit = employee 12% of salary (basic + DA) + employer 12% of salary (basic + DA)
Calculated on salary up to the notified wage ceiling. Part of the employer share goes to EPS, the pension scheme.
Calculated on salary up to the notified wage ceiling. Part of the employer share goes to EPS, the pension scheme.
In NPS vs PPF vs EPF, EPF is the only scheme where the employer must deposit. EPF is run by the Employees’ Provident Fund Organisation. Here is how it works under the EPF Scheme 2026.
| Stage | Rule (EPF Scheme 2026) |
|---|---|
| Deposit | Employee and employer pay equal amounts (Para 18). You can also add voluntary contributions on salary above the wage ceiling (Para 19). The employer does not have to match them. |
| Interest | The Central Government sets the rate with the Central Board, and it is credited on the monthly running balance (Para 42). Declared rates: 8.50% for 2019-20 and 2020-21, 8.10% for 2021-22, 8.15% for 2022-23 (EPFO table). |
| Partial withdrawal | After 12 months of membership. 25% of total contributions and interest must stay as Minimum Balance. Education up to 10 times, marriage 5 times, housing 5 times and special cases 2 times a year (Para 46). |
| Full withdrawal | On retirement after age 55 and in other listed cases (Para 49). |
Story 1: Rohit in Hyderabad thought the PPF rate was fixed for life
Rohit works for a pharma company in Hyderabad. He opened a PPF account and thinks, “The rate printed in the passbook will stay the same for 15 years.”
The mistake: He treated a government-set rate as a fixed promise.
The correction: Rohit reads the PPF Scheme and the latest small savings notice. He learns that interest is paid at the rate applicable to the Scheme from time to time, and the government reviews small savings rates every quarter. He now plans his years of deposits without assuming one fixed rate, whether he chooses NPS vs PPF or both.
NPS vs PPF vs EPF: How PPF Works
PPF deposit = any amount from ₹500 to ₹1.5 lakh in a year, in multiples of ₹50
The limit covers your own account and any minor’s account you open as guardian.
The limit covers your own account and any minor’s account you open as guardian.
In NPS vs PPF, PPF is the simpler scheme. It is a small savings scheme made under the Government Savings Promotion Act, 1873. You can read about small savings accounts on the India Post website. Here is how it works under the Public Provident Fund Scheme, 2019.
| Stage | Rule (PPF Scheme 2019) |
|---|---|
| Deposit | Minimum ₹500 a year, maximum ₹1.5 lakh (Para 4). A missed year makes the account discontinued, and it can be revived with a ₹50 fee plus the minimum for each missed year (Para 6). |
| Interest | Credited at the end of each year. Interest is calculated on the lowest balance between the close of the 5th day and the end of the month (Para 7). The rate is set by the government every quarter, and rates for Oct-Dec 2026 stayed unchanged from the previous quarter (Finance Ministry memorandum, 30 Sep 2026). |
| Loan | From the 2nd to the 5th year, up to 25% of the balance at the end of the second preceding year. Repay within 36 months at 1% interest. If you repay late, the rate is 6% (Paras 8-9). |
| Partial withdrawal | After 5 years from the end of the year of opening. Up to 50% of the balance at the end of the fourth preceding year or the preceding year, whichever is lower. Once a year (Para 10). |
| Maturity | 15 years. You can close the account, or extend in 5-year blocks with or without deposits. During an extended block, withdrawals are capped at 60% of the balance at the start of the block (Paras 11-12). |
| Early closure | After 5 years for a life-threatening illness, higher education or a change in residency status, with interest cut by 1% (Para 13). |
| Court attachment | The balance is protected from attachment for debts (Para 15). |
PPF example. Deposit ₹1.5 lakh every year for 15 years. You put in ₹22.5 lakh. At an assumed rate of 7% a year, the balance would be about ₹40.3 lakh. The 7% is assumed for learning only. It is not the current rate and not a forecast. In NPS vs PPF terms, this is the fixed-limit side: you cannot deposit more than ₹1.5 lakh a year.
We explain loans, extension and tax in detail in our PPF rules guide.
NPS vs PPF vs EPF: How NPS Works
NPS corpus = your deposits + employer deposits + growth of the fund
The corpus is not fixed. At exit, a minimum part must buy an annuity.
The corpus is not fixed. At exit, a minimum part must buy an annuity.
In NPS vs PPF, NPS is the scheme with the annuity rule at exit. NPS is regulated by PFRDA. Withdrawal rules come from the PFRDA Exits and Withdrawals Regulations, 2015, as last amended on 16 December 2025.
| Stage | Rule (PFRDA Exits and Withdrawals Regulations) |
|---|---|
| Deposit | Your own deposits, plus employer deposits if your employer offers NPS. Tax limits are in the tax section below. |
| Partial withdrawal | After 3 years in NPS. Up to 25% of your own contributions. Allowed for a child’s higher education or marriage, a one-time house purchase or construction (not if you already own a house, other than ancestral), medical treatment, disability expenses, or settling a loan against a lien on the account. Up to 4 times before age 60 or superannuation, with 4 years between withdrawals (Regulation 8). |
| Tier II account | You can withdraw in full or in part at any time. A Tier II Tax Saver account has its own lock-in (Regulation 8(2)). |
| Exit at retirement | Part must buy an annuity, and the rest can come as a lump sum or other payouts. The split depends on your sector and corpus, as shown below. |
NPS exit at retirement: government vs private
Lump sum = up to a fixed % of the corpus
Annuity = at least the remaining %
Annuity = at least the remaining %
| Situation | Lump sum | Annuity | Small corpus rule |
|---|---|---|---|
| Government sector, at retirement (Regulation 3(1)(a)) | Up to 60% | At least 40% | Corpus up to ₹8 lakh: 100% lump sum allowed. ₹8 lakh to ₹12 lakh: up to ₹6 lakh as lump sum, balance by systematic unit redemption for at least 6 years or annuity |
| Non-government sector, at age 60, on superannuation or after 15 years (Regulation 4(1)(a)) | Up to 80% | At least 20% | Same ₹8 lakh and ₹12 lakh rules as above |
| Voluntary exit or resignation before that | Up to 20% | At least 80% | Corpus up to ₹5 lakh: 100% lump sum allowed |
NPS exit example. Corpus ₹50 lakh at retirement. A government-sector subscriber can take up to ₹30 lakh as lump sum and must use at least ₹20 lakh for an annuity. A non-government subscriber can take up to ₹40 lakh and must use at least ₹10 lakh. If the corpus were ₹8 lakh or less, the whole amount could be taken as a lump sum. This annuity rule is the main NPS vs PPF difference at the payout stage.
For the full list of payout choices and the old pension and UPS comparison, see our NPS withdrawal rules guide.
Story 2: Meena in Jaipur expected a full lump sum from NPS
Meena works in a central government office in Jaipur. She joined under NPS and thinks, “At retirement I will get my whole NPS amount in one payment.”
The mistake: She ignored the annuity rule.
The correction: Meena reads the PFRDA exit table and asks her office accounts section. For a government-sector subscriber, the lump sum is up to 60% and at least 40% must buy an annuity. The full lump sum is allowed only if the corpus is ₹8 lakh or less. She now plans her monthly expenses around the annuity part, a point many people miss when they compare NPS vs PPF.
NPS vs PPF vs EPF: Tax Rules in the Old and New Regime
Tax at the end = amount you receive − the part the law exempts
Tax is where NPS vs PPF vs EPF differs most on paper.
Tax is where NPS vs PPF vs EPF differs most on paper.
| Scheme | Deposit | Growth | Payout |
|---|---|---|---|
| EPF | Section 123 (earlier Section 80C): old regime only, up to ₹1.5 lakh together with other eligible items. Employer deposits across PF, NPS and superannuation above ₹7.5 lakh in a tax year are taxable (Section 17(1)(h)-(i)). | Interest on your own yearly deposit above ₹2.5 lakh (₹5 lakh if the employer does not contribute) is not exempt. Schedule II Sl. 3-4 (earlier Section 10(11)/(12)). | Excluded from income after 5 years of continuous service and in other listed cases (Schedule XI Part A, para 8). TDS may apply on taxable withdrawals (Section 392(7)). |
| PPF | Section 123 (earlier Section 80C): old regime only, within the same ₹1.5 lakh limit. | Exempt under Schedule II Sl. 3 (earlier Section 10(11)), which covers provident funds notified by the Central Government. The ₹2.5 lakh limit does not arise, as the PPF deposit limit is ₹1.5 lakh. | The same Schedule II Sl. 3 exemption applies to the payout. |
| NPS | Employer deposit: Section 124(1)-(2) (earlier Section 80CCD(2)). Up to 10% of salary for private employers, 14% for government employers, and 14% for everyone in the new regime. Your own extra ₹50,000: Section 124(3) (earlier Section 80CCD(1B)), old regime only. | See the NPS withdrawal rules guide. | Up to 60% of the amount at closure is exempt (Schedule II Sl. 6). The annuity pension is income (Section 124(6)). Ask your CA how the lump sum above 60% is taxed. |
Tax example. A private employee has a salary (basic + DA) of ₹1,00,000 a month, and the employer offers NPS. In the old regime the employer deposit deduction is up to 10%, which is ₹10,000 a month or ₹1.2 lakh a year. In the new regime it is up to 14%, which is ₹14,000 a month or ₹1.68 lakh a year. Employer deposits across PF, NPS and superannuation above ₹7.5 lakh in a tax year are taxable.
In NPS vs PPF terms, the new regime keeps only the employer NPS deduction. It gives no Section 123 benefit, so EPF and PPF deposits give no deduction there. Employer NPS under Section 124(1)-(2) is allowed in both regimes.
Compare the two regimes with numbers in our old vs new tax regime guide. Rules and rates change from time to time. Please confirm with your tax consultant / CA. Last verified on 4 November 2026 against the Income-tax Act 2025.
Story 3: Arvind in Bengaluru assumed EPF interest is always tax-free
Arvind works at a software company in Bengaluru. He adds a large voluntary deposit to his EPF every year. He thinks, “EPF interest is always tax-free, so more is better.”
The mistake: He did not know the yearly limit.
The correction: Arvind asks his CA and reads Schedule II. Interest on his own yearly deposit above ₹2.5 lakh (₹5 lakh if the employer does not contribute) is not exempt. He also learns that Section 123 gives a deduction only in the old regime. He now checks his yearly deposit against the limit before he compares NPS vs PPF.
NPS vs PPF vs EPF: Which One Suits Whom?
The right mix depends on your job. The table shows what you already get and what you can add yourself. It lists features to check, not a recommendation. The NPS vs PPF choice changes with your job.
| Your situation | What you already have | What you can add and what to check |
|---|---|---|
| Private employee in an EPF-covered company | EPF: 12% + 12% of salary (basic + DA), up to the wage ceiling | Voluntary EPF (Para 19), PPF up to ₹1.5 lakh a year, and NPS if your employer offers it. Check the Section 124 limit for your regime. |
| Government employee | NPS, or the pension scheme your service rules provide | PPF up to ₹1.5 lakh a year. The extra ₹50,000 NPS deduction under Section 124(3) is old regime only. Check the exit rules for the government sector. |
| Self-employed or business owner | No employer deposit | PPF up to ₹1.5 lakh a year and NPS in your own name. EPF is for employees of covered establishments, so confirm with EPFO whether it applies to you. |
Story 4: Kiran in Surat had no EPF, so he thought PPF was his only choice
Kiran runs a small textile trading unit in Pandesara, Surat. He has no employer and no EPF. He thinks, “PPF is the only retirement scheme for me.”
The mistake: He did not know that PPF has a ₹1.5 lakh yearly limit, or that NPS is open to individuals.
The correction: Kiran reads the PPF Scheme and the PFRDA exit rules, then asks his CA how the tax rules apply to him. He now knows PPF has a yearly cap and NPS has an annuity rule at exit. He decides to compare NPS vs PPF before depositing. For retirement planning in Surat, see our retirement planning guide.
If you invest through monthly deposits, our retirement SIP and SWP guide and how much SIP is enough cover the planning side. To test a target corpus, read is ₹2 crore enough to retire.
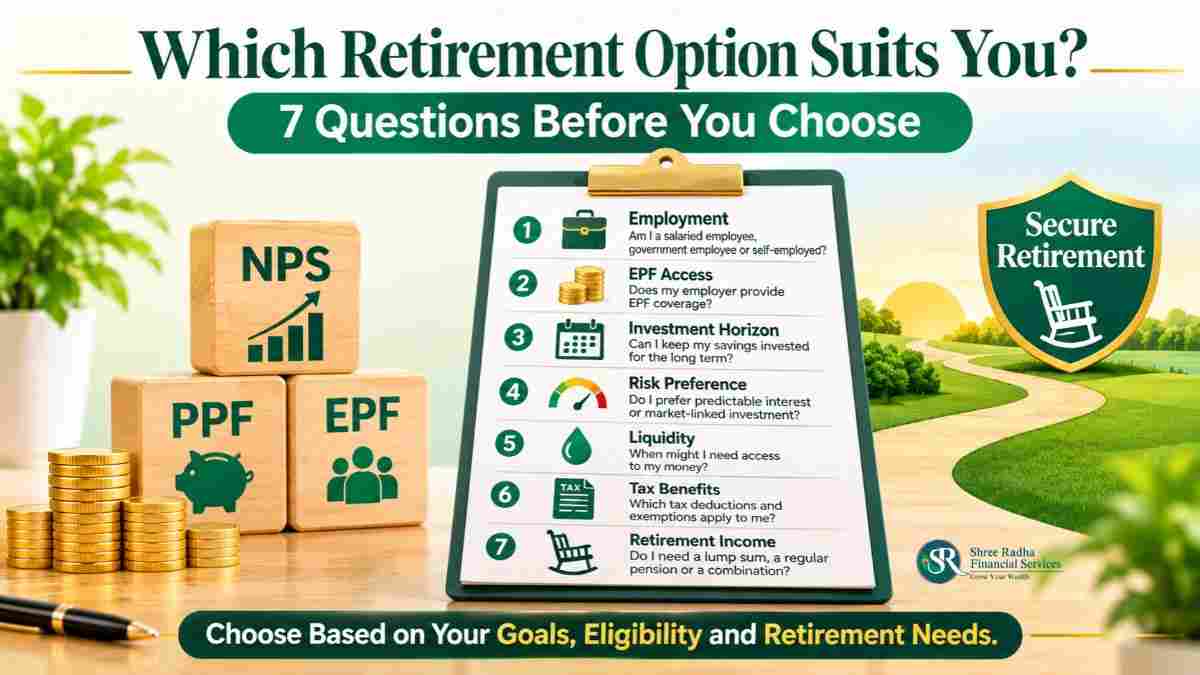
NPS vs PPF Checklist
Use this NPS vs PPF checklist before you start.
- List what you already have: EPF, NPS through your employer, or nothing.
- Check your regime: Section 123 benefits are old regime only.
- Check your yearly EPF deposit against the ₹2.5 lakh limit (₹5 lakh if the employer does not contribute).
- Know the PPF cap: ₹1.5 lakh a year, and 15 years to maturity.
- Know the NPS annuity rule for your sector before you plan your retirement income.
- Read the early-withdrawal rules of each scheme, so you know what you can reach and when.
- Ask your HR, office accounts section or CA about your own case before you decide anything.
NPS vs PPF vs EPF: Frequently Asked Questions
NPS vs PPF: which is better?
In NPS vs PPF, neither is better for everyone. PPF has a government-set rate, a ₹1.5 lakh yearly limit and a 15-year term. NPS has a market-linked corpus and an annuity rule at exit. Your job, your regime and your risk comfort decide what fits.
Can I contribute to EPF and PPF in the same year?
The PPF Scheme does not link to EPF, so both can run together. In the old regime, the Section 123 deduction has one combined limit of ₹1.5 lakh with other eligible items.
Is EPF interest fully tax-free?
No. Interest on your own yearly deposit above ₹2.5 lakh (₹5 lakh if the employer does not contribute) is not exempt. See Schedule II Sl. 3-4 of the Income-tax Act 2025.
Does the PPF interest rate change?
Yes. The government reviews small savings rates every quarter. For October to December 2026, the Finance Ministry kept the rates unchanged from the previous quarter.
Can I withdraw all my PPF money after 15 years?
Yes. After 15 years you can close the account and take the full balance, or extend it in 5-year blocks, with or without deposits.
What are the NPS partial withdrawal rules before age 60?
After 3 years, up to 25% of your own contributions, for listed purposes such as a child’s education or marriage, a one-time house purchase, or medical treatment. Up to 4 times, with 4 years between withdrawals.
Is the NPS payout fully tax-free?
No. Up to 60% of the amount at closure is exempt under Schedule II Sl. 6. The annuity pension is taxed as income. Ask your CA how any lump sum above 60% is treated.
Is the extra ₹50,000 NPS deduction available in the new regime?
No. Section 124(3) is old regime only. The employer NPS deduction under Section 124(1)-(2) is available in both regimes.
Can a self-employed person join EPF?
EPF is for employees of covered establishments. A self-employed person usually looks at NPS vs PPF instead. Confirm your case with EPFO or your CA.
This article is also available on Medium for wider reading:https://medium.com/@shreeradha.services/nps-vs-ppf-vs-epf-which-one-suits-whom-3b765c9d8620
Want a Clear Picture of Your NPS vs PPF Choices?
Choosing between NPS vs PPF vs EPF is easier with a clear picture. Connect with Shree Radha Financial Services for a personalized discussion on the investment side of your retirement plan. For your own EPF, NPS or tax case, please ask your employer, EPFO, PFRDA or CA.
📞 Call/WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services, Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN05763
Investing since 2012 | BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN05763). All content is strictly for educational purposes only and does not constitute individualized investment advice. We do not advise on individual EPF, PPF, NPS or tax cases. Please confirm your own case with your employer, EPFO, PFRDA or CRA, and a qualified tax professional. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing. Rules and rates change from time to time. Tax treatment is based on the Income-tax Act 2025 as verified on 4 November 2026 and is subject to change. The characters in this article are fictional.