PPF Rules in India: Why a Simple Account Confuses So Many People
The PPF rules look simple on paper. Deposit up to ₹1.5 lakh a year, wait 15 years, collect a tax-free amount. But real families trip over the details: a missed deposit, a child’s account, a date on the calendar, or a form nobody told them about.
This guide puts all the PPF rules in one place, in plain words. Most people only learn the PPF rules after making a mistake. You will meet four families from Surat, Ahmedabad, Vadodara and Rajkot, each with a different question. By the end, you will know what PPF is good at, and where it stops being enough.
If you want the bigger picture of all retirement schemes first, read our retirement schemes guide. This article goes deep on PPF alone.
“People tell me PPF is boring. I tell them boring is the point. But I also see people lose money’s worth of interest because they deposited on the 6th instead of the 4th, or open a second account that earns nothing. Knowing the PPF rules is cheap. Not knowing them is expensive.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
PPF Rules at a Glance
Last verified on 27 October 2026. Rates and rules can change. Keep this table handy: these PPF rules answer most everyday questions.
| Point | PPF rule |
|---|---|
| Who can open | Resident Indian individuals. A parent or legal guardian can open one for a minor. Not available as a joint account |
| Where | Post office or authorised banks |
| Minimum and maximum deposit | ₹500 minimum, ₹1.5 lakh maximum in a financial year, in multiples of ₹50 |
| Interest rate | 7.1% for October to December 2026. Set by the government every quarter |
| Interest calculation | On the lowest balance between the 5th and the end of each month. Added once a year, on 31 March |
| Tenure | 15 years from the end of the financial year in which you opened it |
| Loan | From the 3rd to the 6th financial year |
| Partial withdrawal | From the 7th financial year, once a year |
| After 15 years | Close, extend without deposits, or extend with deposits, in 5-year blocks |
| Tax | Interest and maturity tax-free. Contribution deduction only in the old tax regime |
You can find the official scheme details on the India Post website and the National Savings Institute website.
PPF Rules Story 1: Kinjal in Surat and the Account That “Died”
Kinjal is 41. She lives in Adajan, Surat, and runs a small tailoring work from home. Eight years ago she opened a PPF account at the post office. She put in ₹10,000 in the first year, and again in the second. Then her mother-in-law fell ill, money got tight, and she stopped.
Two years later she visited the post office to ask about her PPF. The clerk said, “Madam, your account is discontinued.”
Kinjal went pale. She thought it meant all her money was gone. In her head, PPF was like a fixed deposit: put it once and forget it. She also thought that if she had missed deposits, the government must have cancelled the account.
Here is what the PPF rules actually say. You must deposit at least ₹500 in every financial year. If you miss a year, the account becomes discontinued. But it is not lost. The balance keeps earning interest. What you lose is access: you cannot take a loan or a partial withdrawal until the account is revived.
To revive it, you pay the minimum ₹500 for each missed year, plus a default fee of ₹50 for each missed year. Kinjal had missed two years, so she paid ₹550 for each year: ₹1,100 in total. After that, the account was active again. That is how the PPF rules treat a missed year: a small fine, not a loss.
Her mistake was not the missed deposits. It was staying silent for two years because she was afraid to ask. A small, regular deposit, even the minimum ₹500, would have kept the account alive. For homemakers and small earners like Kinjal, our SIP guide for homemakers shows how a small monthly habit can run beside PPF.
PPF Rules on Deposits, Interest and the 5th-of-the-Month Rule
Among all the PPF rules, this one costs people the most without them noticing. PPF interest is not calculated on a daily average. The rule is simple but sharp: interest for a month is worked out on the lowest balance between the close of the 5th and the last day of that month. The interest for the whole year is added to your account on 31 March, and it compounds from the next year.
What does that mean for you? If you deposit on or before the 5th, that money earns interest for that whole month. If you deposit on the 6th, it earns nothing for that month.
Let us look at the numbers. Assume ₹1.5 lakh a year for 15 years at a steady 7.1% (illustrative; the real rate changes every quarter):
| How you deposit | Balance after 15 years (approx.) |
|---|---|
| ₹1.5 lakh in one go, on or before 5 April every year | ₹40.68 lakh |
| ₹1.5 lakh in one go, on 6 April every year | ₹40.46 lakh (about ₹22,000 less) |
| ₹12,500 every month, always by the 5th | ₹39.45 lakh (about ₹1.24 lakh less than the April lump sum) |
Illustrative only. Real rates change every quarter, so real results will differ.
So the PPF rules reward two habits. Deposit by the 5th, and deposit early in the year if you can arrange it. Many salaried people cannot find ₹1.5 lakh in April. That is fine. A monthly deposit by the 5th still works well. The point is not to be perfect, only to avoid giving away interest by accident.
PPF Rules Story 2: Mahesh in Ahmedabad and His Daughter’s Account
Mahesh is 39. He works in a pharma company in Ahmedabad. He has a daughter, Riya, aged 9. A colleague told him: “Open a PPF in Riya’s name. Put ₹1.5 lakh in yours and ₹1.5 lakh in hers. Double benefit.”
Mahesh did exactly that. In March he deposited ₹1.5 lakh in his own account and ₹1.5 lakh in Riya’s. He thought he had ₹3 lakh working for them.
When we spoke on a phone call (we have no office in Ahmedabad), he asked one question: “Why is Riya’s passbook showing no interest on the second deposit?”
This is the combined limit in the PPF rules. The PPF rules say that the total you deposit in your own account and in any minor’s account you open is capped at ₹1.5 lakh in a financial year. It does not reset for each account. The extra ₹1.5 lakh earned no interest, and it did not qualify for any deduction. It can be taken back.
Mahesh also learned two more rules. A minor’s PPF can be opened and run only by a parent or legal guardian. A grandparent opening it usually does not fit the rules. And when Riya turns 18, she becomes the account holder, and the 15 years run from the year the account was opened.
Mahesh’s mistake was believing one account per person means one limit per account. It is one limit per family member who deposits. If you are planning for a child’s education too, read Child Education and Retirement Fund: 5 Costly Mistakes to Avoid.
PPF Rules on Who Can Open an Account: Minors, HUF, Joint Accounts and NRIs
The PPF rules differ by type of account holder.
- One account per person. A second account in your own name does not earn the PPF rate. Close the extra one. Irregular accounts may be treated differently under recent Finance Ministry circulars, so ask your bank or post office.
- Joint accounts are not allowed. You can add a nominee, and you can open a separate account for your spouse.
- Minors: opened by a parent or legal guardian. Deposits count in the guardian’s ₹1.5 lakh limit.
- HUF: a new PPF account cannot be opened in the name of a HUF. Old HUF accounts can continue until maturity.
- NRIs: a person who is an NRI cannot open a new PPF account. If you were a resident when you opened it and moved abroad later, the PPF rules let you keep the account until maturity, with no extension. Details below.
Parth, Originally from Surat, Now in Dubai
Parth moved to Dubai six years ago. His PPF account, opened in Surat in 2014, was still running, and he kept depositing every March. On a video call he asked, “Can I extend my PPF after 15 years like my brother in Surat?”
No. For an NRI, the PPF rules are different. The existing account can continue until it matures. After maturity, extension is not allowed, and the balance has to be taken out. Recent circulars have also changed interest on extended NRI accounts, so please check the latest position with your bank or post office. For wider NRI planning, read our NRI retirement planning guide.
PPF Rules Story 3: Jignesh in Vadodara, a Loan and a Withdrawal in One Account
Jignesh is 44. He owns a small auto-parts shop in Vadodara. In April 2018, he opened a PPF account and has deposited ₹1.5 lakh every year since, always before the 5th. He thinks of PPF as money he must never touch.
In the 4th year, his daughter’s school fee and shop repairs landed in the same quarter. He needed about ₹80,000. His first thought was a personal loan at a high rate. His second thought was: “Can I use my PPF?”
He can, and this is where the PPF rules on loan and withdrawal matter. To keep the example clear, we assume a steady 7.1% on his PPF (illustrative). The balances below are rounded.
| Financial year | Year-end balance (approx.) | What happened |
|---|---|---|
| Year 1 (2018-19) | ₹1.61 lakh | Account opened |
| Year 2 (2019-20) | ₹3.33 lakh | This balance sets his loan limit for year 4 |
| Year 4 (2021-22) | ₹7.14 lakh | Loan taken: about ₹83,000 (25% of the year 2 balance) |
| Year 5 (2022-23) | ₹9.26 lakh | This balance sets his withdrawal limit for year 9 |
| Year 8 (2025-26) | ₹16.54 lakh | Loan fully repaid within 36 months. Balance for year 9 comparison |
| Year 9 (2026-27) | ₹19.32 lakh | Partial withdrawal: up to about ₹4.63 lakh (50% of the lower of year 5 and year 8 balances) |
Illustrative only, at a steady 7.1% and ₹1.5 lakh deposited every April by the 5th. The actual rate changes every quarter, so real balances will differ.
Every step in this example follows the PPF rules on loan and partial withdrawal exactly as listed in the table further below.
Here is how each rule worked for Jignesh:
The loan (year 4). He could borrow up to 25% of his balance at the end of the second year before the year he applied. That was year 2: ₹3.33 lakh, so about ₹83,000. The loan carried an interest rate 1% above the PPF rate, so about 8.1% in our example. He had 36 months to repay. If he had not repaid in time, the rate would have jumped to 6% above the PPF rate. Also, while the loan was outstanding, that borrowed part stopped earning PPF interest. He took the loan only once, and repaid it fully before taking a second one.
The partial withdrawal (year 9). From the 7th year, he could take out part of the money. The limit is 50% of the lower of two balances: the balance at the end of the 4th year before the year of withdrawal, and the balance at the end of the previous year. For year 9, those were the year 5 balance (₹9.26 lakh) and the year 8 balance (₹16.54 lakh). The lower is ₹9.26 lakh, so he could take up to 50% of that: about ₹4.63 lakh. He could take it once in the year.
The tax. Neither the loan nor the withdrawal was taxed. The money stayed tax-free because PPF is exempt on interest and maturity.
Jignesh’s real lesson was a balance. The loan was cheaper than a personal loan, but the cost was not zero: the borrowed part stopped compounding. The withdrawal gave him cash, but the amount taken out also stopped growing tax-free. Many families take a PPF loan or withdrawal as a first resort. For a long-term goal like retirement, it works better as a last resort after emergency savings.
PPF Withdrawal Rules: Where, When and How Much
This is the section most people search for. Each PPF option has a different timing, amount and cost.
| Option | When you can use it | How much | Cost or condition |
|---|---|---|---|
| Loan | From the 3rd to the 6th financial year of the account | Up to 25% of the balance at the end of the second year before the year of application | Interest 1% above the PPF rate. Repay within 36 months, or the rate becomes 6% above. A second loan only after the first is repaid |
| Partial withdrawal | From the 7th financial year, one withdrawal per financial year | Up to 50% of the lower of: the balance at the end of the 4th year before the withdrawal year, or the balance at the end of the previous year | Tax-free. The withdrawn amount stops growing |
| Premature closure | After 5 completed financial years, only for specified reasons: serious illness of you, your spouse or dependent children; higher education of you or dependent children; change of residency status | The full balance | Interest is recalculated at 1% lower than the rate you earned. Documents are needed |
| Maturity | After 15 financial years | The full balance | Tax-free |
| On death of the holder | Any time | The full balance to the nominee or legal heir | Nominee should be registered. Keep documents ready |
Where to apply: at the same bank branch or post office where your account is held. These PPF rules apply the same way at both. Many banks also allow some of these through net banking, but not all. Please check with your bank or post office. The forms often asked for are the withdrawal form (Form C), the loan form (Form D) and the closure form (Form 5). Your branch will tell you the current ones.
Counting the years: The “year 1” of your PPF is the financial year in which you opened it, even if you opened it in March. So an account opened in April 2018 has its first financial year as 2018-19. This is why people are often a year off when they plan withdrawals.
PPF Rules Story 4: Hasmukhbhai in Rajkot and the Maturity Date
Hasmukhbhai is 58. He retired from a private company in Rajkot and opened his PPF in August 2011. He thought it would mature in 2026, “15 years from 2011”.
When he checked, the bank said the account matures on 31 March 2027. His first reaction: “Why the extra months?”
This is how the PPF rules count. The 15 years begin from the end of the financial year in which the account was opened. His account was opened in 2011-12, so the 15 years end on 31 March 2027.
He then asked what he can do. After maturity, there are three paths:
- Close the account and take the full balance, tax-free.
- Extend for 5 years without deposits. The balance keeps earning the PPF rate. You can withdraw any amount, once in a financial year.
- Extend for 5 years with deposits. You need to give a written request (Form H) within one year of maturity. Otherwise the account is treated as extended without deposits. While extended with deposits, you can withdraw up to 60% of the balance at the start of the extension block, once in a year. Deposits continue within the ₹1.5 lakh yearly limit.
The extension can be repeated in blocks of 5 years. These PPF rules on extension are the ones people miss most often. Confirm the exact current form and process with your bank or post office.
Hasmukhbhai asked what each option would mean for a steady ₹1.5 lakh deposit scenario. Here is the illustration, at a steady 7.1%:
| PPF extension rules: path | Balance after 20 years (approx.) | What it means |
|---|---|---|
| Close at 15 years | ₹40.68 lakh paid out at year 15 | Money is free to use elsewhere, and no longer earns PPF interest |
| Extend 5 years, no deposits | ₹57.33 lakh | The existing balance keeps growing tax-free |
| Extend 5 years, with ₹1.5 lakh deposits | ₹66.58 lakh | More tax-free growth, if you can keep depositing |
Illustrative only, at a steady 7.1%. No promise of future rates.
Hasmukhbhai also noticed something important. ₹40.68 lakh after 15 years sounds large. But at 6% yearly inflation, that amount would buy only what about ₹17 lakh buys today. PPF is excellent at protecting money. It is not designed to beat inflation by a wide margin. That brings us to the next part.
PPF Rules on Tax: EEE in the Old and New Tax Regime
PPF is the most tax-friendly of all retirement schemes, and the PPF rules on tax are easy to follow. EEE means Exempt, Exempt, Exempt: exempt when you put money in, exempt while it grows, exempt when you take it out.
The Income-tax Act, 2025 came into effect on 1 April 2026. The old Section 80C basket (limit ₹1.5 lakh) now sits in Section 123. Earlier this was Section 80C under the 1961 Act. You can see the law on the Income Tax Department website.
| Stage | Old tax regime | New tax regime |
|---|---|---|
| Your deposit | Deduction under Section 123, within the overall ₹1.5 lakh limit | No deduction |
| Employer contribution | Not applicable. There is no employer share in PPF | Not applicable |
| Yearly interest | Tax-free (earlier Section 10(11)). No TDS | Tax-free. No TDS |
| Loan | Not income. Not taxed | Not taxed |
| Partial withdrawal, closure, maturity | 100% tax-free | 100% tax-free |
For your tax return: PPF interest is exempt income. The return forms ask you to show exempt income separately. Earlier, PPF interest was shown under Section 10(11). Please confirm the current section reference and the right place on your form with your tax consultant or CA.
Deposits for your spouse or child: Under the earlier Section 80C rules, deposits into a spouse’s or child’s PPF could also count for your deduction (old regime). Confirm how Section 123 treats this for your case.
Protection from creditors: PPF balances are generally protected from attachment by civil courts for private debts under the PPF Act, 1968. For business owners, that is a useful feature. The rules around tax dues and special laws can differ, so please check with your lawyer for your situation.
PPF Rules: Where PPF Helps Most
The PPF rules suit some people better than others.
- Self-employed people and business owners with no employer provident fund, like Hitesh-type traders in Surat who need a steady pot outside the business.
- Homemakers and small earners who want a safe habit with a tiny starting amount of ₹500.
- Parents who want a long-term safe pot for a child, within the combined limit.
- Anyone who values tax-free certainty on interest and maturity, whichever regime they choose.
- People who need a forced lock-in, because the 15 years stop you from spending the money.
PPF Rules: Where PPF Has Limits
A balanced view matters. These are the real limits in the PPF rules:
- The ₹1.5 lakh cap. For a high earner, PPF alone cannot build a large retirement corpus.
- Inflation. After tax, a PPF rate near 7% may only slightly beat inflation, as Hasmukhbhai saw.
- Variable rate. The rate is not fixed for 15 years. It is reset every quarter.
- Lock-in. Money is hard to reach for the first 6 years, and partly limited after that.
- No tax deduction under the new regime. You get the exemption on interest, but not the deduction on deposits.
- No employer matching and no joint account.
- NRI restrictions on new accounts and extension.
That is why PPF usually works best as the safety bucket, next to a growth bucket and an income bucket. The retirement planning guide for Surat investors and Is ₹2 crore enough to retire show how families add the other buckets. For a look at how a hybrid option sits next to a safe deposit, see our hybrid SIF vs fixed deposit guide. We will compare NPS, EPF and PPF side by side in a separate guide.
Want to test your own numbers? Use our calculator.
Seven PPF Rules Mistakes to Avoid
- Depositing on the 6th instead of by the 5th.
- Missing a year’s ₹500 and letting the account turn discontinued.
- Opening a child’s account and an own account and depositing over the combined limit.
- Opening a second account in your own name.
- Counting the 15 years from the date of opening, not from the end of that financial year.
- Forgetting the extension form (Form H) within one year of maturity.
- Using the loan or partial withdrawal for lifestyle needs, and not for real needs.
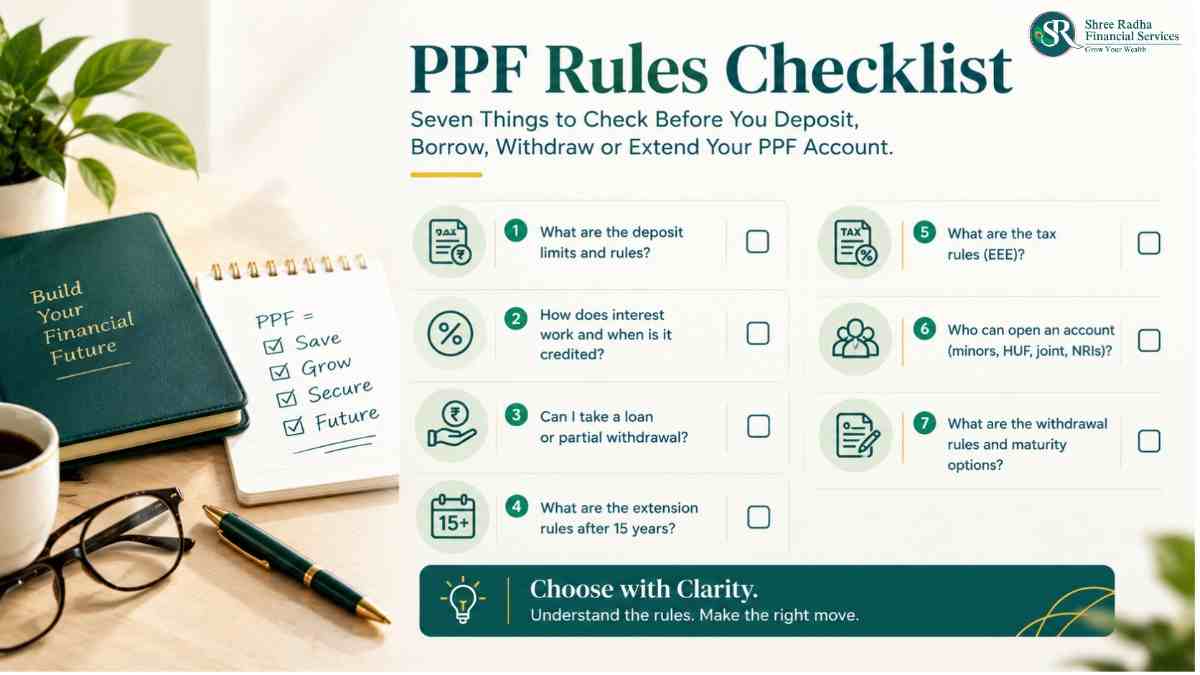
PPF Rules Checklist: Seven Things to Check
Use this list to apply the PPF rules to your own account.

- Have I deposited at least ₹500 this financial year? It keeps the account active.
- Will my deposit land by the 5th? It earns interest for that month.
- Are my own and my child’s deposits within ₹1.5 lakh together?
- Which financial year is my “year 1”? That decides loan and withdrawal dates.
- Do I know my maturity date? Note 31 March of the 15th year, and the Form H deadline.
- Which tax regime am I in? The deduction applies only to the old regime.
- Is my nominee registered and my passbook updated?
Rules and regulations change from time to time. Please connect with your tax consultant / CA for details specific to your situation. Figures in this article were last verified on 27 October 2026.
PPF Rules: Frequently Asked Questions
What are the main PPF rules on deposit limits?
Under the PPF rules, the minimum is ₹500 and the maximum is ₹1.5 lakh in a financial year, across your own account and any minor’s account you open. Deposits above the limit earn no interest.
What happens if I miss a PPF deposit?
The account becomes discontinued. You can revive it by paying ₹500 for each missed year plus a ₹50 default fee for each missed year. Until then, you cannot take a loan or a withdrawal.
Can I withdraw money from PPF before 15 years?
Yes. You can take a loan from the 3rd to the 6th financial year, and a partial withdrawal from the 7th year. Premature closure is possible after 5 completed years, only for specified reasons.
What are the PPF extension rules after 15 years?
You can close the account, extend for 5 years without deposits, or extend for 5 years with deposits by submitting Form H within one year of maturity. Extensions can be repeated in 5-year blocks.
Is PPF interest taxable in the new tax regime?
No. PPF interest and maturity are tax-free in both regimes. The deduction on your deposit is available only in the old regime.
Can an NRI open or extend a PPF account?
An NRI cannot open a new account. An account opened while you were a resident can continue until maturity, but cannot be extended. Please check the latest circulars with your bank or post office.
Can I open a PPF account for my child?
Yes, a parent or legal guardian can. The deposits count within the same ₹1.5 lakh yearly limit as the parent’s own account.
Is the PPF rate fixed for 15 years?
No. Under the PPF rules, the government reviews the rate every quarter. It is 7.1% for October to December 2026.
This article is also available on Medium for wider reading:https://medium.com/@shreeradha.services/ppf-rules-in-india-the-5th-of-the-month-rule-loan-withdrawal-and-extension-explained-045345c3d2ee
Want to See How the PPF Rules Fit Your Retirement Plan?
Connect with Shree Radha Financial Services for a personalized discussion.
📞 Call/WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services, Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN05763
Investing since 2012 | BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN05763). PPF is a government savings scheme and is not a product distributed by us. All content is strictly for educational purposes only and does not constitute individualized investment advice. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing. Tax treatment is based on current laws and subject to change. Please consult a qualified tax professional before investing. The characters in this article (Kinjal, Mahesh, Riya, Parth, Jignesh and Hasmukhbhai) are fictional and used only to explain situations. Numbers in the worked examples are illustrative at a steady 7.1% and are not a promise of returns.