Carry Forward of Losses: Four Mistakes That Cost Taxpayers Their Loss Claims
Carry forward of losses is one of the few places where the tax law gives something back. A loss this year can be set off against income in later years. But the rules are strict, and one missed step can end the claim for good.
Most taxpayers lose the benefit not because the law is hard, but because nobody told them the conditions. The Income-tax Act 2025 (Tax Year 2026-27) keeps most of the old rules and changes the section numbers.
Note: The people and numbers in the four stories below are illustrative, to explain the rules. They are not real clients.
“When a client has a loss, the first question is not ‘how much?’ but ‘when did you file?’ A loss that is not recorded in time can disappear, and the person usually finds out a year later, when the gain arrives.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
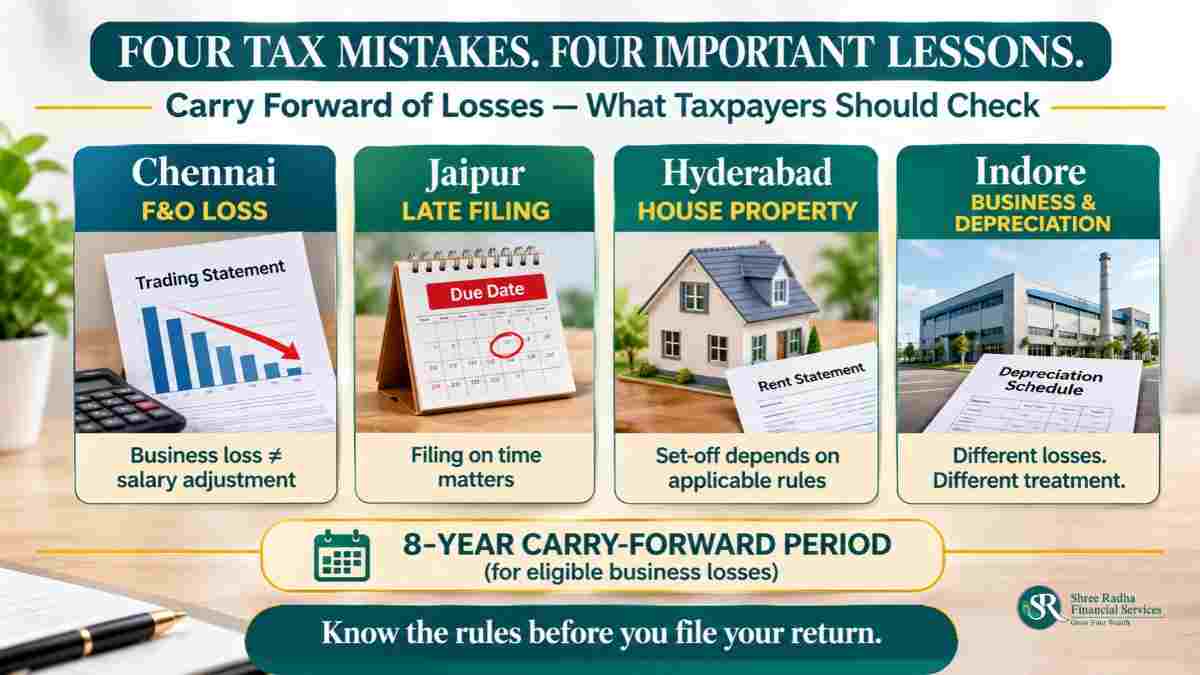
Story 1: Chennai, the Salaried Trader Who Wanted His F&O Loss Against Salary
Karthik, 36, is a software architect in Chennai. His salary is Rs 24 lakh. This year he also traded in futures and options and ended with a net loss of Rs 3.5 lakh.
He planned to deduct the whole loss from his salary and get a lower tax bill.
What went wrong
Under Section 109(1)(a), a business loss cannot be set off against income under the head “Salaries”. F&O trading is generally treated as business, so his loss is a business loss. His tax on salary did not change.
The right way
A business loss can be set off against income under other heads in the same year, such as capital gains. Whatever remains can be carried forward for up to 8 years under Section 112, and used against business profits only. This needs the return to be filed by the due date (Section 121).
One more point. Intraday equity trades that are settled without delivery are generally speculation, and a speculation loss goes only against speculation profit (Section 113). Whether a particular trade is speculation or not is something to confirm with your CA. A person with business income files ITR-3, not ITR-4. Our ITR-4 or ITR-3 guide explains why.
Story 2: Jaipur, the Investor Who Filed Late
Sunita, 44, lives in Jaipur and invests in shares. In a market fall she booked a short-term capital loss of Rs 4 lakh. She was busy with a family wedding and filed her return after the due date.
Next year she booked a short-term gain of Rs 5 lakh. She expected to set the old loss against it.
What went wrong
Section 121 says a capital loss can be carried forward only if it was determined in a return filed under Section 263(1), the return filed by the due date. A late return is filed under Section 263(4). Her Rs 4 lakh loss could not be carried forward. The same would have happened if she had not filed at all.
Setting off a loss within the same year does not depend on this rule. Only the carry forward is lost.
The right way
File by the due date even when no tax is payable, so the loss is recorded. A short-term capital loss can be set off against any capital gain. A long-term capital loss can be set off only against long-term gains. Both can be carried forward for 8 years (Section 111).
Mutual fund investments are subject to market risks. Read all scheme-related documents carefully. For rates and gains, see our mutual fund taxation guide.
Story 3: Hyderabad, the Landlord With a House Property Loss
Deepa, 40, works in Hyderabad with a salary of Rs 20 lakh. She owns a let-out flat in Pune. After interest and the standard deduction, the flat shows a loss of Rs 3.2 lakh under the head “Income from house property”.
She expected the full Rs 3.2 lakh to reduce her salary income.
What went wrong
Section 109(1)(b) allows a house property loss to be set off against other heads only up to Rs 2,00,000. In the new regime, Section 202(2)(b)(ii) does not allow the set-off against other heads at all.
The right way
Under the old regime, Rs 2 lakh can be set off against other income. The remaining Rs 1.2 lakh is carried forward for up to 8 years and used only against house property income (Section 110). In the new regime, the loss can still be carried forward, but your CA should confirm the position for your case.
Also note that in the new regime, interest on a self-occupied home is not allowed as a deduction (Section 202(2)(a)(v)), so no loss arises there. Compare both regimes before choosing. Our old vs new tax regime guide and house property guide help.
Story 4: Indore, the Manufacturer Who Lost One Claim but Not the Other
Ankit runs a small auto-component unit in Indore. In a weak year the unit made a business loss of Rs 5 lakh before depreciation. Depreciation of Rs 3 lakh also went unused. A factory strike delayed his accounts, and he filed after the due date.
Next year the unit earned a profit of Rs 7 lakh. He hoped to use both amounts against it.
What went wrong
The Rs 5 lakh business loss was lost. Section 112 carry forward needs a due-date return under Section 121.
The right way
The Rs 3 lakh depreciation is treated differently. Section 33(11) adds unabsorbed depreciation to the next year’s depreciation, with no end date. Section 121 does not name it. The official FAQ confirms that unabsorbed depreciation from earlier years has no time limit. How a late return affects it in a particular case is a point to confirm with your CA.
Also, Section 112(3) says business loss is given effect first. Business owners can read our presumptive taxation guide to see when they need full books.
What the Act Says on Set-off and Carry Forward of Losses
Set-off has two steps. First, a loss is set off against other income of the same year. Then, if something is left, it is carried forward. Chapter VII of the Income-tax Act 2025 (Sections 108 to 121) covers both. It replaces Sections 70 to 80 of the 1961 Act.
| Loss under | Can be set off against (same year) | Cannot be set off against | Section |
|---|---|---|---|
| One source in a head | Other sources under the same head | Capital gains follow separate rules | 108(1) |
| Short-term capital asset | Income from any other capital asset | Any other head | 108(2)(a), 109(2) |
| Long-term capital asset | Income from other long-term assets only | Short-term gains and other heads | 108(2)(b), 109(2) |
| Business or profession (not speculation) | Other heads, including capital gains | Salaries | 109(1)(a) |
| House property | Other heads, up to Rs 2,00,000 | Anything above Rs 2,00,000 | 109(1)(b) |
| Speculation business | Speculation profit only | All other income | 113(1) |
Now the carry forward. This is where the due-date return matters.
| Loss | Carried forward for | Set off later against | Due-date return needed? | Section |
|---|---|---|---|---|
| House property | 8 tax years | House property income only | Not listed in Section 121 | 110 |
| Capital loss | 8 tax years | Short-term: any capital gain. Long-term: long-term gains only | Yes | 111 |
| Business loss (not speculation) | 8 tax years | Business or profession profits | Yes | 112 |
| Speculation loss | 4 tax years | Speculation profit only | Yes | 113 |
| Specified business loss | No time limit seen in the text; confirm with your CA | Specified business profit only | Yes | 114 |
| Unabsorbed depreciation | Added to next year’s depreciation, no end date | Business profit, and other heads except salary | Not listed in Section 121 | 33(11) |
The eight-year count starts from the year the loss was first computed. Rules and rates change from time to time. Please confirm with your tax consultant / CA.
Carry Forward of Losses and the New Tax Regime
The new regime in Section 202 changes how some losses work. Check these points before you choose a regime.
| Point | Old regime | New regime (Section 202) |
|---|---|---|
| House property loss against other heads | Up to Rs 2,00,000 | Not allowed (Section 202(2)(b)(ii)) |
| Interest on a self-occupied home | Allowed within limits | Not allowed (Section 202(2)(a)(v)) |
| Carried-forward loss or depreciation tied to deductions barred in the new regime | Allowed as per the old rules | Not set off (Section 202(2)(b)(i)) |
| Business loss, capital loss | As per Sections 108 to 114 | Same rules |
For a person with business income, opting for the old regime and returning to the new one has special conditions in Section 202(4)(a). Ask your CA before switching.
Carry Forward of Losses From Before 1 April 2026
Many readers have losses from earlier years. The Income Tax Department’s FAQ answers the main questions.
| Question | Answer from the official FAQ |
|---|---|
| Do old-Act losses survive? | Yes, under the saving clause in Section 536, in the same way as under the old Act |
| Does the 8-year clock restart? | No. It counts from the original assessment year |
| Is a belated old-Act loss return revived? | No. The new Act does not cure the defect |
| Does unabsorbed depreciation expire? | No. The unlimited carry forward continues |
| Is a loss reclassified into another head? | No. It keeps its original character |
The return for FY 2025-26 is filed under the 1961 Act, so its loss rules and section numbers still follow the old Act. The first return under the new Act is for Tax Year 2026-27.
Special Cases: Crypto, Speculation and Undisclosed Income
| Case | Rule in the Act | Section |
|---|---|---|
| Loss on transfer of a virtual digital asset (crypto) | No set-off against any income and no carry forward | 194(1), Table Sl. 4 |
| Speculation business | Treated as separate from other business; loss against speculation profit only | 26(3), 113 |
| Undisclosed income found in search or survey | Brought-forward loss and depreciation cannot be set off against it | 120 |
| Loss not determined in a due-date return | No carry forward for capital, business, speculation, specified business and race horse losses | 121 |
Where Losses Appear in the ITR-3
The current ITR-3 form (AY 2026-27, income of FY 2025-26) has separate schedules for losses. The return for Tax Year 2026-27 will use the form notified for that year, so check the schedule names there.
| Schedule | What it records |
|---|---|
| CYLA | Set-off of this year’s losses against this year’s income |
| BFLA | Set-off of brought-forward losses and depreciation |
| CFL | Losses to be carried forward, with the return filing date for each year |
| UD | Unabsorbed depreciation |
| Subject | 1961 Act | 2025 Act |
|---|---|---|
| Set-off within the same head | Section 70 | Section 108 |
| Set-off across heads | Section 71 | Section 109 |
| House property loss carry forward | Section 71B | Section 110 |
| Capital loss carry forward | Section 74 | Section 111 |
| Business loss carry forward | Section 72 | Section 112 |
| Speculation and specified business loss | Sections 73, 73A | Sections 113, 114 |
| Return needed for carry forward | Section 80 | Section 121 |
| New tax regime | Section 115BAC | Section 202 |
Official Sources to Read
- Income Tax Department: the Income-tax Act page, Chapter VII, Sections 108 to 121.
- e-Filing portal: the set off and carry forward of losses FAQs.
- AMFI: amfiindia.com for mutual fund scheme information.
Read these along with our income tax computation guide and Section 54 capital gains guide. The rules on carry forward of losses are easier once you see how each head is computed.
How SR Wealth Can Help
Shree Radha Financial Services is an AMFI Registered Mutual Fund and SIF Distributor and an APMI Registered PMS Distributor. We are not tax consultants. What we do:
- Explain the products you hold or are considering, such as mutual funds, SIF, PMS and deposits
- Help you keep clean records of purchases, sales and statements, so your CA can work out gains and losses
- Connect you with a competent CA or tax consultant if you need one for your salary tax, return or notice
Carry Forward of Losses: Frequently Asked Questions
1. Can an F&O loss be set off against salary?
No. A business loss cannot be set off against salary (Section 109(1)(a)). It can be set off against other heads in the same year, and the rest can be carried forward for 8 years against business profits.
2. Can a short-term capital loss be set off against a long-term gain?
Yes. A short-term capital loss can be set off against any capital gain (Sections 108(2) and 111).
3. Can a long-term capital loss be set off against a short-term gain?
No. A long-term capital loss can be set off only against long-term gains.
4. How many years can losses be carried forward?
House property, capital and business losses: 8 tax years. Speculation loss: 4 tax years. Unabsorbed depreciation has no end date in Section 33(11).
5. What happens if I file a belated return?
Capital, business, speculation, specified business and race horse losses cannot be carried forward (Section 121). Check house property and depreciation with your CA.
6. Can house property loss reduce salary in the new regime?
No. Section 202(2)(b)(ii) does not allow house property loss to be set off against other heads in the new regime.
7. Is intraday trading loss the same as F&O loss?
Generally not. Intraday equity trades settled without delivery are speculation. A speculation loss goes only against speculation profit. Confirm the classification with your CA.
8. Can crypto losses be set off?
No. Section 194(1) allows no set-off and no carry forward for loss on transfer of a virtual digital asset.
9. Does unabsorbed depreciation expire?
No. It is added to the next year’s depreciation, with no time limit.
10. Do losses from the old Act still count under the new Act?
Yes, under Section 536, in the same way as under the old Act. The 8-year clock is not restarted, and a loss return filed late under the old Act is not revived.
This article is also available on Medium for wider reading:https://medium.com/@shreeradha.services/one-late-return-can-end-your-loss-claim-what-investors-and-traders-should-know-3cd207d935b4
Planning Your Investments and Records?
If you want to talk about SIPs, mutual funds, SIF or retirement income planning, connect with Shree Radha Financial Services for a personalized discussion.
📞 Call/WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services, Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN05763
IRDAI Licensed Insurance Distributor
Investing since 2012 | BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN05763). All content is strictly for educational purposes only and does not constitute individualized investment or tax advice. The characters in this article are fictional. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing. Rules and rates change from time to time. Please confirm with your tax consultant / CA. Tax treatment is based on current laws and subject to change.