EPF Rules in 2026: Why Everyone Is Asking
EPF rules changed in 2026, and most salaried people have not noticed. On 29 June 2026, the government notified three new schemes under the Code on Social Security, 2020: the Employees’ Provident Funds Scheme, 2026, the Employees’ Pension Scheme, 2026 and the Employees’ Deposit-Linked Insurance Scheme, 2026. They replace the old 1952, 1995 and 1976 schemes. The new EPF rules also write the 2025 board decisions on withdrawal into the scheme itself.
This guide is arranged in the order you will use it. Part 1 covers EPF in detail: contribution, then interest, then withdrawal, with the tax-free limit at each step. Part 2 covers the EPS pension. Part 3 covers EDLI insurance. You will meet four people from Gurugram, Surat, Indore and Chennai. Each one believed something about the EPF rules that was only half true. You will see what they thought, where the mistake was, and how it was corrected.
We checked the EPF rules against the three scheme texts published in the Gazette, and against the Income-tax Act, 2025. You can also see the official sites of the Employees’ Provident Fund Organisation (EPFO) and the Ministry of Labour and Employment. For the wider picture, start with our retirement schemes guide and our PPF rules guide.
“Most salaried people see one line on the payslip called PF. They never see that it is really three schemes: a savings account, a pension and an insurance cover. Knowing which is which is half the planning.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
EPF Rules at a Glance: Three Schemes, the ₹15,000 Limit and Three Equations
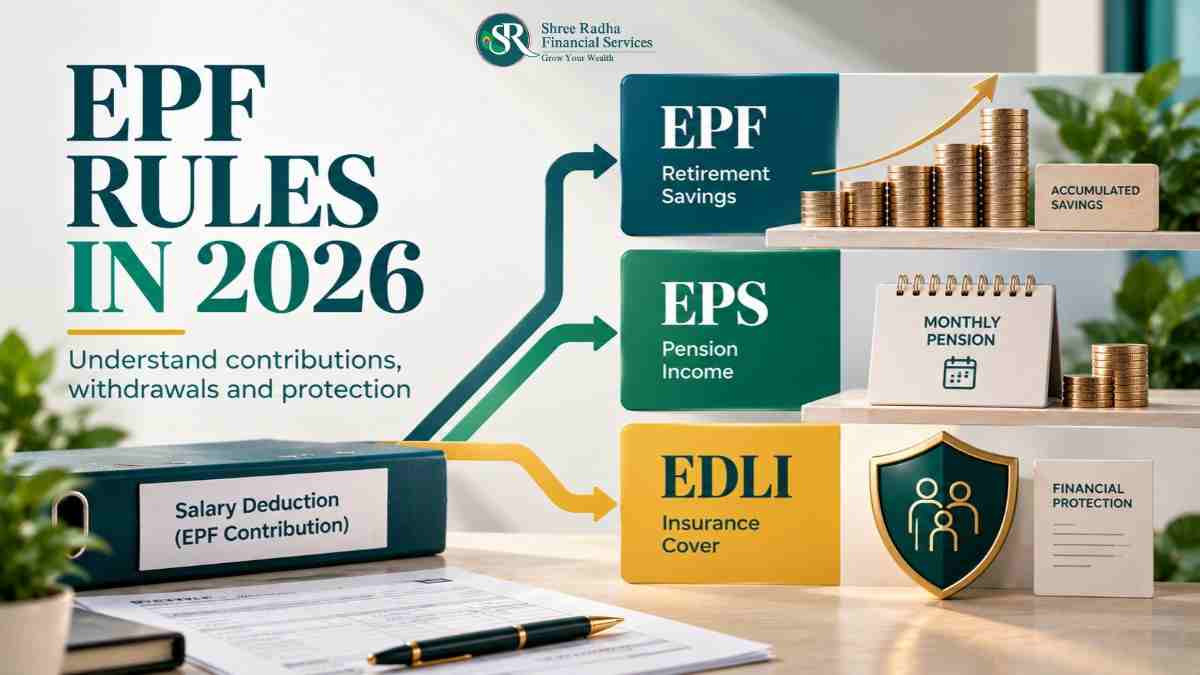
The three schemes in one table
| Point | EPF (savings) | EPS (pension) | EDLI (insurance) |
|---|---|---|---|
| What it is | Your own provident fund account | A monthly pension after service | A life cover paid to your family if you die in service |
| Who pays | You 12% and your employer 12% of salary, within the limit | Part of the employer’s 12%, plus 1.16% from the Government | Only the employer. Nothing is cut from your pay |
| What you get | Balance plus interest, as a lump sum | Pension from the age of superannuation | One-time payment to the nominee or family |
| Needs | Contributions | At least 10 years of eligible service | 12 months of continuous service for the full cover |
Government employees under GPF, NPS or UPS are not in this system. The EPF rules are for employees of establishments covered by Chapter III of the Code. That includes most private and many public sector employees. Some employers run their own PF trust under an exemption. Those members still get the EPS and EDLI protection.
What “salary” means in this guide
The schemes use the word “wages”. In this guide, salary means basic pay plus dearness allowance (DA). This is the part used for PF, EPS and EDLI, and it is the number you should look for on your payslip. The Code defines wages in its own way, and allowances above a certain share can be added to it. Please ask your HR team what the EPF rules count in your PF salary.
The ₹15,000 limit and how it changes everything
The scheme fixes a limit on the salary that is counted. It is called the wage ceiling. Reports say it is ₹15,000 a month at present. The scheme text refers to the “notified” ceiling and does not fix the number, so the Government can change it without changing the scheme. The same limit is used for all three schemes under the EPF rules. Look at what the EPF rules do to a person with a salary of ₹50,000.
| Where the limit applies | The rule | For a salary of ₹50,000 |
|---|---|---|
| EPF contribution (default) | 12% of salary up to the limit. Above the limit only if employee and employer jointly agree | 12% of ₹15,000 = ₹1,800. If agreed on full salary: 12% of ₹50,000 = ₹6,000 |
| EPS pension | Pensionable salary cannot go above the limit | Counted as ₹15,000, not ₹50,000 |
| EDLI cover | 35 times the salary, with the salary capped at the limit | 35 x ₹15,000 = ₹5.25 lakh, not 35 x ₹50,000 |
So a person earning ₹50,000 gets the same pension and the same insurance base as a person earning ₹15,000. Only the EPF part can grow with salary, and only if the employer agrees. This is the most important of all EPF rules.
The three equations
These are the three calculations in this guide. Each is explained again, with numbers, in its own part.
Equation 1 of the EPF rules: contribution each month
PF salary = salary (basic + DA), limited to ₹15,000 (unless both agree to use the full salary)
Employee share = 12% x PF salary
Employer share = 12% x PF salary
Employer part to EPS = 8.33% x salary up to ₹15,000 (so ₹1,250 at most)
Employer part to EPF = Employer share – Employer part to EPS
Total into EPF = Employee share + Employer part to EPF
PF salary = salary (basic + DA), limited to ₹15,000 (unless both agree to use the full salary)
Employee share = 12% x PF salary
Employer share = 12% x PF salary
Employer part to EPS = 8.33% x salary up to ₹15,000 (so ₹1,250 at most)
Employer part to EPF = Employer share – Employer part to EPS
Total into EPF = Employee share + Employer part to EPF
Equation 2 of the EPF rules: EPS pension each month
Pensionable salary = average salary of the last 60 months, limited to the ceiling (₹15,000)
Monthly pension = (Pensionable salary x Pensionable service in years) / 70
Pensionable salary = average salary of the last 60 months, limited to the ceiling (₹15,000)
Monthly pension = (Pensionable salary x Pensionable service in years) / 70
Equation 3 of the EPF rules: EDLI cover
Benefit = (35 x average monthly salary of last 12 months, limited to ₹15,000) + (50% of average PF balance, limited to ₹1,75,000)
The benefit is never less than ₹2,50,000 and never more than ₹7,00,000
Benefit = (35 x average monthly salary of last 12 months, limited to ₹15,000) + (50% of average PF balance, limited to ₹1,75,000)
The benefit is never less than ₹2,50,000 and never more than ₹7,00,000
EPF Rules Part 1: Your Provident Fund Account in Three Steps
The EPF is your own savings account. It has three steps: money goes in (contribution), it grows (interest) and it comes out (withdrawal). We cover each step of the EPF rules in order, with its tax angle. EEE means exempt when you invest, exempt while it grows and exempt when you withdraw. EPF is mostly EEE, with limits at every step. These limits are what the tax rules are really about.
Step 1 of EPF Rules: Contribution
EPF Rules Story 1: Aman in Gurugram and the Missing ₹4,200
Aman is 29. He is a sales manager at a company in Gurugram. His salary (basic + DA) is ₹50,000 a month. One day he compared payslips with his friend Rohit, who has the same salary at another company. Aman’s PF line showed ₹1,800. Rohit’s showed ₹6,000.
Aman believed three things. First: “12% of my ₹50,000 is ₹6,000, so ₹4,200 of my PF is missing.” Second: “The full employer share goes into my PF balance.” Third: “The insurance cover is paid from my own salary.”
“₹4,200 is missing.” Nothing is missing. His company contributes on the ₹15,000 limit, which is the default under the EPF rules. 12% of ₹15,000 is ₹1,800. Rohit’s company has agreed with him to contribute on the full salary, so 12% of ₹50,000 is ₹6,000. Both are allowed under the EPF rules.
“The full employer share goes to my PF.” No. A part of the employer’s 12% goes to the EPS pension, as 8.33% of the salary up to ₹15,000. That is ₹1,250. Only the rest, ₹550 in Aman’s case, goes into his EPF.
“Insurance is paid by me.” No. EDLI is paid only by the employer, and the scheme says the employer cannot recover it from the employee.
Aman’s mistake was reading the payslip line as the whole story, and not the EPF rules behind it. The next table shows exactly how the numbers work for both of them.
The contribution calculation, step by step
Use Equation 1 from above. The EPF rules for contribution are the same for everyone. Both cases are for a salary of ₹50,000.
| Item | Formula | Case A: Aman (₹15,000 limit) | Case B: Rohit (full ₹50,000) |
|---|---|---|---|
| 1. PF salary | Salary, limited to ₹15,000 unless both agree | ₹15,000 | ₹50,000 |
| 2. Employee share | 12% x PF salary | ₹1,800 | ₹6,000 |
| 3. Employer share | 12% x PF salary | ₹1,800 | ₹6,000 |
| 4. Employer part to EPS | 8.33% x ₹15,000 (rounded) | ₹1,250 | ₹1,250 |
| 5. Employer part to EPF | Row 3 – Row 4 | ₹550 | ₹4,750 |
| 6. Total into EPF each month | Row 2 + Row 5 | ₹2,350 | ₹10,750 |
| 7. Total into EPF each year | Row 6 x 12 | ₹28,200 | ₹1,29,000 |
| 8. Cut from take-home pay | Row 2 | ₹1,800 | ₹6,000 |
Illustrative only. 8.33% of ₹15,000 is ₹1,249.50, which the scheme rounds to ₹1,250.
Under the same EPF rules, Rohit builds a much larger PF every month, but his take-home pay is ₹4,200 lower than Aman’s. Neither is wrong under the EPF rules. It is a choice between more savings now and more cash now.
Maximum contribution and the tax-free limits
This table shows who can put how much under the EPF rules, and where the tax-free limit sits. The old regime and new regime are shown side by side.
| Who | How much | Old tax regime | New tax regime |
|---|---|---|---|
| Employee, compulsory | 12% of PF salary (10% for notified classes of establishments) | Deduction under Section 123 (earlier Section 80C), within the overall ₹1.5 lakh limit | No deduction |
| Employee, voluntary (VPF) | Any amount, up to your salary after permitted deductions. The employer need not match it | Counts in the same ₹1.5 lakh limit. Interest is tax-free only while your total contribution in the year stays within ₹2.5 lakh | No deduction. The ₹2.5 lakh interest limit still applies |
| Employer, compulsory | 12% of PF salary (10% for notified classes) | Not taxed in your hands, as long as the employer’s total for the year in EPF, NPS and superannuation is within ₹7.5 lakh | Same |
| Employer, extra or matching | Employer’s choice | Counts in the same ₹7.5 lakh. Above it, the excess and the interest on it are taxable (Section 17(1)(h)-(i), earlier Section 17(2)) | Same |
If your employer does not contribute at all, the tax-free interest limit on your own contribution rises from ₹2.5 lakh to ₹5 lakh a year (Schedule II Sl. 3-4).
A VPF example: where the tax-free limit bites
Aman wants to save more and adds a voluntary contribution (VPF) of ₹15,000 a month. This is the equation.
Equation: your own contribution in a year
Compulsory share = 12% x ₹50,000 x 12 months = ₹72,000 (if his employer used the full salary)
VPF = ₹15,000 x 12 months = ₹1,80,000
Total own contribution = ₹72,000 + ₹1,80,000 = ₹2,52,000
Above the tax-free limit = ₹2,52,000 – ₹2,50,000 = ₹2,000
Compulsory share = 12% x ₹50,000 x 12 months = ₹72,000 (if his employer used the full salary)
VPF = ₹15,000 x 12 months = ₹1,80,000
Total own contribution = ₹72,000 + ₹1,80,000 = ₹2,52,000
Above the tax-free limit = ₹2,52,000 – ₹2,50,000 = ₹2,000
| Item | Amount | What happens |
|---|---|---|
| Own contribution up to ₹2,50,000 | ₹2,50,000 | Interest on this part is tax-free |
| Own contribution above ₹2,50,000 | ₹2,000 | Interest on this part is taxable. At 8.25%, about ₹165 in the first year |
| Tax deduction (old regime) | Only up to ₹1.5 lakh of the total, with other Section 123 items | No deduction in the new regime |
Illustrative only. The 8.25% is the reported rate for FY 2025-26 and can change. Please confirm with your CA.
The lesson from the EPF rules: VPF is useful, but the tax-free limit of ₹2.5 lakh in own contribution a year decides how much of the interest stays tax-free. Aman kept his VPF at a level that stayed within it.
Step 2 of EPF Rules: Interest
- Rate: decided each year by the Central Government with the Central Board. Reports say 8.25% was ratified for FY 2025-26 in June 2026, the same as in the two earlier years. Do not plan a 25-year corpus on today’s rate.
- How it is worked out: on the monthly running balance, credited at the year end. If you withdraw during the year, interest is paid up to the month before the withdrawal month. On a final settlement, interest is paid up to the date the payment is authorised.
- Tax-free limit: interest on your own contribution is tax-free up to ₹2.5 lakh of own contribution a year (₹5 lakh if there is no employer contribution). This applies to contributions made on or after 1 April 2021 (Schedule II Sl. 3-4).
- Interest above the notified rate: taxable as part of salary (Schedule XI Part A para 6). The EPF rules and the Act make it clear that the second E is not unlimited.
What Aman and Rohit could build, using an equation
Growth of a monthly amount is worked out like this. We assume 8.25% a year, flat contributions and 25 years. These are examples, not promises.
Equation: growth of a monthly amount
Corpus = P x [ ((1 + r)^n – 1) / r ]
P = monthly amount into EPF, r = 8.25% / 12 = 0.6875% a month, n = 25 x 12 = 300 months
Corpus = P x [ ((1 + r)^n – 1) / r ]
P = monthly amount into EPF, r = 8.25% / 12 = 0.6875% a month, n = 25 x 12 = 300 months
| After 25 years (illustrative) | Case A: Aman | Case B: Rohit |
|---|---|---|
| Monthly amount into EPF (P) | ₹2,350 | ₹10,750 |
| Total put in over 300 months | ₹7.05 lakh | ₹32.25 lakh |
| Corpus at 8.25% a year | About ₹23.3 lakh | About ₹106.5 lakh |
Illustrative only. Salary and contributions are kept flat. In real life both will rise, and the interest rate will change. Not a promise of returns.
The gap is large. Aman’s EPF is small because the limit is ₹15,000. This is why many people ask how the EPF rules apply to higher salaries, and whether their employer can contribute on the full salary, and why some add VPF.
Step 3 of EPF Rules: Withdrawal, Partial and Full
EPF Rules Story 2: Dhruv in Surat and the Job Gap
Dhruv is 34. He was a marketing executive at a textile firm in Surat with a salary (basic + DA) of ₹50,000. His PF, with interest, is about ₹8 lakh. He resigned in January to start a trading business in Varachha. He told his friends: “Two months after I resign, I can withdraw my full PF.”
Dhruv believed three things. First: “Full withdrawal is allowed two months after resigning.” Second: “I can take the whole balance in a partial withdrawal.” Third: “If I get a job later, my old balance just carries on.”
“Two months.” That was the old rule. The new EPF rules are stricter. Under Para 49(2) of the EPF Scheme, 2026, if the case is not one of the listed situations, a full withdrawal needs 12 continuous months out of covered employment. Female members resigning to get married are exempt from the wait. Full withdrawal is also allowed on retirement after 55, permanent incapacity, retrenchment, a voluntary retirement scheme or permanent migration.
“The whole balance.” No. A partial withdrawal must leave a Minimum Balance of 25%. The rest, called the Eligible Member Balance, can be withdrawn for listed purposes after 12 months of membership.
“My balance just carries on.” Only if it is transferred. When you join another covered employer, you can apply on the portal for transfer, and automatic transfer can be provided after identity checks. If you withdraw under Para 49(2) and later take a covered job, you are treated as a fresh member.
Dhruv’s mistake was planning business money around old EPF rules. He chose the partial withdrawal route and kept the rest invested.
Partial withdrawal under the EPF rules: the equation and the limits (Para 46)
Equation: how much you can take
Minimum Balance = 25% x (all contributions by you and employer, plus interest, up to the date of withdrawal)
Eligible Member Balance = Your balance – Minimum Balance
Each withdrawal can be up to 100% of the Eligible Member Balance, and at least ₹1,000
Minimum Balance = 25% x (all contributions by you and employer, plus interest, up to the date of withdrawal)
Eligible Member Balance = Your balance – Minimum Balance
Each withdrawal can be up to 100% of the Eligible Member Balance, and at least ₹1,000
| Purpose | How much | Condition |
|---|---|---|
| Illness of self or family | Up to 100% of Eligible Member Balance | 12 months of total membership |
| Education of self or family | Up to 100% of Eligible Member Balance | 12 months of membership, up to 10 times in the membership |
| Marriage of self or family | Up to 100% of Eligible Member Balance | 12 months of membership, up to 5 times |
| Housing: buy or build a house or flat, buy a site, repay a home loan, additions or renovation | Up to 100% of Eligible Member Balance | 12 months of membership, up to 5 times |
| Special circumstances | Up to 100% of Eligible Member Balance | 12 months of membership, up to 2 times in a financial year |
| Exit before 12 months of membership | Not more than Eligible Member Balance | Partial withdrawal still allowed |
The counts of 10, 5 and 2 are worked out afresh for each member from the date the new scheme started. The scheme does not list reasons under special circumstances. News reports say no reason is needed, but please check on the EPFO portal.
Dhruv’s partial withdrawal in numbers
Dhruv’s total contributions plus interest up to today are ₹8,00,000, with no earlier withdrawal. Illustrative numbers.
| Step | Calculation | Result |
|---|---|---|
| Minimum Balance | 25% x ₹8,00,000 | ₹2,00,000 |
| Eligible Member Balance | ₹8,00,000 – ₹2,00,000 | ₹6,00,000 |
| Withdrawal 1: education of a family member | Say ₹3,00,000, within ₹6,00,000 | ₹3,00,000 taken, ₹5,00,000 left |
| Eligible balance now | ₹5,00,000 – ₹2,00,000 (minimum stays) | ₹3,00,000 |
| Withdrawal 2: home loan repayment | Say ₹3,00,000, within ₹3,00,000 | ₹3,00,000 taken, ₹2,00,000 left |
Illustrative only. This is our reading of the Minimum Balance definition. Please confirm the method on the EPFO portal.
Full withdrawal under the EPF rules: when is it allowed? (Para 49)
| Situation | Rule |
|---|---|
| Retirement after 55 | Full amount. Also if you reach 55 before the payment is authorised |
| Permanent and total incapacity | Full amount, with the medical certificate the scheme requires |
| Permanent migration or employment abroad | Full amount, just before leaving India |
| Retrenchment or voluntary retirement scheme | Full amount |
| Some closure and transfer cases, or discharge with retrenchment compensation | Full amount, but paid only after a continuous period of at least 2 months |
| All other cases (for example, resigning) | Full amount after 12 continuous months out of covered employment. Exempt for women resigning to get married |
Reports say the Labour Ministry later allowed a larger advance for people who lose their jobs. The scheme text we read does not contain it, so please check with EPFO before you plan around it.
Tax on withdrawal under the EPF rules: the third E
Dhruv’s question next was, “Will I pay tax if I take my money out?” The answer depends on how long he served. This is the equation for TDS.
Equation: TDS on an early full withdrawal
TDS = 10% x Withdrawal amount, if the amount is ₹50,000 or more and no exemption applies
Example: 10% x ₹8,00,000 = ₹80,000 (TDS is not the final tax)
TDS = 10% x Withdrawal amount, if the amount is ₹50,000 or more and no exemption applies
Example: 10% x ₹8,00,000 = ₹80,000 (TDS is not the final tax)
| Situation | Tax position (same in old and new regime) |
|---|---|
| Withdrawal after 5 years of continuous service | Exempt (Schedule XI Part A para 8) |
| Service ended due to ill-health, closure of the business or causes beyond your control | Exempt |
| Balance moved to a new employer’s recognised PF | Exempt. No tax on transfer |
| Entire balance moved to NPS under Section 124 | Exempt |
| Withdrawal before 5 years, none of the above | Taxable. TDS of 10% if ₹50,000 or more (Section 392(7), earlier Section 192A). Final tax depends on your slab |
| Partial withdrawal for education, marriage or housing | Depends on the 5-year rule and the case. Please confirm with your CA |
Dhruv had worked for 6 years, so his withdrawal was exempt under the 5-year rule. Had he resigned at 3 years, he would have faced tax and TDS. Please note that the Act text we read still names the old 1952 scheme, and the 5-year count should be checked for your case. Our old vs new tax regime guide and tax computation guide explain how the two regimes compare.
Transfer, nomination and claims under the EPF rules
- Transfer: apply on the portal when you change jobs. Do not withdraw and re-join. Automatic transfer can be provided after identity checks.
- Nomination (Para 44): make it on the e-nomination portal. If you have a family, the nominee must be a family member. File a fresh nomination after marriage, and replace any nomination made under the old 1952 scheme.
- Claims: a complete claim should be settled within 20 days of receipt, with 12% a year penal interest on delay beyond that. If a claim has a gap, EPFO should tell you within 20 days.
- Inoperative account: if a member who retired after 55, migrated abroad or died has not applied within 36 months, the money moves to an Inoperative Account. It can still be paid later.
- NPS option: for NPS rules, read our NPS withdrawal rules guide.
EPF Rules Part 2: The EPS Pension
Under the EPF rules, EPS is the pension that comes out of the employer’s 12%. You do not pay anything extra. It gives a monthly pension after at least 10 years of eligible service.
EPF Rules Story 3: Rajesh in Indore and the Half-Salary Pension
Rajesh is 52. He is a supervisor at a manufacturing unit near Indore. His salary (basic + DA) is ₹50,000 a month and he has 30 years of service. He told his family: “At 58 I will get a pension of half my last salary, ₹25,000, like a government employee.”
Rajesh believed three things. First: “EPS pension is half my last salary.” Second: “If I stop at 55, I get the same pension.” Third: “If I wait till 60, nothing changes.”
“Half my salary.” No. EPS follows an equation (Equation 2). The pensionable salary is the average of the last 60 months, limited to ₹15,000, so Rajesh’s ₹50,000 counts as ₹15,000. With 30 years of service, and 2 extra years of weightage for retiring at the age of superannuation, the pension is ₹15,000 x 32 / 70, which is about ₹6,857 a month. Not ₹25,000.
“Same pension at 55.” No. Early pension can start from age 50, but it is reduced by 4% for every year short of the age of superannuation. At 55, with 3 years short, the cut is 12%.
“Nothing changes at 60.” It does. Pension can be deferred up to age 60, and it rises by 4% for every completed year of deferral.
Rajesh’s mistake was borrowing a rule from a different system. The EPF rules for pension are their own. He worked out his own range, instead of assuming a number.
Equation 2 again: EPS pension
Pensionable salary = average salary of last 60 months, limited to the ceiling
Pension = (Pensionable salary x Pensionable service) / 70
At superannuation with 20 or more years: add 2 years of weightage to service
Early pension: reduce the pension by 4% for every year short of the age of superannuation (from age 50)
Deferred pension: increase by 4% for every completed year of deferral (up to age 60)
Pensionable salary = average salary of last 60 months, limited to the ceiling
Pension = (Pensionable salary x Pensionable service) / 70
At superannuation with 20 or more years: add 2 years of weightage to service
Early pension: reduce the pension by 4% for every year short of the age of superannuation (from age 50)
Deferred pension: increase by 4% for every completed year of deferral (up to age 60)
| Rajesh’s choice | Pensionable service | Calculation | Monthly pension (approx.) |
|---|---|---|---|
| Retire at the age of superannuation | 32 years (30 + 2 weightage) | ₹15,000 x 32 / 70 | ₹6,857 |
| Early pension at 55 (3 years short) | 30 years (no weightage) | ₹15,000 x 30 / 70 = ₹6,429, less 12% | ₹5,657 |
| Defer by 2 years, claim at 60 | 32 years | ₹6,857 plus 8% (4% x 2 years) | ₹7,406 |
| For comparison: no limit (not payable) | 32 years | ₹50,000 x 32 / 70 | ₹22,857 |
Illustrative only. We assume a ₹15,000 limit throughout. The scheme uses the limit that applied in each period, so actual pensions can be lower. The age of superannuation and the weightage should be confirmed with EPFO for your case. Pension is taxable as income.
The last row shows what the ₹15,000 limit takes away. A higher EPS contribution is possible only for members who exercised the joint option and were found eligible. For them, the scheme says the employer contribution is 9.49% on salary above ₹15,000. Please check your status with the EPFO office.
EPS and the EPF rules in one list
- Eligibility: at least 10 years of eligible service for a pension. Service is rounded to the nearest year, with 6 months or more counted as a year.
- Minimum pension: ₹1,000 a month, subject to the deductions listed in the scheme.
- If you leave before 10 years: you can take a withdrawal benefit, but only after 36 months from the date the last contribution became due, or on reaching the age of superannuation. Or you can take a scheme certificate, which keeps your service on record and adds it to a future job.
- Disability: a member who becomes permanently and totally disabled during employment gets a pension with a minimum of ₹250 a month, if at least one month’s contribution was paid.
- Family: widow or widower pension, with a minimum of ₹1,000 a month. Children’s pension is 25% of the widow pension for up to two children until age 25. Orphan pension is 75% of the widow pension, with the minimum set in the scheme.
- Tax: the monthly pension is taxable as income, in both regimes.
EPF Rules Part 3: EDLI Insurance Cover
Under the EPF rules, EDLI is a life insurance cover that comes with your PF membership. The employer pays for it. It pays your family an extra amount if you die while in service, on top of your PF balance.
EPF Rules Story 4: Lakshmi in Chennai and the EDLI Claim
Lakshmi is 38. She works as an accountant in Chennai. Her husband Karthik, 41, worked at an IT services firm with a salary (basic + DA) of ₹50,000 a month. Karthik passed away suddenly. Lakshmi knew about his PF balance of about ₹6 lakh. She thought that was all there was.
She believed three things. First: “Only the PF balance comes to us.” Second: “A nominee is not needed, because I am his wife.” Third: “The claim will take months.”
“Only the PF balance.” No. EDLI pays an extra amount in addition to the PF balance. For an employee who had worked continuously for 12 months, the benefit follows Equation 3. Karthik’s ₹50,000 salary is counted only up to ₹15,000, so 35 x ₹15,000 = ₹5,25,000. Add 50% of his average PF balance, capped at ₹1,75,000. The total is ₹7,00,000, which is the maximum.
“A nominee is not needed.” It still helps. Without a nomination, the amount goes to family members in equal shares in the order set in the scheme, which can mean more paperwork. Nominations made under the old 1952 scheme are void to the extent they are inconsistent with the new scheme, so a fresh nomination is needed.
“Months of waiting.” A complete claim must be settled within 20 days of receipt. If the Commissioner fails without good reason, penal interest of 12% a year can be charged.
Lakshmi’s mistake was assuming the PF balance was the whole story. The EPF rules pay the PF balance and EDLI together. She filed for both the PF and EDLI together.
Equation 3 again: EDLI benefit
After 12 months of continuous service:
Benefit = (35 x average monthly salary of last 12 months, limited to ₹15,000) + (50% x average PF balance of last 12 months, this part limited to ₹1,75,000)
The benefit is not less than ₹2,50,000 and not more than ₹7,00,000
For less than 12 months of service:
Basic benefit = average PF balance if up to ₹50,000. If above ₹50,000: ₹50,000 + 40% of the excess, limited to ₹1,00,000. Minimum ₹50,000
After 12 months of continuous service:
Benefit = (35 x average monthly salary of last 12 months, limited to ₹15,000) + (50% x average PF balance of last 12 months, this part limited to ₹1,75,000)
The benefit is not less than ₹2,50,000 and not more than ₹7,00,000
For less than 12 months of service:
Basic benefit = average PF balance if up to ₹50,000. If above ₹50,000: ₹50,000 + 40% of the excess, limited to ₹1,00,000. Minimum ₹50,000
| Karthik’s case | Calculation | Amount |
|---|---|---|
| 35 x salary (limited to ₹15,000) | 35 x ₹15,000 (not ₹50,000) | ₹5,25,000 |
| 50% of average PF balance | 50% x ₹6,00,000 = ₹3,00,000, limited to ₹1,75,000 | ₹1,75,000 |
| Total before limits | ₹5,25,000 + ₹1,75,000 | ₹7,00,000 |
| After limits (min ₹2,50,000, max ₹7,00,000) | Within limits | ₹7,00,000 |
| PF balance, paid separately | As on the date of death, with interest | About ₹6,00,000 |
| Family receives in total | EDLI + PF balance | About ₹13,00,000 |
Illustrative only. The scheme also says the benefit is increased by a further 20% in addition to the amounts under sub-paragraphs (1) or (3). We have not applied it, because the wording is unclear. Please check with EPFO.
A person on a ₹50,000 salary gets the same EDLI as a person on a salary of ₹30,000 with a similar PF balance, because the salary is capped at ₹15,000. The cover cannot go beyond ₹7 lakh.
EDLI and the EPF rules in one list
- Who pays: only the employer. The rate is notified by the Government from time to time. The earlier scheme used 0.5% of salary up to the ceiling. Nothing is deducted from you.
- Gaps in service: a gap of up to 60 days between two jobs is ignored, and the two jobs count as continuous.
- Death soon after leaving: an employee who dies within 6 months of the last contribution, while still on the employer’s rolls, gets the benefit.
- Who gets it: the nominee. If no nomination exists, family members in equal shares.
- Time: a complete claim should be settled within 20 days of receipt.
- Tax: we could not confirm the tax treatment of the EDLI payout in the Act text, so please check with your CA.
EPF Rules: Which Situation Suits What
The EPF rules affect each person differently. Find your row.
- Salaried private employee: check whether your PF runs on the ₹15,000 limit or on your full salary. Our salary income guide covers salary components.
- Frequent job changer: link the same UAN, apply for transfer after every job and avoid withdrawing in between.
- Employee planning a break or a business: remember the 12-month wait, the 25% Minimum Balance and the 36-month EPS rule.
- Higher-salary employee: the limit keeps EPS and EDLI small. Ask whether the employer will contribute on the full salary, and think about VPF within the ₹2.5 lakh limit.
- Family planning: make a fresh e-nomination under the new scheme and tell your family about EDLI.
- Senior executives: corporate benefits and tax planning go together. Our CXO guide covers more.
- NRIs: eligibility and tax rules differ. Start with our NRI retirement planning guide.
- Surat and Gujarat employees: our retirement planning guide for Surat investors explains how EPF fits the rest of the plan.
EPF Rules: Where EPF Helps and Where It Has Limits
Where the EPF rules help most
- Automatic saving. The money is deducted before you see it, so it builds quietly.
- Employer money that is not cut from your salary.
- A government-declared rate that has been 8.25% for three years running, as reported. Rates can change.
- Pension and insurance bundled in. EPS and EDLI come with the membership at no extra cost to you.
- Portability. One UAN, and your balance can follow you from job to job.
Where the EPF rules have limits
- The ₹15,000 limit. It keeps EPS pension and EDLI small for higher salaries.
- EPS pension is small. At the limit, the standard pension is in the range of ₹7,000 to ₹8,000. It does not replace a salary.
- Access is restricted. The 25% Minimum Balance, the 12-month wait and the 36-month EPS rule slow early exits.
- Interest is not fixed. It is decided each year.
- Tax limits. Interest above the ₹2.5 lakh own-contribution limit is taxable, and an early withdrawal can attract tax and TDS.
- Rules change. The 2026 schemes replaced the old ones. Always check the latest.
Many families use EPF as one bucket next to a flexible bucket such as mutual funds. You can try your own numbers on our calculator. Our guide on whether ₹2 crore is enough to retire shows how to think about the full corpus.
Seven EPF Rules Mistakes to Avoid
- Assuming 12% of your full salary goes into PF, when the default is 12% of ₹15,000.
- Assuming the whole employer share goes into the EPF balance.
- Planning a full withdrawal two months after resigning.
- Forgetting that a partial withdrawal must leave a 25% Minimum Balance.
- Expecting an EPS pension of half your salary, when the ₹15,000 limit and the 10-year rule apply.
- Not filing a fresh nomination under the new scheme.
- Withdrawing before 5 years of service without checking the tax and TDS position.
EPF Rules Checklist: Seven Questions Before You Act
Use this list to apply the EPF rules to your own account.
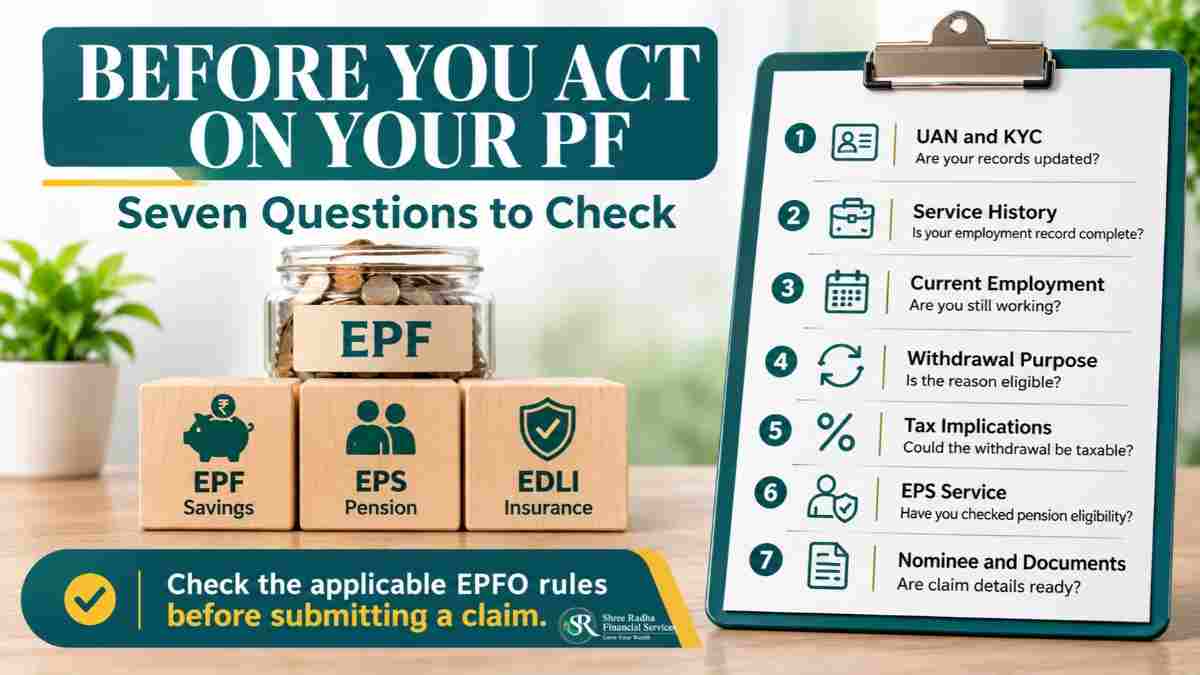
- Is my UAN active, linked with Aadhaar and KYC, and is my PF transferred from past jobs?
- Does my PF run on the ₹15,000 limit or on my full salary? Ask HR.
- Have I filed a fresh e-nomination under the 2026 scheme?
- How many years of EPS service do I have? The 10-year mark matters.
- What does the 25% Minimum Balance leave me for a partial withdrawal?
- If I leave my job, which route applies: transfer, partial withdrawal or full withdrawal after 12 months?
- What is the tax effect for my case? Check the 5-year rule, the ₹2.5 lakh limit and TDS with your CA.
Rules and regulations change from time to time. Please connect with your tax consultant / CA for details specific to your situation. Figures in this article were last verified on 1 November 2026.
EPF Rules: Frequently Asked Questions
What are the main EPF rules in 2026?
The employee and employer each pay 12% of salary up to the ₹15,000 limit, unless both agree to use the full salary. Part of the employer’s share goes to the EPS pension. EDLI insurance is paid by the employer. Partial withdrawal needs 12 months of membership and a 25% Minimum Balance. Full withdrawal is allowed on retirement after 55 and in other listed cases, or after 12 months out of covered employment.
What is the ₹15,000 limit in the EPF rules?
It is the wage ceiling notified by the Government. It limits the salary counted for PF, pension and EDLI. Reports say it is ₹15,000 at present, and the Government can change it.
Is VPF interest tax-free under the EPF rules?
Interest on your own contribution (compulsory and VPF together) is tax-free up to ₹2.5 lakh of contribution in a year, or ₹5 lakh if there is no employer contribution. Interest on the part above the limit is taxable.
Can I withdraw 100% of my EPF while working, under the EPF rules?
Not fully. A partial withdrawal can be up to 100% of the Eligible Member Balance, which is your balance minus the 25% Minimum Balance, for listed purposes. The 25% must stay in the account.
How long must I wait for a full PF withdrawal after leaving a job, under the EPF rules?
Under the scheme text, 12 continuous months out of covered employment, unless the case falls under a listed situation such as retirement after 55 or retrenchment. Please check any later relaxation with EPFO.
Can I withdraw my EPS amount if I have less than 10 years of service?
Yes, as a withdrawal benefit, but only after 36 months from the date the last contribution became due, or on reaching the age of superannuation. You can also take a scheme certificate.
How is the EPS pension calculated under the EPF rules?
Pensionable salary x pensionable service / 70. Pensionable salary is the average of the last 60 months, limited to the ceiling. A member who retires at the age of superannuation with 20 or more years gets 2 years of weightage.
How much does EDLI pay under the EPF rules?
After 12 months of continuous service, not less than ₹2.5 lakh and not more than ₹7 lakh, as per the equation in the scheme. The employer pays for it, and nothing is deducted from your salary.
Is EPF withdrawal taxable under the EPF rules?
Not after 5 years of continuous service, and not in some other listed cases. An early withdrawal can be taxable, and TDS of 10% applies if the payment is ₹50,000 or more and the exemption does not apply. Please confirm with your CA.
This article is also available on Medium for wider reading:https://medium.com/@shreeradha.services/epf-rules-in-2026-one-pf-deduction-three-schemes-16f4ebd88941
Want to See How the EPF Rules Fit Your Retirement Plan?
Connect with Shree Radha Financial Services for a personalized discussion.
📞 Call/WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services, Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN05763
Investing since 2012 | BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN05763). EPF, EPS and EDLI are run by EPFO under the Ministry of Labour and Employment and are not products of this firm. All content is strictly for educational purposes only and does not constitute individualized investment advice. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing. Tax treatment is based on current laws and subject to change. Please consult a qualified tax professional before investing. The characters in this article (Aman, Rohit, Dhruv, Rajesh, Lakshmi and Karthik) are fictional and used only to explain situations. Numbers in the worked examples are illustrative and are not a promise of returns or benefits.