Old Pension in 2026: Why Everyone Is Asking
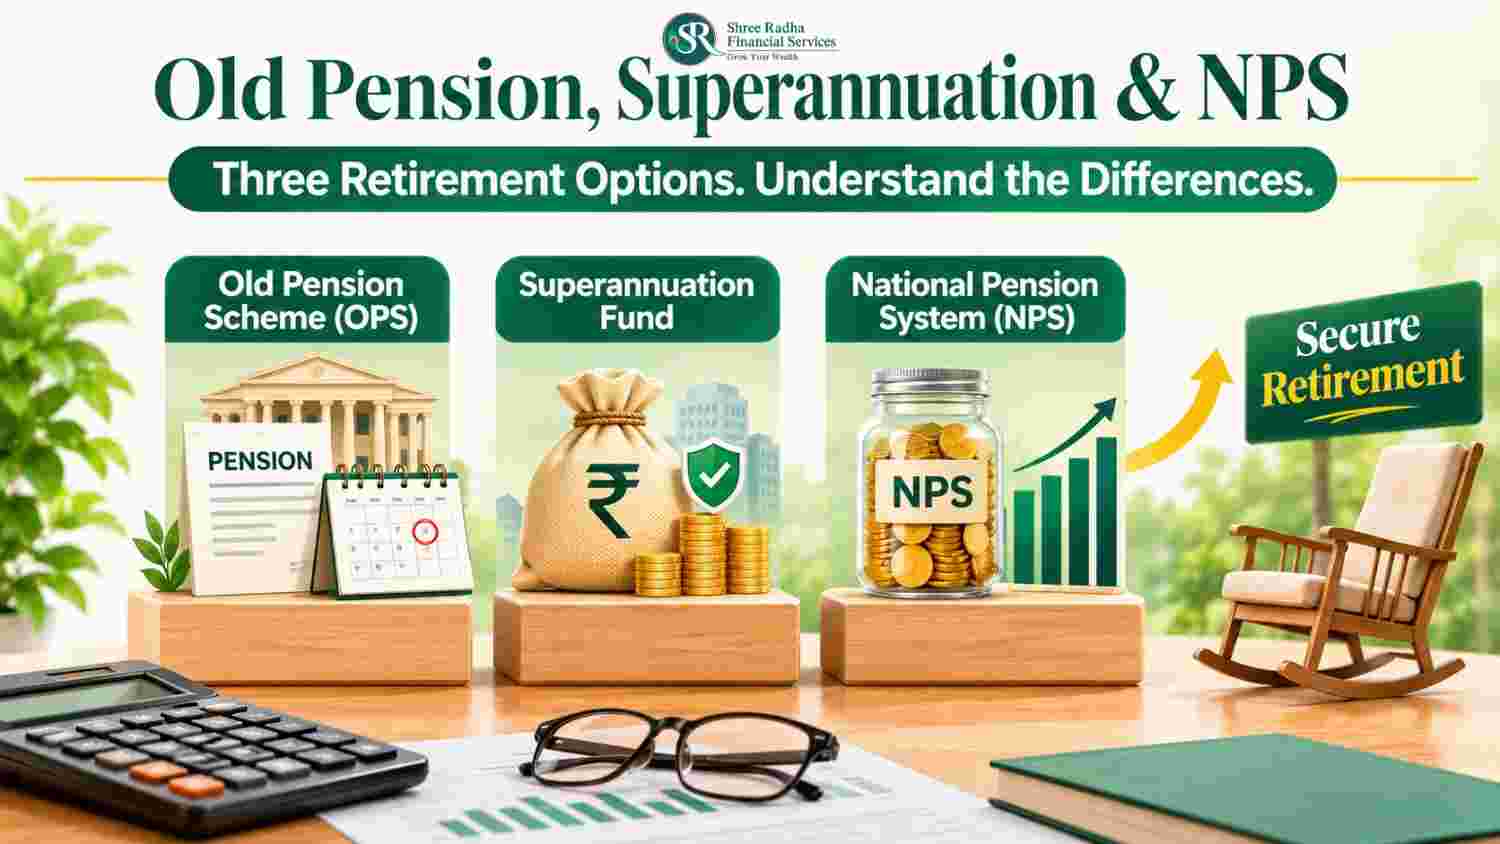
Old pension is back in every office chat. Some people say it is returning. Others say it is gone for good. Meanwhile, private employees see a line called “superannuation” on their salary structure and wonder if it is the same thing. It is not. The old pension scheme, the superannuation fund and NPS are three different products, built in three different ways.
The word “superannuation” itself confuses people. In rules for government service it also means the age at which you retire. In this guide, “superannuation fund” means an employer-funded retirement fund run by a trust. You will meet four people from Delhi, Lucknow, Surat and Hyderabad. Each one believed something about their pension that was only half true. You will see what they thought, where the mistake was, and how it was corrected.
We checked the old pension facts against the Central Civil Services (Pension) Rules, 2021, and the tax and superannuation facts against the Income-tax Act, 2025 and the Income-tax Rules, 2026. You can see the official sites of the Department of Pension and Pensioners’ Welfare and the Income Tax Department. For the wider picture, read our retirement schemes guide and our NPS withdrawal rules guide.
“People compare the old pension and NPS as if they were two versions of the same product. They are not. One is a promise by the government, one is a fund run by an employer, and one is your own market-linked account. Each has its own rulebook.”
— Paresh Chaudhary, Founder, Shree Radha Financial Services
Old Pension, Superannuation Fund and NPS at a Glance
| Point | Old pension scheme (OPS) | Superannuation fund | NPS |
|---|---|---|---|
| Who pays | The government. No employee contribution | The employer, through a trust | The employee and the employer (or the government for its employees) |
| Who takes the risk | The government | The insurer that gives the annuity | You, because it is market-linked |
| What you get | A monthly pension linked to your last basic pay, plus gratuity | An annuity (a pension from an insurer), with a limited part commuted | A corpus, with part taken as lump sum and part as annuity |
| Who is covered | Mainly central government employees appointed on or before 31 December 2003 | Employees of companies that run an approved fund | Government employees after 2003, and any citizen |
Government employees under NPS or UPS are covered in our NPS withdrawal rules guide. This guide goes deeper on the old pension and the superannuation fund.
Old Pension Part 1: The Old Pension Scheme (OPS) in Detail
The old pension scheme for central government employees is set out in the Central Civil Services (Pension) Rules, 2021. These rules apply to government servants appointed on or before 31 December 2003.
Old Pension Story 1: Anil in Delhi and the Retirement Letter
Anil is 59. He joined a central government office in Delhi in 1996, so he has 30 years of qualifying service. His basic pay (called “emoluments” in the rules) is ₹1,00,000 a month. His retirement is a few months away. He had three beliefs.
First: “My pension is 50% of my last pay, whatever my service.” Second: “The gratuity is a small amount, like a farewell gift.” Third: “If something happens to me after retirement, my family gets nothing.”
“50% of my last pay, whatever my service.” Not quite. The pension is 50% of emoluments or average emoluments, whichever is more beneficial to him. Average emoluments are worked out on the last ten months of service. And it is payable only if he has completed at least 10 years of qualifying service. Below 10 years, the rules give a one-time service gratuity, not a pension. The pension is also limited to a minimum of ₹9,000 and a maximum of ₹1,25,000 a month.
“The gratuity is small.” No. The retirement gratuity is one-fourth of emoluments for every completed six-month period of qualifying service, up to a limit of 16½ times the emoluments, and never more than ₹20 lakh. For 30 years, that is ₹15 lakh on ₹1,00,000. Dearness allowance on the date of retirement is also counted as part of the emoluments for the gratuity.
“My family gets nothing.” No. Family pension is payable to the family after the death of a government servant or a pensioner. The rate is higher for the first years, then comes down.
Anil’s mistake was reading the old pension as one number. It is a set of benefits: pension, gratuity, commutation, dearness relief and family pension. He listed each one before he planned his retirement budget.
Who is covered by the old pension?
- Covered: government servants appointed on or before 31 December 2003, including civilian government servants in the Defence Services appointed substantively to civil services and posts in connection with the affairs of the Union.
- Not covered by these rules: railway servants, persons in casual and daily-rated employment, persons paid from contingencies, persons entitled to the benefit of a Contributory Provident Fund, members of the All India Services, and persons locally recruited for service abroad. Please read Rule 2 for the full list.
- Voluntary retirement: a government servant who retires on own volition after 20 years of qualifying service also gets a retiring pension by the same formula (Rules 34 and 43).
The old pension equations
There are three equations. We use basic pay (emoluments) of ₹1,00,000 and 30 years of qualifying service in the next table.
Equation 1: monthly old pension
Pension = 50% x (emoluments or average emoluments of the last 10 months, whichever is more beneficial)
Conditions: at least 10 years of qualifying service. Minimum ₹9,000 and maximum ₹1,25,000 a month
Qualifying service: 3 months or more counts as a completed six-month period. 9 years 9 months counts as 10 years
Pension = 50% x (emoluments or average emoluments of the last 10 months, whichever is more beneficial)
Conditions: at least 10 years of qualifying service. Minimum ₹9,000 and maximum ₹1,25,000 a month
Qualifying service: 3 months or more counts as a completed six-month period. 9 years 9 months counts as 10 years
Equation 2: retirement gratuity
Retirement gratuity = 1/4 x emoluments x number of completed six-month periods of qualifying service
Limits: not more than 16.5 times the emoluments, and not more than ₹20,00,000
Retirement gratuity = 1/4 x emoluments x number of completed six-month periods of qualifying service
Limits: not more than 16.5 times the emoluments, and not more than ₹20,00,000
Equation 3: family pension (after the death of the government servant)
Death in service: 50% of pay for 10 years, then 30% of pay
Death after retirement: 50% of pay for 7 years, or until the retired servant would have turned 67, whichever is less (but not more than the pension authorised), then 30% of pay
Rates have a minimum of ₹9,000. The 50% rate has a maximum of ₹1,25,000 and the 30% rate a maximum of ₹75,000 a month
Death in service: 50% of pay for 10 years, then 30% of pay
Death after retirement: 50% of pay for 7 years, or until the retired servant would have turned 67, whichever is less (but not more than the pension authorised), then 30% of pay
Rates have a minimum of ₹9,000. The 50% rate has a maximum of ₹1,25,000 and the 30% rate a maximum of ₹75,000 a month
Old Pension Worked Example: Anil’s Benefits on ₹1,00,000 of Emoluments
| Benefit | Equation | Anil’s figure |
|---|---|---|
| Monthly pension | 50% x ₹1,00,000 | ₹50,000 a month, plus dearness relief |
| Retirement gratuity | 1/4 x ₹1,00,000 x 60 periods (30 years x 2) | ₹15,00,000 (within the 16.5 times and ₹20 lakh limits) |
| Additional pension from age 80 | 20% x ₹50,000 (age 80 to under 85) | ₹10,000 more, so ₹60,000 plus dearness relief |
| Family pension if Anil dies after retirement | 50% of pay for 7 years or until age 67, whichever is less, then 30% | ₹50,000 a month, then ₹30,000 |
| Family pension if Anil dies in service | 50% of pay for 10 years, then 30% | ₹50,000 a month, then ₹30,000 |
Illustrative only. Pay for family pension is emoluments or average emoluments, whichever is more. Dearness relief is added at rates the Central Government specifies from time to time. Additional pension steps up to 30% at 85, 40% at 90, 50% at 95 and 100% at 100 years.
The scheme also allows a part of the pension to be commuted into a lump sum. The rules send you to the Central Civil Services (Commutation of Pension) Rules, 1981 for the table and limits, so please read those rules or ask your accounts office before you decide.
Tax on the old pension (Income-tax Act, 2025)
The tax rules for salary sit in Section 19(1). Earlier these were Sections 10(10) and 10(10A) under the 1961 Act. The retirement benefits are treated the same way in the old and the new tax regime. You can compare the regimes in our old vs new tax regime guide.
| Benefit | Tax position |
|---|---|
| Death-cum-retirement gratuity of a government employee | Entire amount exempt (Section 19(1) Table Sl. 3) |
| Commutation of pension under the Civil Pensions (Commutation) Rules or similar schemes for civil, State or defence employees | Entire amount exempt (Sl. 7) |
| Commutation of pension from other employers | Commuted value of one-third of the pension if gratuity was received, one-half if not (Sl. 8) |
| Monthly pension | Taxable as income |
Is the old pension coming back?
This is a policy question, and policies change. Here is what the public record shows, with dates. We do not take a side.
- As of 31 July 2025, five states (Rajasthan, Chhattisgarh, Jharkhand, Punjab and Himachal Pradesh) had informed the Centre or PFRDA about a reversion to the old pension. A parliamentary reply also noted that Punjab continued to pay employee and government contributions to NPS. Please check the latest position for your state.
- PFRDA told some of those states that the law has no provision to return the NPS corpus to a state government.
- A reply reported in December 2025 said the Centre had no proposal to restore the old pension for central employees who are under NPS or UPS.
Old Pension Story 2: Deepak in Lucknow and the Hope of a Comeback
Deepak is 44. He teaches in a state government school in Lucknow and joined in 2008. His staff room is full of talk about the old pension. He believed three things. First: “The old pension will return for everyone soon.” Second: “Central rules apply to me too.” Third: “So NPS does not matter any more.”
“It will return for everyone.” There is no way to say that. The central rules cover government servants appointed on or before 31 December 2003. For state employees, each state decides its own rules, and they can change. A few states have said they reverted to the old pension. Others have not.
“Central rules apply to me.” No. The Central Civil Services (Pension) Rules, 2021 apply to the central government. A state employee follows the state’s own orders.
“NPS does not matter.” It does, until a state order says otherwise. His NPS account is real money, and it has a nominee, an investment choice and a withdrawal rule.
Deepak’s mistake was waiting for news instead of looking at his own order. He asked his department for the latest government order, kept a copy, updated his nominee and read the NPS basics in our NPS withdrawal rules guide.
Old Pension Part 2: The Superannuation Fund
Most people with a “superannuation” line on their salary structure work in the private sector or in a company that is not part of the government. This part explains it.
Old Pension Story 3: Hardik in Surat and the Line on His Salary Structure
Hardik is 38. He is a plant manager at a chemical company in Surat, with a salary (basic + DA) of ₹1,00,000 a month. His salary structure has a line called “superannuation”. He believed three things. First: “It is a government pension, like the old pension.” Second: “It is the same as NPS.” Third: “If I resign, I lose it, or I get all of it back.”
“A government pension.” No. A superannuation fund is set up by the employer under an irrevocable trust. The fund exists to pay annuities to employees on retirement at or after a specified age, on becoming incapacitated, and to widows, children or dependants on death. The employer must contribute to it.
“Same as NPS.” No. NPS is your own market-linked account. In a superannuation fund, the trustees arrange the annuity through an insurance scheme with LIC or another insurer, or buy an annuity at retirement, death or incapacity.
“I lose it, or I get all back.” Neither is exactly right. The Income-tax Act exempts payments on death, on commutation of an annuity at retirement or incapacity, and in a few other listed cases. Other payments to an employee during his lifetime, such as a refund on leaving service, have tax deducted at the average rate of the last three years (or the period of membership, if less).
Hardik’s mistake was treating the line as a salary item. It is an employer-funded retirement fund with its own rules. He asked his HR team for the trust deed summary, and read the plan before he decided about his next job.
How the superannuation fund works
- Set up: an irrevocable trust in India with at least two trustees who live in India, approved by the tax authorities. The fund must be set up in connection with a trade or undertaking carried on in India, with at least 90% of employees employed in India.
- Who contributes: the employer. Contributions are made to provide annuities. The employer cannot take money out of the fund and has no lien on it.
- Annuities: the trustees either enter into an insurance scheme with LIC or another insurer, or accumulate the contributions and buy an annuity at retirement, death or incapacity. The employee has no interest in the insurance policy itself, only in the annuity.
- Benefits are paid in India. All annuities, pensions and other benefits from the fund are payable only in India.
The superannuation equations
Two equations matter. The first is the limit on what the employer can put in for one employee in a year.
Equation 4: employer’s yearly contribution limit
Maximum yearly contribution = 27% x salary for the year – employer’s PF contribution for the same year
Example: salary ₹12,00,000 a year (₹1,00,000 a month). 27% x ₹12,00,000 = ₹3,24,000
Maximum yearly contribution = 27% x salary for the year – employer’s PF contribution for the same year
Example: salary ₹12,00,000 a year (₹1,00,000 a month). 27% x ₹12,00,000 = ₹3,24,000
| Hardik’s employer | Employer PF in the year | Maximum superannuation contribution |
|---|---|---|
| PF on the ₹15,000 ceiling (12% x ₹15,000 x 12) | ₹21,600 | ₹3,24,000 – ₹21,600 = ₹3,02,400 |
| PF on the full salary (12% x ₹1,00,000 x 12) | ₹1,44,000 | ₹3,24,000 – ₹1,44,000 = ₹1,80,000 |
Illustrative only. This is the limit in Rule 305 of the Income-tax Rules, 2026. It is a ceiling, not what a company actually pays. Please ask your HR team what applies to you.
The second equation is the limit on how much of the annuity can be turned into a lump sum, called commutation.
Equation 5: commutation limit
Commuted value of at most 1/3 of the annuity, if the employee gets gratuity
Commuted value of at most 1/2 of the annuity, if the employee gets no gratuity
The commuted value depends on age, health, interest rate and official mortality tables
Commuted value of at most 1/3 of the annuity, if the employee gets gratuity
Commuted value of at most 1/2 of the annuity, if the employee gets no gratuity
The commuted value depends on age, health, interest rate and official mortality tables
For example, if the annuity is ₹30,000 a month and the employee gets gratuity, the commuted portion is the value of ₹10,000 a month of it. How big the lump sum is depends on those tables and on the insurer. This is why the lump sum should be checked with the insurer before you decide.
Tax on the superannuation fund (Income-tax Act, 2025)
The fund is covered by Schedule XI Part B and the exemptions are in Schedule II Sl. 8. Earlier the exemption was in Section 10(13) under the 1961 Act. The rules are the same in the old and the new regime.
| Stage | Tax position |
|---|---|
| Employer’s contribution | Not taxed in your hands within the limit. The total employer contribution to PF, NPS and an approved superannuation fund above ₹7,50,000 in a tax year is taxable as a perquisite, along with the yearly interest or growth on that excess (Section 17(1)(h)-(i)) |
| Payment on death, or commutation of an annuity on retirement or incapacity | Exempt (Schedule II Sl. 8) |
| Transfer of the balance to your NPS account | Exempt (Schedule II Sl. 8) |
| Other payments to you during your lifetime, for example a refund on leaving service | Tax deducted at the average rate of tax of the last three years, or the period of membership if less (Schedule XI Part B para 7) |
| Monthly annuity | Taxable as income |
Please confirm the exact position for your fund with your tax consultant or CA, because the trust deed decides what is paid and when.
Old Pension Story 4: Nisha in Hyderabad and the ₹7.5 Lakh Line
Nisha is 41. She heads finance at a pharma company in Hyderabad, with a salary (basic + DA) of ₹40,00,000 a year. Her company contributes to her PF, to corporate NPS and to a superannuation fund. She believed three things. First: “Whatever my employer puts in is tax-free.” Second: “The old pension is better because it has no limits like these.” Third: “At retirement I can turn the full annuity into cash.”
“All employer money is tax-free.” There is a ceiling. The employer’s contributions to PF, NPS and an approved superannuation fund are counted together. Above ₹7,50,000 in a tax year, the excess is taxable as a perquisite, along with the interest or growth on it.
“The old pension has no limits.” It has its own limits. The old pension has a minimum of ₹9,000 and a maximum of ₹1,25,000 a month, and a ₹20 lakh limit on gratuity. Each product has rules and limits, and none is a free lunch.
“I can cash out the full annuity.” No. Commutation is limited to the commuted value of one-third of the annuity if she gets gratuity, or one-half if not.
Nisha’s mistake was adding up only one of her three employer contributions. She added them all, and then checked the total against the ceiling.
Nisha’s employer contributions, added up
Equation 6: employer contributions tested against the ceiling
Employer total = PF + NPS + superannuation
Taxable excess = Employer total – ₹7,50,000 (if the total is higher)
Employer total = PF + NPS + superannuation
Taxable excess = Employer total – ₹7,50,000 (if the total is higher)
| Contribution (illustrative) | Amount in the year |
|---|---|
| Employer PF (12% on the ₹15,000 ceiling) | ₹21,600 |
| Employer NPS (10% of ₹40,00,000) | ₹4,00,000 |
| Employer superannuation fund | ₹3,50,000 |
| Total | ₹7,71,600 |
| Taxable excess over ₹7,50,000 | ₹21,600, plus the growth on it |
Illustrative only. The ₹3,50,000 is below the 27% limit. The NPS employer limit in the new tax regime is up to 14% of salary and in the old regime 10% for a private employer (Section 124). Please confirm with your CA.
This is why senior executives look at the whole salary structure and not one line. Our CXO guide covers more.
Old Pension Part 3: NPS in Short
NPS is your own market-linked account, regulated by PFRDA. We cover it in full in our NPS withdrawal rules guide. Here is what matters for the comparison.
- Risk: you bear the market risk. The pension depends on the corpus and the annuity rate, so it is not fixed.
- At exit: a government employee can take up to 60% as a lump sum and must put at least 40% into an annuity. A non-government subscriber with a corpus above ₹12 lakh can take up to 80% and must put at least 20% into an annuity.
- Tax: up to 60% of the corpus is tax-free (Schedule II Sl. 6, earlier Section 10(12A)/(12B)). The monthly pension is taxable.
- Employer contribution: the deduction under Section 124(1)-(2) (earlier 80CCD(2)) works in both tax regimes, up to 14% in the new regime.
- UPS: a central government option inside NPS, covered in the NPS withdrawal rules guide.
Old Pension, Superannuation Fund and NPS Compared
| Point | Old pension scheme (OPS) | Superannuation fund | NPS |
|---|---|---|---|
| Pension amount | 50% of emoluments or average emoluments, after 10 years of service, within ₹9,000 to ₹1,25,000 | Depends on contributions, the insurer and the annuity chosen | Depends on the corpus and the annuity rate |
| Lump sum | Gratuity, plus commutation as per the 1981 rules | Commutation of at most one-third or one-half of the annuity | Up to 60% (government) or 80% (non-government) |
| Inflation | Dearness relief as specified | None unless the annuity type has escalation | None unless the annuity type has escalation |
| Family | Family pension (50% for a period, then 30%) | Annuity options for dependants, as per the fund rules | Corpus can go to the nominee, or an annuity for the family |
| Portability | Only within government service | Depends on the fund. Transfer to NPS is exempt from tax | Portable across jobs |
| Tax on the final lump sum | Gratuity and commutation exempt | Exempt in listed cases. Other refunds taxed at the average rate | 60% exempt. The rest is taxable |
| Who it is for | Central employees appointed on or before 31 Dec 2003 | Employees of companies with an approved fund | Government employees after 2003 and any citizen |
The EEE check for all three
EEE means exempt when you invest, exempt while it grows, exempt when you withdraw. All three have limits.
| Stage | Old pension (OPS) | Superannuation fund | NPS |
|---|---|---|---|
| Contribution | None from you. The government pays | Employer pays. Counts toward the ₹7.5 lakh yearly ceiling with PF and NPS | Employer deduction in both regimes (up to 14% in the new regime). Your own deduction in the old regime only |
| Growth | Not applicable. The government carries it | Held by the trust and insurer. The tax on the fund is not covered in this guide | No tax inside NPS |
| Final payment | Gratuity and commutation exempt. Pension taxable | Listed payments exempt. Annuity taxable | 60% exempt. Annuity taxable |
| Old vs new regime | Same | Same | Employer deduction same. Own deduction old regime only |
Our tax computation guide and salary income guide explain how the new Act works in simple steps.
Old Pension: Which Situation Suits What
- Central employee appointed on or before 31 December 2003: the old pension rules apply. List each benefit and its limit.
- Central employee appointed after 2003: NPS or UPS applies. Read our NPS withdrawal rules guide.
- State government employee: follow your department’s latest order. Do not assume central rules.
- Private employee with a superannuation line: ask HR for the trust summary, the insurer and the contribution level.
- Employee with PF, NPS and superannuation together: add the employer contributions and check the ₹7.5 lakh ceiling.
- NRIs: eligibility and tax rules differ. Start with our NRI retirement planning guide.
- Surat and Gujarat employees: our retirement planning guide for Surat investors shows how these pieces fit the rest of the plan.
Many families keep a safe bucket such as PPF next to a flexible bucket. You can try your own numbers on our calculator. Our guide on whether ₹2 crore is enough to retire shows how to think about the full corpus.
Seven Old Pension Mistakes to Avoid
- Assuming the old pension is for every government employee. It covers those appointed on or before 31 December 2003, with exclusions.
- Treating the old pension as one number, and forgetting gratuity, commutation, dearness relief and family pension.
- Expecting a pension with less than 10 years of qualifying service.
- Assuming central rules apply to state employees.
- Reading a superannuation line as a government pension or as NPS.
- Adding only one employer contribution and missing the ₹7.5 lakh ceiling across PF, NPS and superannuation.
- Assuming the whole annuity can be commuted into cash.
Old Pension Checklist: Seven Questions Before You Plan
Use this list to apply the old pension and superannuation rules to your own situation.
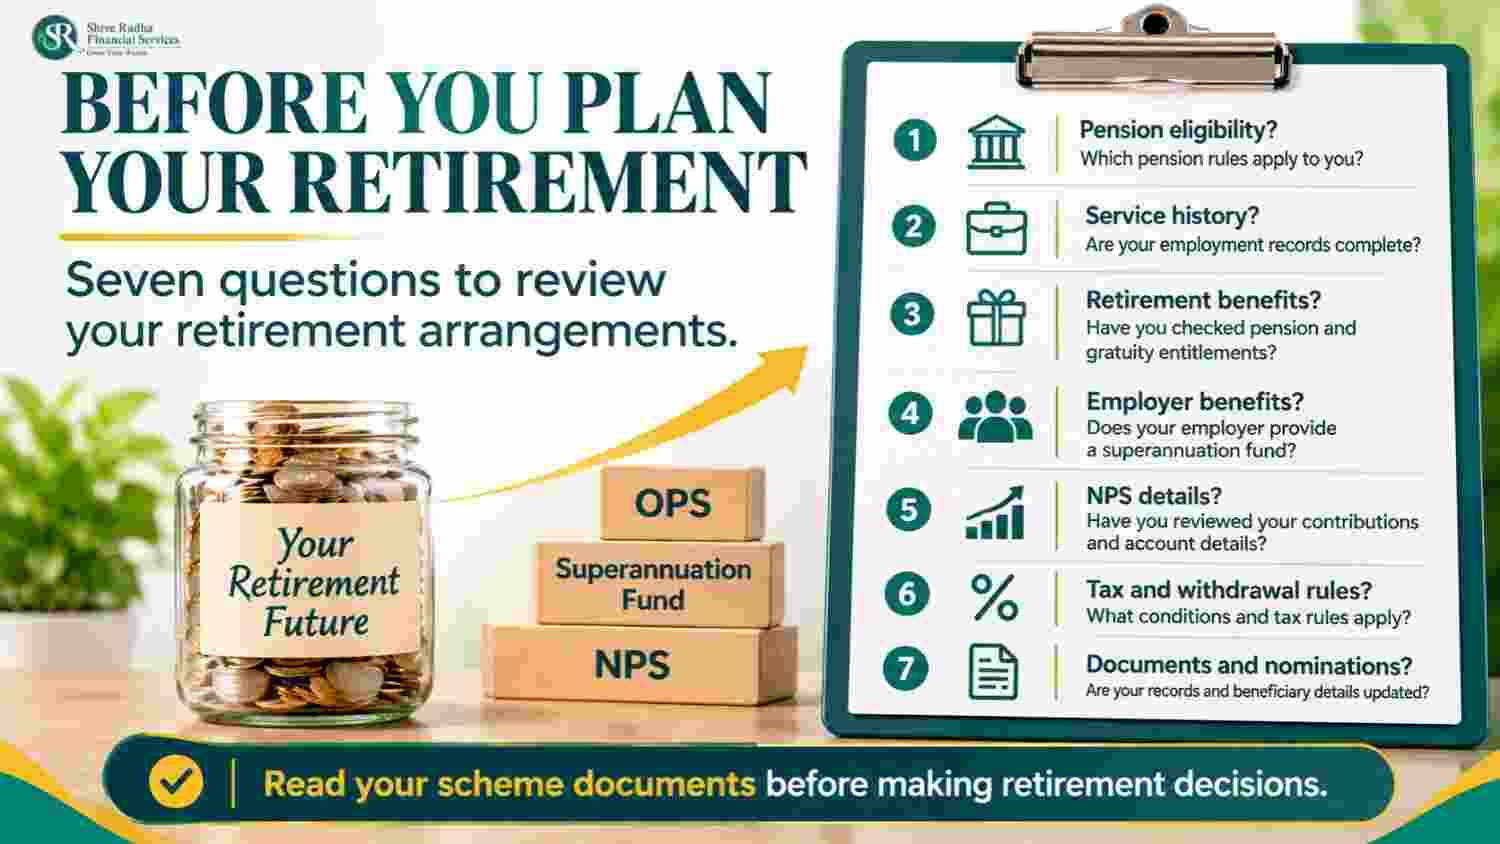
- Which pension am I under? The old pension, NPS or UPS, or a company fund.
- Was I appointed on or before 31 December 2003? That decides the central old pension.
- How many years of qualifying service will I have? The 10-year mark matters.
- What are my gratuity, commutation and family pension numbers? Write each one down.
- Does my salary structure have a superannuation line? Ask HR for the trust summary and the insurer.
- What do my employer contributions add up to? Test the total against ₹7.5 lakh a year.
- What is the tax effect for my case? Check with your CA.
Rules and regulations change from time to time. Please connect with your tax consultant / CA for details specific to your situation. Figures in this article were last verified on 3 November 2026.
Old Pension: Frequently Asked Questions
Who is covered by the old pension scheme?
Under the Central Civil Services (Pension) Rules, 2021, government servants appointed on or before 31 December 2003, with some exclusions such as railway servants, All India Services and persons entitled to a Contributory Provident Fund. State employees follow their state’s orders.
How is the old pension calculated?
50% of emoluments or average emoluments of the last 10 months, whichever is more beneficial, after at least 10 years of qualifying service. The pension has a minimum of ₹9,000 and a maximum of ₹1,25,000 a month.
What if I have less than 10 years of service?
You do not get a pension. You get a service gratuity of half a month’s emoluments for every completed six-month period of qualifying service. 9 years and 9 months counts as 10 years.
How much gratuity does the old pension give?
One-fourth of emoluments for every completed six-month period of qualifying service, up to 16.5 times the emoluments and never more than ₹20 lakh. It is exempt from tax for a government employee.
Is the old pension coming back?
Five states told the Centre or PFRDA that they reverted to it, as of 31 July 2025. A reply reported in December 2025 said the Centre had no proposal to restore it for central employees under NPS or UPS. Please check the latest position for your own state or department.
What is a superannuation fund?
An employer-funded retirement fund held in a trust. It provides annuities on retirement, incapacity or death. The trustees arrange the annuity with LIC or another insurer.
Is superannuation the same as NPS?
No. A superannuation fund is run by the employer and gives an annuity. NPS is your own market-linked account regulated by PFRDA.
Can I take the whole superannuation annuity as cash?
No. The commuted value is limited to one-third of the annuity if you get gratuity, and one-half if not.
Is the superannuation fund taxable?
Payments on death and on commutation of an annuity at retirement or incapacity are exempt. Other payments during your lifetime have tax deducted at the average rate of the last three years. The monthly annuity is taxable. Please confirm with your CA.
This article is also available on Medium for wider reading: https://medium.com/@shreeradha.services/old-pension-superannuation-fund-and-nps-three-different-products-e253b44864b2
Want to See How the Old Pension and NPS Fit Your Retirement Plan?
Connect with Shree Radha Financial Services for a personalized discussion.
📞 Call/WhatsApp: +91 98791 13255
📧 Email: shreeradha.services@gmail.com
🌐 Visit: www.srwealth.co.in
📍 Shop 33, Mira Nagar 2, Dindoli Road, Surat 394210
Paresh Chaudhary
Founder, Shree Radha Financial Services, Surat
AMFI Registered Mutual Fund & SIF Distributor — ARN: 268390
APMI Registered PMS Distributor — APRN05763
Investing since 2012 | BE Mechanical, SVNIT Surat | Ex-L&T (15+ Years)
Educational Disclaimer: This article is published by Shree Radha Financial Services — an AMFI Registered Mutual Fund & SIF Distributor (ARN: 268390) and APMI Registered PMS Distributor (APRN05763). The old pension scheme, superannuation funds and NPS are governed by the Government, trusts and insurers, and PFRDA, and are not products of this firm. All content is strictly for educational purposes only and does not constitute individualized investment advice. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing. Tax treatment is based on current laws and subject to change. Please consult a qualified tax professional before investing. The characters in this article (Anil, Deepak, Hardik and Nisha) are fictional and used only to explain situations. Numbers in the worked examples are illustrative and are not a promise of benefits or returns.